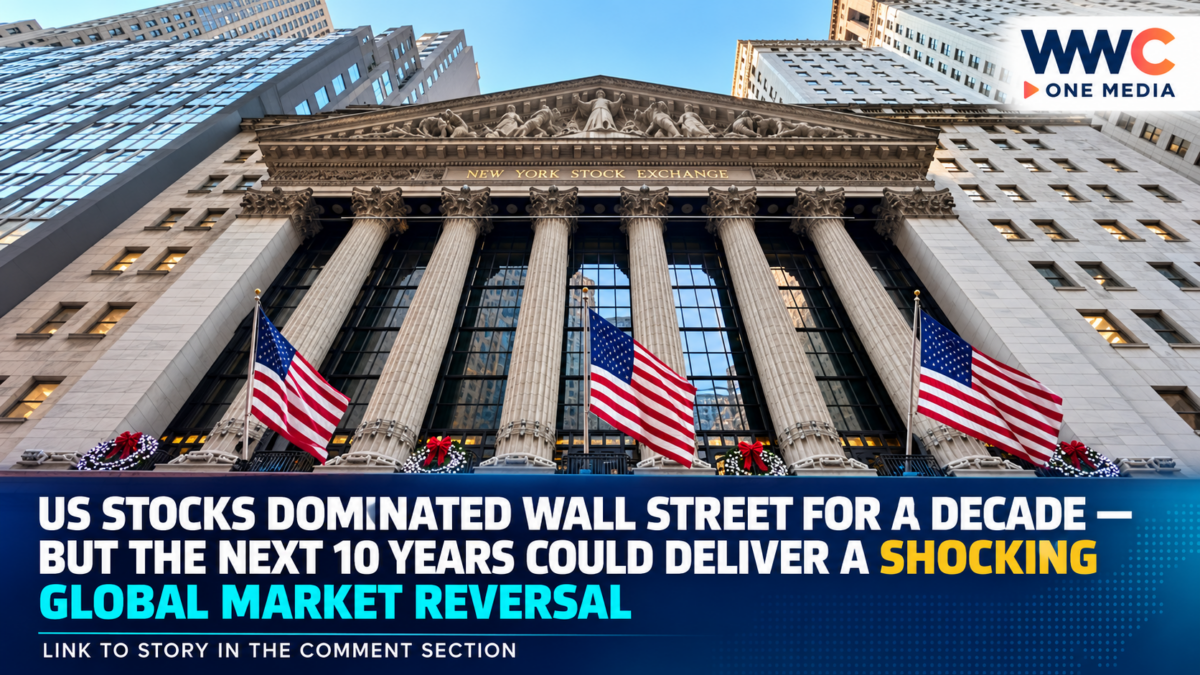
NEW YORK, October 14, 2026 — American stocks have dominated global investment portfolios for much of the past decade, generating enormous wealth through technology innovation, powerful corporate earnings and the rise of trillion-dollar companies.
But as Wall Street enters a new era marked by artificial intelligence, expensive stock valuations, rising borrowing costs and changing global economic conditions, investors are confronting a question that could reshape financial markets:
Will the United States continue to dominate global stock returns over the next decade, or is the world’s next major investment opportunity emerging elsewhere?
The debate is gaining urgency as investment managers reconsider whether the factors behind America’s extraordinary market performance can continue driving returns through 2036.
While major US stock indexes remain near historic highs, forecasts from leading investment research firms suggest the next decade may look significantly different from the last.
America’s Decade of Stock Market Dominance
The US stock market has benefited from an exceptional combination of technological leadership, strong profitability and investor demand for the world’s largest companies.
Technology giants such as Apple, Microsoft, Nvidia, Alphabet, Amazon and Meta Platforms have become central forces in global equity markets.
Their expansion has helped push the S&P 500 and Nasdaq to historic levels, while the development of artificial intelligence has introduced another major investment cycle.
A strong US dollar during portions of the past decade also boosted American investments relative to overseas assets when returns were measured in dollar terms.
For investors who concentrated their portfolios in US equities, the strategy often delivered impressive results.
However, the same concentration that fueled those gains could create vulnerabilities if market leadership begins to change.
The Next Decade Could Bring Lower US Stock Returns
One of the clearest warnings comes from Vanguard, one of the world’s largest asset managers.
In its July 22, 2026, capital markets forecast, Vanguard projected average annualized returns for broad US equities of approximately 4.2% to 6.2% over the following decade.
That range is materially more restrained than the returns investors became accustomed to during some of Wall Street’s strongest years.
The firm’s models also projected annualized returns of approximately 4.5% to 6.5% for developed markets outside the United States.
For emerging-market equities, the projected range was approximately 2% to 4%.
These estimates do not guarantee that overseas markets will outperform American shares.
Instead, they demonstrate how expensive valuations and changing economic expectations may influence long-term investment outcomes.
Vanguard has emphasized that even when markets appear overvalued, those valuations are unreliable indicators of short-term performance.
That means US stocks could continue climbing before any meaningful change in global market leadership.
The Artificial Intelligence Boom Faces Its Biggest Profitability Test
Artificial intelligence has become one of the most influential drivers of US equity valuations.
Companies developing advanced semiconductors, cloud computing platforms and AI infrastructure have attracted substantial investment.
Nvidia and other semiconductor businesses have benefited from enormous demand for hardware used in AI data centers.
Microsoft, Alphabet, Amazon and Meta have also committed significant resources to expanding computing capacity.
But as investment spending rises, shareholders are becoming increasingly focused on whether these companies can produce enough additional revenue and profit to justify the money being deployed.
Reuters reported on October 13 that global equities came under pressure as investors grew concerned about the sustainability of AI-related spending.
Semiconductor shares were particularly vulnerable, reflecting worries about competition and the potential returns from expensive infrastructure projects.
The market’s central concern is not necessarily whether artificial intelligence will transform the economy.
It is whether today’s most highly valued companies will capture enough of that transformation to justify current stock prices.
Even a successful technology revolution does not guarantee equally strong investment returns for every company involved.
Expensive Valuations Could Become Wall Street’s Biggest Weakness
The price investors pay for a company matters.
When stock valuations are elevated, future earnings growth may already be reflected in market prices.
That leaves less room for disappointment.
Vanguard’s research has highlighted the importance of valuations over longer investment horizons, arguing that expensive markets face greater risks of disappointing returns even when underlying companies remain profitable.
This distinction is crucial.
A business can continue growing revenue and earnings while its stock delivers disappointing returns if investors previously paid too much for expected growth.
American technology companies have demonstrated impressive profitability, but many also carry substantial expectations for future expansion.
If earnings growth slows, interest rates remain elevated or global competition intensifies, investors may become less willing to pay premium valuations.
That adjustment could limit future stock market gains without requiring a severe economic recession.
Europe and Other International Markets Could Challenge US Leadership
While American stocks have captured much of the global investment spotlight, international markets are attracting renewed attention.
Vanguard has identified developed markets outside the United States as potentially competitive alternatives over longer investment horizons.
European companies may benefit from industrial investment, defense spending, infrastructure development and changes in global supply chains.
Meanwhile, Asian markets offer exposure to manufacturing, advanced semiconductors, financial services and growing technology ecosystems.
Countries such as Japan, South Korea and Taiwan remain closely connected to the global semiconductor industry.
Other emerging markets could benefit from domestic consumption, industrial expansion and investment diversification.
However, the outlook is far from one-sided.
European economies face their own structural challenges, while Asian and emerging markets remain exposed to trade tensions, currency fluctuations and geopolitical uncertainty.
International stocks are therefore not automatically safer or more profitable than US equities.
The central argument is that investors may need to look beyond the American market to capture a wider range of future opportunities.
Wall Street’s 2026 Rally Shows Why Timing Is Difficult
Despite warnings about expensive valuations, US stocks have remained resilient.
According to the Associated Press, the S&P 500 closed at 7,805.45 on October 13, 2026, after a marginal decline during the session.
The index was still up approximately 14% for the year.
The Nasdaq Composite had gained around 17%, while the Dow Jones Industrial Average was up about 7.5%.
These advances demonstrate why investors can suffer substantial opportunity costs when they abandon markets simply because valuations appear expensive.
Corporate earnings, economic growth and technological innovation can continue supporting stock prices even during periods of heightened uncertainty.
Yet strong recent performance cannot eliminate the possibility of weaker returns over the next decade.
Rising Treasury Yields Add Another Challenge
The long-term outlook for equities is also being influenced by changes in the bond market.
US Treasury yields have climbed sharply in 2026, reflecting inflation concerns, government financing pressures and changing expectations for monetary policy.
Higher yields create competition for stocks because investors can potentially earn more income from relatively lower-risk government securities.
They also raise borrowing costs for households and businesses.
For high-growth technology companies, elevated interest rates can reduce the present value investors assign to profits expected far into the future.
Reuters reported on October 13 that the US 10-year Treasury yield was around 5.22%, even after retreating from recent highs.
Those conditions make stock valuations and earnings expectations increasingly important.
If inflation remains persistent, the Federal Reserve could face difficult decisions about interest rates, economic growth and financial stability.
What This Means for Investors in the Philippines and Asia
The debate over US stock market leadership also matters to investors throughout Asia.
Many internationally diversified portfolios, retirement funds and investment products have substantial exposure to American equities.
Philippine investors purchasing US stocks or international equity funds also face currency considerations.
A stronger peso against the dollar can reduce the peso-denominated value of dollar investments, while a weaker peso can increase those returns when converted back into local currency.
This means international diversification involves more than simply comparing stock market indexes.
Investors must also consider exchange rates, fund expenses, taxation, investment objectives and risk tolerance.
Exposure to markets outside the United States may reduce dependence on a relatively small group of American technology leaders.
However, global diversification cannot eliminate investment losses, and foreign stock markets can decline alongside Wall Street during periods of financial stress.
Five Forces That Could Decide the Next Decade
Several developments may determine whether America retains its position as the world’s leading equity market.
1. Artificial intelligence profitability: Whether AI investment translates into sustained earnings growth rather than simply higher infrastructure spending.
2. Interest rates and inflation: Whether borrowing costs remain elevated or financial conditions become more supportive of equity valuations.
3. Global earnings growth: Whether European, Asian and emerging-market companies can deliver stronger profit expansion.
4. The US dollar: Whether exchange-rate movements continue favoring American assets or begin supporting international investment returns.
5. Market concentration: Whether US index gains broaden beyond technology giants or remain dependent on a relatively small number of companies.
These factors could interact in unpredictable ways, making long-term forecasts uncertain.
The Bigger Picture: America’s Stock Market Era Is Facing a New Test
The most important question is not whether American companies will remain powerful.
Many of them are likely to remain global leaders in technology, finance, healthcare and consumer industries.
The more important question is whether their future growth will be strong enough to justify the prices investors are paying today.
A decade of exceptional stock performance can create the expectation that the same market will continue winning indefinitely.
But financial history shows that investment leadership changes as valuations, economic conditions and corporate profitability evolve.
Wall Street may continue producing substantial wealth, yet investors who assume the next decade will repeat the last could overlook opportunities elsewhere.
The biggest surprise of the next 10 years may not be a collapse in American stocks — but a world in which other markets finally deliver returns that challenge Wall Street’s long-standing dominance.