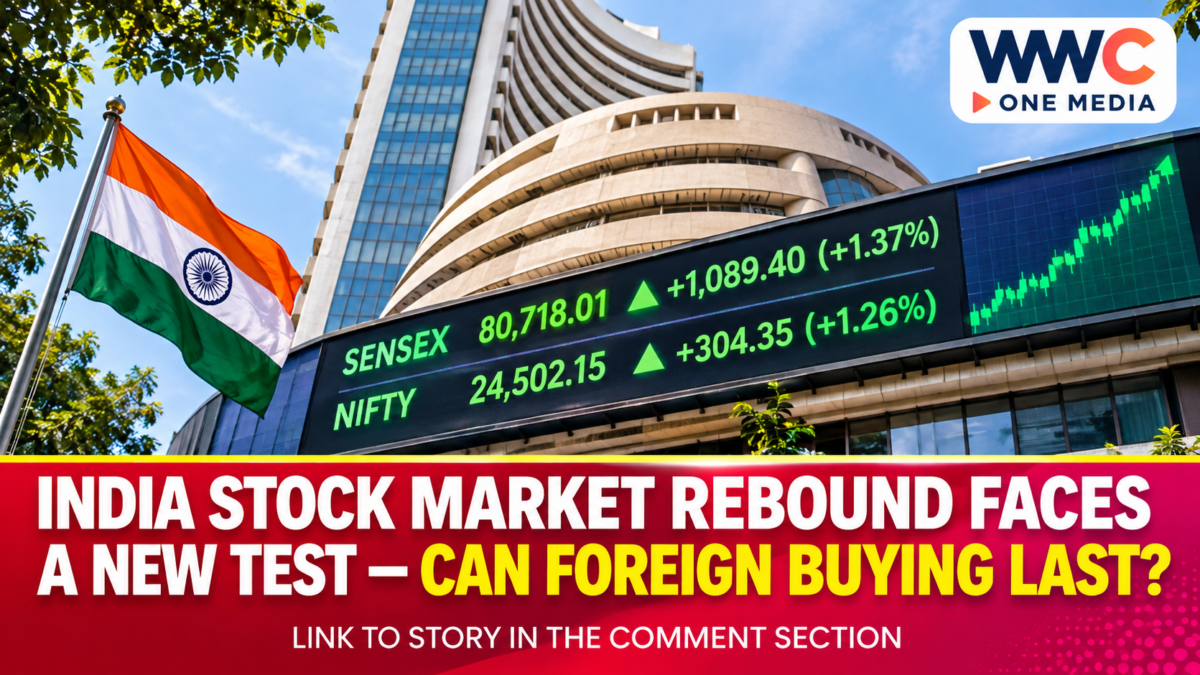
MUMBAI, India — Nov. 15, 2026. Foreign investors returned to Indian equities in November, with official depository records showing ₹8,898.8 crore of net equity investment reported on Nov. 13. Yet India’s benchmark Nifty 50 closed that session at 25,144.30, down 0.61%, illustrating that renewed overseas demand has not eliminated day-to-day market weakness.
The India stock market rebound is therefore better understood as a contest between fresh investment flows and economic risks than as a straight-line rally. The gap between foreign buying and falling benchmark prices is a useful reminder that one group of investors cannot determine every trading session’s outcome.
India Stock Market Rebound: What the Official Numbers Show
The Central Depository Services (India) Limited recorded ₹21,500.33 crore of foreign equity purchases and ₹12,601.53 crore of sales in its report dated Nov. 13. The resulting net investment was ₹8,898.8 crore, including transactions through stock exchanges and the primary market.
That figure needs a careful qualification. The depository says its daily compilation reflects custodial reports received on the reporting date and may cover trades conducted on earlier trading days. It must not be presented as a precise, same-day measure of the stock market’s reaction to a particular news event.
The National Stock Exchange separately showed provisional combined-market foreign institutional net purchases of ₹5,736.55 crore for Nov. 13. These two figures measure differently compiled activity and should not be added together.
India’s government market monitor recorded the Nifty 50 at 25,144.30 and the BSE Sensex at 81,592.45 on Nov. 13. Both benchmarks finished below their previous closes, with the Sensex down 0.39%. The result shows why investors should distinguish a broader recovery from uninterrupted daily gains.
Why Foreign Capital Matters Beyond One Trading Day
Foreign portfolio investors can buy shares in exchange-listed companies or participate in other eligible equity transactions. Their activity can affect demand for stocks, although domestic institutions, companies, retail investors and sellers also shape prices.
A positive net investment number means recorded purchases exceeded sales within the relevant measurement. It does not establish that all foreign investors share one strategy, that the money will remain invested, or that the index must rise.
The official Securities and Exchange Board of India provides separate links to daily and monthly portfolio-investment data. A trend requires consistent measurements across dates.
There is also a difference between money flowing into shares and new money being invested directly in factories or infrastructure. Portfolio purchases generally involve ownership of securities. They do not establish higher employment or output.
The Interest-Rate Constraint Investors Cannot Ignore
India’s monetary authorities have made clear that inflation remains part of the investment calculation. In its October policy decision, the Reserve Bank of India’s monetary policy committee raised the repo rate by 25 basis points to 5.50% and adopted a calibrated-tightening stance.
Higher benchmark rates can influence bank funding, borrowing costs and equity valuations. They may support the attractiveness of some rupee assets while creating pressure for businesses and households reliant on financing. The effect differs by sector and does not translate into a guaranteed stock-market outcome.
WWC previously examined India’s October interest-rate increase and its implications for borrowers. The latest foreign-investment data should be assessed alongside that policy shift, rather than treated as proof that monetary risks have vanished.
Future policy depends on inflation and economic conditions. For equity investors, this makes the mix of financing costs and future earnings at least as relevant as headline fund flows.
Why a Global AI Rotation Is Not Yet a Proven Explanation
One possible interpretation of renewed interest in India is that international portfolios are being rebalanced across markets and industries. But the official investment totals do not disclose the reasons individual funds bought or sold securities.
In particular, the data cannot show that money left artificial-intelligence-related shares abroad and was immediately redeployed into Indian stocks. Establishing that causal chain would require directly attributable investor disclosures or other sufficiently detailed primary evidence.
India’s benchmark index represents companies across multiple industries. A market with a varied sector mix can perform differently from exchanges heavily influenced by a smaller number of technology companies. That is an analytical possibility, not a verified explanation for each day’s trades.
Index gains do not mean every company is improving. Earnings, valuations, debt and business prospects remain company-specific, and an index-level recovery can coexist with losses in individual shares.
Currency and Inflation Remain Part of the Risk Picture
International investors measure returns in their own currencies, so changes in the rupee can affect their results even when an Indian share price rises. Currency swings can also influence import costs and the domestic inflation outlook.
WWC’s earlier coverage of rupee volatility and central-bank currency measures provides context for this separate risk. It is not evidence that exchange-rate movements caused the November share purchases.
Food and energy costs also matter because inflation can influence consumer spending, business margins and the central bank’s policy options. Impacts vary by industry.
The broader economic pressures were explored in WWC’s report on India’s monsoon-linked food inflation and imported-cost risks. These considerations help explain why foreign capital returning to the market is a positive signal for demand, but not a guarantee of lasting returns.
What Happens Next
The next useful test is whether depository data continue to show positive net equity investment over a longer reporting window, and whether the Nifty and Sensex sustain their recovery across several sessions. Another test is whether economic conditions give listed companies room to improve profits despite tighter monetary policy.
For readers in the Philippines, India’s experience also illustrates a broader investment principle: international fund flows may turn quickly, while the economic forces underlying valuations take longer to develop. This is analysis, not a recommendation to buy or sell Indian securities.
The strongest conclusion currently supported by the records is modest but meaningful: foreign equity demand has improved, yet the latest verified trading session still finished lower. The durability of the rebound remains an open question.
Frequently Asked Questions
Are foreign investors buying Indian shares again?
Yes. The official CDSL report dated Nov. 13, 2026 recorded ₹8,898.8 crore in net foreign equity investment. Its reporting date does not mean every transaction occurred on that day.
Did India’s stock market rise on Nov. 13?
No. The government’s market monitor listed the Nifty 50 at 25,144.30, down 0.61%, and the Sensex at 81,592.45, down 0.39%.
Is the India rebound caused by investors leaving AI stocks?
The official market and investment records reviewed here do not establish that direct causal connection. Global portfolio rebalancing is a possible interpretation, not a confirmed explanation.
What is the Reserve Bank of India’s policy rate?
The RBI raised its repo rate to 5.50% in October 2026. That decision is relevant to borrowing costs and financial-market valuations.