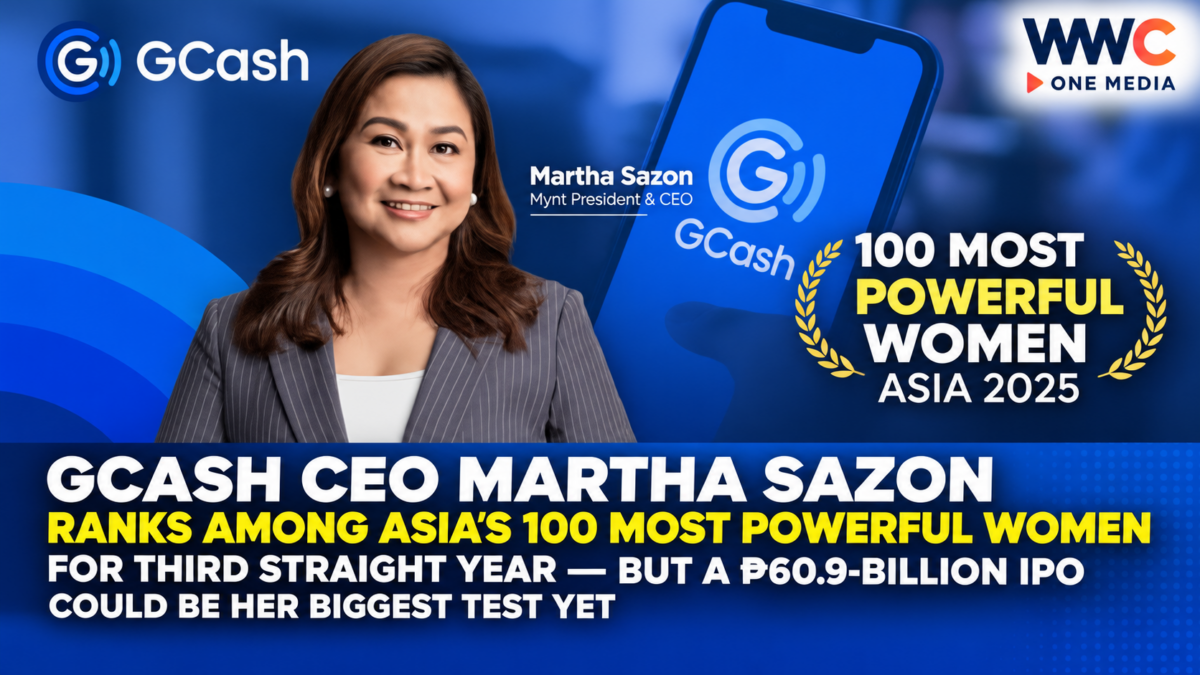
MANILA, Philippines — October 13, 2026 — Martha Sazon, the president and chief executive officer of GCash parent Mynt Inc., has secured another place among Asia’s most influential business leaders, ranking 35th on Fortune’s 2026 Most Powerful Women Asia list as she prepares to guide the Philippine financial technology giant through one of the country’s biggest stock market debuts.
The recognition marks Sazon’s third consecutive appearance on the prestigious annual list, highlighting her leadership in transforming GCash from a mobile payments platform into a broad digital financial services ecosystem.
Under her leadership, Mynt achieved a landmark $5-billion private valuation in 2024, becoming the Philippines’ first fintech company to reach that milestone.
GCash has also expanded its digital lending reach to more than 11 million borrowers, with women accounting for approximately half of them, according to figures released by the company.
Now, Sazon faces another major challenge as Mynt prepares for its scheduled October 20 listing on the Philippine Stock Exchange (PSE), following an initial public offering that could reach ₱60.9 billion if its overallotment option is fully exercised.
But while Sazon’s rise has placed Philippine fintech on Asia’s business map, the bigger question is whether GCash can turn its rapid expansion into lasting profitability, stronger financial inclusion and a successful public-market debut.
Martha Sazon Ranks No. 35 on Fortune’s Most Powerful Women Asia 2026
Fortune’s latest Most Powerful Women Asia ranking recognizes 100 influential female executives from 14 markets across the Asia-Pacific region.
The 2026 list reflects the increasing influence of women leading major businesses in technology, banking, manufacturing, retail and other industries.
Sazon placed 35th, joining an international group of business leaders who are transforming major companies and markets.
At the top of the ranking is DBS Group CEO Tan Su Shan of Singapore, followed by Luxshare Precision Industry’s Grace Wang and Lens Technology founder Zhou Qunfei.
For Sazon, the distinction is particularly significant because it comes as GCash prepares to enter the public stock market.
Her third consecutive inclusion also reflects the growing international visibility of Philippine financial technology companies.
Fortune evaluates business leaders based on factors such as organizational scale, performance, innovation, influence, career trajectory and overall impact.
The latest recognition places Sazon among executives whose influence extends beyond their home markets.
How Martha Sazon Transformed GCash During the Pandemic
Sazon assumed leadership of Mynt during the COVID-19 pandemic, when lockdowns and social distancing accelerated demand for cashless payments.
At the time, digital financial services were becoming essential for households, businesses and individuals seeking alternatives to traditional face-to-face transactions.
GCash was already an established mobile wallet, but the pandemic created opportunities for wider adoption.
Under Sazon’s leadership, the platform expanded beyond basic money transfers and bill payments.
Its financial services ecosystem grew to include savings, lending, insurance, investments and merchant payment services through GCash and its partners.
The expansion helped establish GCash as a major participant in Philippine digital finance.
The platform also became increasingly relevant for small businesses, online sellers and consumers seeking convenient financial transactions.
Rather than focusing exclusively on mobile payments, Sazon positioned GCash as a financial services platform designed to address a wider range of everyday needs.
That strategy became central to the company’s growth and its eventual push toward a public listing.
GCash Reaches $5-Billion Valuation and Prepares for Historic IPO
One of the most important milestones under Sazon’s leadership came in 2024, when Mynt secured investments that valued the company at approximately $5 billion.
The valuation established Mynt as the Philippines’ first so-called double unicorn, a term often used for privately held startups valued at several billion dollars.
The company’s investor base includes major Philippine and international financial institutions.
Globe Telecom, Ant Group, Ayala Corporation and Mitsubishi UFJ Financial Group have been among the investors associated with Mynt’s development.
The company’s financial growth and expanding digital financial services network helped support expectations for a potential public listing.
By 2026, those plans had advanced into a major IPO transaction.
Mynt priced its shares at ₱6.60 each on October 2, 2026, following strong demand from institutional investors.
At the final offer price, the base transaction is valued at approximately ₱53 billion.
If the 1.2-billion-share overallotment option is fully exercised, total gross offering proceeds could rise to around ₱60.9 billion.
That would make the transaction the largest IPO in Philippine history by gross proceeds.
However, the offering’s final size depends on whether the additional shares are sold.
October 20 GCash IPO Becomes Major Test for Sazon
The upcoming stock market debut represents a new stage in Mynt’s corporate development.
As a privately held company, Mynt built its reputation through rapid platform adoption, digital innovation and expanding financial services.
A public listing brings additional expectations from shareholders, analysts and market regulators.
Investors will examine the company’s financial performance, earnings growth, governance and long-term business strategy.
According to Reuters, the transaction has attracted major institutional investment commitments, including participation from global financial institutions.
Mynt’s IPO has also opened opportunities for eligible retail investors to subscribe through GStocks PH, a feature accessible through the GCash application.
The minimum subscription of 100 shares at ₱6.60 per share represented an initial investment of ₱660 during the offering period.
This lower minimum investment requirement helped make IPO participation more accessible to investors with relatively small budgets.
However, owning GCash shares remains different from keeping money in an e-wallet or savings product.
Share prices can rise or fall, and investors may lose part of their investment.
For Sazon, the challenge will be demonstrating that the company can meet public-market expectations while continuing to expand its financial services.
GCash’s AI Lending Platform Reaches More Than 11 Million Borrowers
Beyond valuation milestones, one of GCash’s biggest achievements has been the expansion of access to digital credit.
According to Mynt’s October 6 announcement, GCash has helped extend loans to more than 11 million borrowers through its digital lending ecosystem.
Approximately half of those borrowers are women.
A central part of this strategy is GScore, an artificial intelligence-assisted credit scoring system that evaluates eligible users using digital behavioral data.
Traditional lenders often consider financial documents, formal income records and established credit histories when assessing loan applications.
These requirements can make borrowing difficult for individuals with limited financial records or previous banking relationships.
Alternative credit scoring methods can provide additional information for evaluating borrowers who may not have conventional credit histories.
For GCash, this creates an opportunity to extend financing to people who might otherwise struggle to access formal lending services.
However, loan eligibility remains subject to the company’s lending criteria and applicable regulatory requirements.
The 11-million-borrower figure is a company-reported cumulative reach metric and should not automatically be interpreted as the number of people with currently outstanding loans.
Why Women’s Access to Credit Matters
The fact that women account for approximately half of GCash’s reported borrowers is an important part of the company’s financial inclusion narrative.
Many women entrepreneurs operate small businesses that require working capital, inventory financing or funds for business expansion.
Access to appropriate financial services can help such entrepreneurs manage expenses and respond to commercial opportunities.
Digital lending platforms may also reduce some traditional barriers by allowing eligible customers to apply for loans through mobile devices.
For women managing households or small businesses, convenient digital access can provide greater flexibility.
However, wider borrowing access does not automatically establish that loans are affordable or improve every borrower’s financial well-being.
Interest rates, repayment periods, disclosure requirements and responsible credit assessment remain essential.
The success of inclusive lending should therefore be measured not only by how many people receive loans but also by whether financing supports sustainable economic outcomes.
GCash Has More Than 41 Million Monthly Active Users
Independent investment documentation provides further perspective on GCash’s scale.
According to the International Finance Corporation’s September 2026 project disclosure, GCash recorded approximately 41.5 million monthly active users during the three months ended June 2026.
The figure was equivalent to about 56% of the Philippine adult population, based on the population estimate cited in the disclosure.
Fortune’s 2026 profile of Sazon also states that approximately 90 million Filipinos have used the application.
These figures measure different aspects of platform adoption.
The larger number reflects the company’s broad historical user reach, while the monthly active user figure measures a more specific level of recent engagement.
For investors, that distinction matters because registered or historical users do not necessarily generate transactions or revenue every month.
The challenge for Mynt is converting its extensive customer network into sustainable business activity.
GCash Grows Beyond Payments Into Savings, Credit and Investments
GCash’s development under Sazon has been marked by efforts to build a wider digital financial ecosystem.
The platform now provides access to a range of services, including:
- Digital payments and money transfers.
- Bills payment and merchant transactions.
- Savings products offered through partner financial institutions.
- Consumer and business lending.
- Insurance products.
- Investment services.
- Financial tools for merchants and entrepreneurs.
The expansion allows users to access different financial products through one digital interface.
It also gives Mynt opportunities to generate revenue from a more diversified range of services.
However, the company operates within a regulated financial environment, and some products are provided by partner institutions rather than directly by the GCash wallet operator.
Customers should review the terms, risks and provider details of individual financial products before using them.
Financial Inclusion Remains Central to Sazon’s Strategy
Sazon has consistently emphasized financial inclusion as one of Mynt’s central business priorities.
The company’s stated mission, “Finance for All,” reflects its ambition to make digital financial services accessible to a broader segment of the Philippine population.
Historically, many Filipinos have faced obstacles when opening financial accounts, applying for loans or accessing formal investment services.
These include geographical distance, limited documentation and difficulties meeting conventional banking requirements.
Digital platforms can help reduce some of those obstacles by allowing transactions and applications through mobile devices.
Mynt’s October 6 announcement cited an increase in the share of Filipino adults with formal financial accounts, from 29% before the pandemic to approximately 50% in a more recent measure.
However, this nationwide improvement should not be attributed entirely to GCash.
Banks, other digital wallets, government programs, financial regulation and broader technological adoption have also contributed to expanding financial access.
Martha Sazon Brings Three Decades of Business Experience
Sazon’s rise in fintech follows a career spanning approximately three decades across consumer goods, telecommunications and financial technology.
Before leading Mynt, she spent 12 years at Globe Telecom, where she worked on the expansion of mobile postpaid, small and medium enterprise services and broadband businesses.
Her experience in consumer markets and telecommunications helped shape her approach to digital finance.
She graduated cum laude from the University of the Philippines Diliman with a degree in business administration and accountancy.
She also pursued executive education at IMD, INSEAD and Harvard Business School, according to Mynt.
Her background reflects the combination of consumer business knowledge and technology-sector experience increasingly required in modern financial services.
GCash CEO Brings Philippine Fintech to Global Forums
Beyond her role in the Philippine financial sector, Sazon has represented Mynt and Philippine financial innovation at international business events.
According to Mynt, she has participated in forums including the World Economic Forum in Davos, the International Monetary Fund Executive Board Retreat, the Mobile World Congress in Barcelona and the United Nations Global Compact Leaders Summit in New York.
Her participation reflects the growing international attention given to digital payments and financial technology in emerging markets.
The Philippines has become an important market for digital financial services because of its large consumer population, expanding online commerce and continued demand for accessible financial products.
However, GCash’s international recognition should not be confused with evidence that it has become a dominant digital wallet operator throughout Asia.
Its largest and best-established market remains the Philippines.
GCash Faces Tougher Competition and Rising Expectations
Despite its strong position in Philippine fintech, GCash faces an increasingly competitive environment.
Banks, digital financial platforms and other technology companies are expanding services involving payments, lending, savings and investments.
Competitors are seeking to attract customers through improved mobile applications, lower transaction costs, rewards and new financial products.
At the same time, regulators are placing greater emphasis on consumer protection, cybersecurity, responsible lending and the transparency of financial services.
For Mynt, expanding the number of users is no longer the only challenge.
The company must also demonstrate that its services can generate sustainable earnings while protecting customer information and financial assets.
The transition to public ownership will likely increase scrutiny of these issues.
GCash Reports Continued Profit Growth Ahead of IPO
Mynt’s financial performance shows both the strength and the challenges of its expanding business.
Reuters reported that the company recorded approximately ₱10.82 billion in net income during the first half of 2026.
That represented year-on-year growth of 7.3%.
Revenue reached approximately ₱43.27 billion, an increase of 10.4% from the same period in 2025.
These figures indicate that Mynt remains profitable and continues to expand.
However, the pace of earnings growth also creates questions about how much future expansion investors should expect from the business.
At the IPO price of ₱6.60 per share, Mynt’s implied equity valuation is approximately ₱442 billion.
Such a valuation places significant importance on the company’s ability to maintain growth, improve financial performance and expand profitable services.
For Sazon, the next challenge will be showing investors that GCash can continue generating value after its shares begin trading.
Can GCash Become a Regional Fintech Leader?
Sazon’s recognition on Fortune’s Most Powerful Women Asia list highlights the international visibility of Philippine fintech.
GCash has demonstrated how a mobile financial application can evolve into a major consumer financial services platform.
Its large user base, credit products and investment services offer lessons for other markets seeking to improve access to financial services.
However, expanding beyond the Philippine market would bring additional challenges.
Financial regulations, competitive conditions, payment infrastructure and consumer behavior differ across countries.
For GCash, any larger regional ambitions would require careful planning, strategic partnerships and compliance with local financial regulations.
Its current success in the Philippines provides a foundation for international recognition, but not a guarantee of regional market dominance.
The Bigger Test: From Fintech Success Story to Public Company
Martha Sazon’s third consecutive Fortune recognition is an important professional milestone.
Her leadership has coincided with a dramatic expansion of GCash’s role in the Philippine financial system.
The platform now reaches millions of active users, has extended digital lending access to more than 11 million borrowers and provides a broad range of financial services.
Mynt’s journey from a growing fintech enterprise to a company preparing for a potentially record-breaking IPO reflects the development of the Philippine digital economy.
But becoming publicly traded will introduce a different standard of accountability.
Investors will expect financial transparency, sustainable profit growth, disciplined expansion and strong corporate governance.
Consumers will continue expecting reliable, secure and affordable financial services.
For Sazon, success will depend on meeting both sets of expectations.
GCash CEO Martha Sazon has secured her place among Asia’s most powerful businesswomen for a third straight year — but with a potential ₱60.9-billion IPO approaching, the bigger question is whether she can transform one of the Philippines’ biggest fintech success stories into a lasting financial powerhouse.