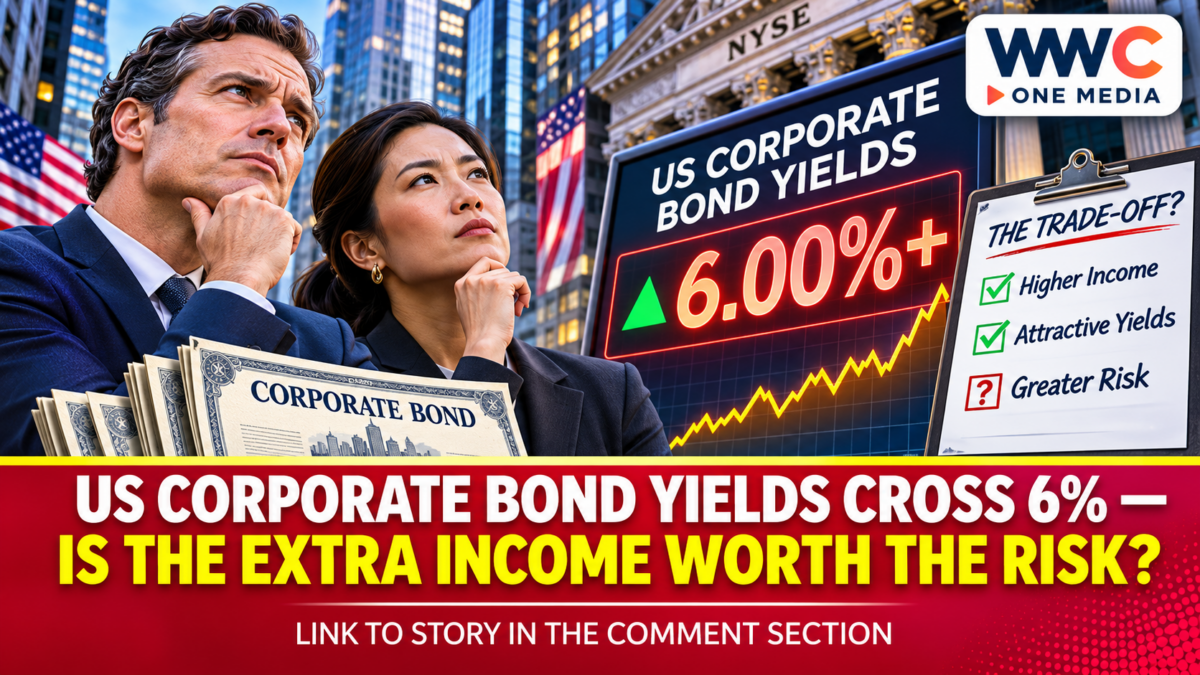
NEW YORK — Nov. 15, 2026. A US corporate-bond benchmark for BBB-rated issuers carried an effective yield of 6.18% on Nov. 12, while a broader below-investment-grade bond index yielded 8.16%, published market-index observations show. Those figures put the US corporate bond yields debate in sharper focus as investors evaluate income against borrowing costs, changing interest rates and the possibility of default.
The central question is not whether a bond offers an eye-catching percentage. It is whether the yield compensates a buyer for the issuer’s financial risks, the bond’s maturity and the possibility of having to sell before repayment.
US corporate bond yields: What the latest figures show
The BBB-rated US corporate bond index stood at 6.18% on Nov. 12, compared with 5.95% on Nov. 9. BBB is the lowest broad investment-grade rating category in this index, so its constituents should not be confused with the bonds of companies rated below investment grade.
A separate BB-rated high-yield index showed 6.80% on Nov. 12. The broad US high-yield index was at 8.16%, while its single-B category yielded 8.36%. The much riskier CCC-and-lower category stood at 17.98%.
These are index-level effective yields, not interest-rate offers to individual retail customers. A buyer’s available price, fees, tax treatment, maturity and actual issuer exposure could all differ from the averages. The dataset’s latest confirmed observation used here is Nov. 12; it is not a Nov. 14 closing quotation.
Why a 6% yield does not mean a 6% guaranteed profit
A bond’s coupon is the contractual payment rate on its face amount. Its effective yield reflects a market valuation, and can change as bond prices move. Buying a security at a premium or discount can change the investor’s realised return.
Market interest rates and fixed-rate bond prices generally move in opposite directions. A holder who must sell before maturity can therefore lose money even if the issuer continues making scheduled interest payments.
Default risk is another consideration. Companies rated below investment grade generally must offer more income to compensate investors for a higher estimated chance of failing to meet debt obligations. No rating or quoted yield eliminates that possibility.
The distinction is relevant to the Philippines as well. WWC’s coverage of a Bank of Commerce peso bond offering explores a different issuer and currency, but illustrates why headline coupons must be examined alongside credit terms and maturity.
What credit spreads reveal beyond the headline rate
Bond yields contain two important components: the general level of market interest rates and the additional compensation demanded for credit and other risks. That second component can be studied through a credit spread over a government-bond benchmark.
On Nov. 12, the BBB corporate index’s option-adjusted spread was 1.11 percentage points, versus 1.16 points on Nov. 5. The broad high-yield spread was 3.20 points on Nov. 12, compared with 3.48 points a week earlier.
A narrowing spread can indicate that the market is requiring less additional compensation for holding corporate credit relative to the benchmark. It does not, on its own, demonstrate that a company has become safer or that corporate bonds rallied during every trading session.
For comparison, the US Treasury’s ten-year constant-maturity yield measured 5.10% on Nov. 12. The Treasury figure and corporate index yields cover different instruments and calculation conventions, so subtracting them mechanically is not a substitute for using the published option-adjusted spread.
Why stock-market turbulence is not proof of a bond-market rush
Technology-share volatility can make fixed-income securities look more attractive, especially to investors who want contractual payment schedules rather than participation in future company earnings. That is a plausible portfolio consideration, not proof that a specific amount of money has moved out of Nvidia or other technology companies and into bonds.
WWC previously covered a US Treasury bond rebound amid technology volatility. Government securities and corporate debt, however, have different credit exposures. A Treasury rally cannot establish an identical rally in riskier company bonds.
Higher yields can result from falling bond prices rather than growing demand. To establish a genuine flow into corporate credit, analysts would need confirmed fund subscriptions, trading-volume data or new-issuance records for the period being discussed.
The verified indices provide a useful snapshot of prices and risk premiums. They do not identify the motivations of individual portfolio managers or show that Nvidia-related events caused the yield changes.
What rising borrowing costs mean for companies
A higher yield in the secondary market can signal that investors demand more compensation to finance corporate borrowers. If those conditions persist, companies issuing or refinancing bonds may face higher interest costs, depending on their credit ratings, maturities and the terms offered at issuance.
Refinancing risk differs from near-term liquidity risk. A company with debt maturing years from now may not immediately pay more simply because benchmark yields move today. Conversely, businesses needing fresh financing can be exposed sooner.
For Philippine readers, international interest-rate moves matter because global credit conditions can influence pricing for dollar-denominated borrowing. But local peso lending costs and domestic bond pricing also reflect Philippine policy rates, currency risk and issuer-specific demand.
WWC’s earlier analysis of US inflation and equity-market volatility provides broader context for why changing interest-rate expectations affect both shares and bonds. The correlation is not automatic, and one market’s daily moves cannot establish another’s cause.
What happens next
The next test is whether corporate yields remain elevated while spreads narrow, or whether investors start demanding more compensation for credit risk. The distinction matters: a yield rise caused mainly by Treasury rates tells a different story from a widening corporate credit premium.
Investors can also watch company refinancing announcements, earnings disclosures and subsequent benchmark observations. None of those indicators can guarantee where bonds or equities will trade next.
For now, the official index data establish a clear gap between investment-grade BBB yields just over 6% and materially higher yields offered by weaker-rated debt. Analysis: That gap is a reminder that attractive income and meaningful risk often arrive together.
Frequently asked questions
Are US corporate bonds yielding more than 6%?
Yes. The BBB US corporate bond index’s effective yield was 6.18% on Nov. 12, 2026. Other ratings and maturities have different yields.
Are 6% corporate bond yields guaranteed returns?
No. Actual returns depend on purchase price, cash flows, holding period and whether the issuer meets its obligations. Selling before maturity may produce a loss.
What is the difference between BBB and BB bonds?
BBB is investment grade in the cited indices, while BB falls below investment grade and generally carries greater credit risk.
Did Nvidia’s troubles cause bond yields to change?
The verified data do not establish that causal connection. Proving such a claim would require further evidence about flows and trading conditions.
What should investors watch next?
Future yield and credit-spread readings, corporate financing disclosures and interest-rate developments can help assess whether the income premium is changing.