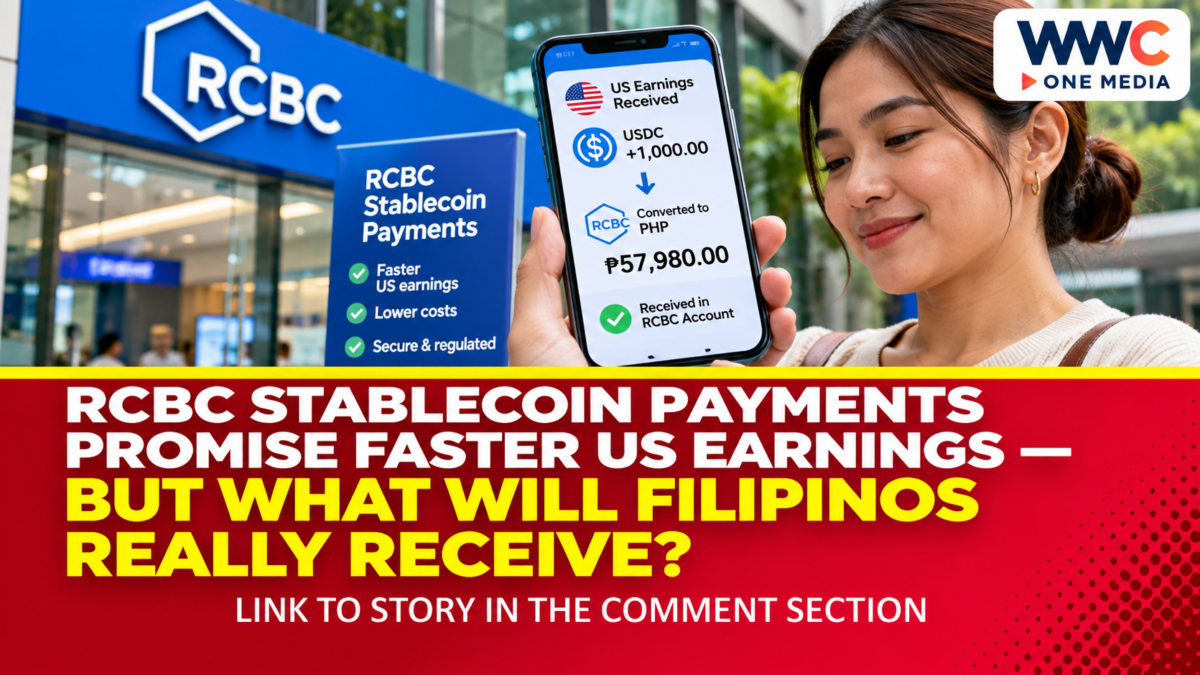
SINGAPORE — Nov. 14, 2026. Rizal Commercial Banking Corporation (RCBC) is offering stablecoin transfers as a funding option for its US Virtual Account in the RCBC Pulz mobile app, giving eligible Filipinos another way to receive US-dollar payments before converting them into pesos. The bank’s published product terms describe receipt within minutes and no incoming stablecoin fee, but they also set identity-verification requirements and a monthly limit on conversion into a linked Philippine account.
The significant question is not whether a payment can move through a blockchain. It is how many pesos the recipient can ultimately use, how reliably the transfer completes and which safeguards apply when the sender or recipient encounters a problem.
RCBC Stablecoin Payments: What the Bank Actually Offers
RCBC’s official US Virtual Account page lists three ways to receive funds: US Automated Clearing House (ACH) transfers, Fedwire transfers and stablecoin transfers. It says customers can hold received value in US dollars and decide when to convert it into Philippine pesos.
The page gives separate instructions for each channel. For stablecoin payments, the sender must use the appropriate network, while the recipient shares the corresponding wallet address or QR code displayed through the banking service. The bank does not describe this as a licence for customers to send arbitrary cryptocurrencies into an ordinary deposit account.
The product information identifies Meridian as RCBC’s US banking partner and describes additional identity checks before a customer can use the account. The exact supported token and blockchain-network list reported elsewhere was not independently confirmed on the bank page examined for this article.
A Few Minutes Is Not the Same as Free Money Movement
RCBC’s customer information lists stablecoin receipts as arriving within minutes. For comparison, it describes ACH deposits as taking one to three business days, while US wire transfers may arrive the same day or the next business day depending on the sending institution’s cut-off time.
Its posted receiving charges are also specific: no RCBC fee for incoming stablecoin transfers, no fee for incoming ACH transfers and US$15 for incoming wires. The bank lists no separate fee for converting US dollars into pesos.
Those prices do not establish that a transfer is entirely free. A sender could face a charge from a wallet provider, payment intermediary or blockchain network. The amount received in pesos also depends on the actual conversion rate displayed when the customer exchanges US dollars.
Analysis: Comparing payment services fairly requires the same starting amount, the same destination currency and the full cost charged at both ends. A transfer advertised as free may deliver fewer pesos if its exchange rate is less favourable; a paid transfer might be competitive under different conditions. No independent comparative test was available for this report.
The US$10,000 Limit Changes the Calculation
The bank sets a US$10,000 monthly aggregate limit for USD-to-PHP conversions transferred into the account holder’s linked RCBC current or savings account. RCBC says that customers who reach that limit must wait until the following month before moving additional converted funds through that facility.
RCBC also states that the US Virtual Account is linked to one nominated Philippine peso account. Existing RCBC customers can apply through Pulz; people new to the bank must first open an RCBC account and complete electronic know-your-customer checks.
Meridian’s separate verification requirements include a valid Philippine identity document, Philippine address, personal information and employment details.
Why Regulated Banks Still Have to Check Digital-Asset Partners
A stablecoin is designed to track the value of a reference asset, commonly the US dollar. That intended price relationship is not itself a guarantee of redemption, uninterrupted service or protection against fraudulent payments.
The Bangko Sentral ng Pilipinas’ Memorandum M-2026-003 requires supervised financial institutions dealing with virtual-asset service providers and relevant offshore counterparties to verify authorisations, assess financial-crime risks and monitor relationships and transactions. The memorandum also sets restrictions concerning unauthorised counterparties and direct access to offshore providers.
For context, WWC’s examination of stablecoins in Latin America explores the tension between faster international transfers and the practical risks of redemption, fraud and converting tokens into spendable money. Its regional statistics do not measure RCBC’s own transaction volumes.
The Philippines Already Has a Large Remittance Market
Official BSP statistics show that cash remittances channelled through Philippine banks totalled US$23.42365 billion from January through August 2026, compared with US$22.909145 billion over the corresponding 2025 period. The figures cover a broad banking-system series rather than the volume handled by RCBC’s new payment option.
WWC has examined GoTyme’s approach to competing for remittance customers. That offering is separate from RCBC’s US Virtual Account, and its promotional terms should not be applied to RCBC customers.
The trend also includes bank-fintech infrastructure partnerships. WWC’s coverage of Tala and Crossmint discusses a different use of stablecoin-related technology; it is not evidence that Tala provides the same RCBC payment service.
What This Could Mean for Filipino Remote Workers
Analysis: A freelancer paid by a US customer may care more about predictable access to earnings than about the technical rail used behind the scenes. A service that lets a recipient hold dollars, check an exchange rate and convert only when needed offers flexibility, subject to its terms and account eligibility.
However, customers should verify the receiving network before sharing a wallet address, confirm the source of a payment request and keep an independent record of invoices and receipts. Wrong-network transfers and fraudulent requests can create difficult recovery problems. No bank announcement should be interpreted as guaranteeing reimbursement for every user mistake.
What Happens Next
The most informative future disclosures will be RCBC’s supported token and network documentation, transparent comparisons of end-to-end costs, and any published adoption or failed-transfer data. A directly accessible dated launch release would also establish which details were introduced in November rather than already available earlier.
For now, the bank’s published instructions confirm stablecoin receipt as an available US Virtual Account feature. They do not establish that all incoming payments are risk-free, universally instantaneous or automatically the cheapest way for every Filipino to get paid.
Frequently Asked Questions
Can RCBC Pulz receive stablecoin payments from the United States?
RCBC’s official US Virtual Account page lists stablecoin transfers among its supported incoming payment methods. Customers must follow the app’s correct network and address instructions and meet eligibility requirements.
Does RCBC charge a fee for incoming stablecoin transfers?
Its product page lists no RCBC incoming stablecoin fee. Senders may still incur third-party charges, and the effective peso amount depends on the conversion rate.
How quickly can stablecoin funds appear?
RCBC advertises receipt within minutes. That is the bank’s stated service expectation, not a guarantee for every transaction.
Is there a limit on converting US dollars to pesos?
Yes. RCBC lists a US$10,000 monthly aggregate limit for conversions transferred into the linked Philippine bank account.