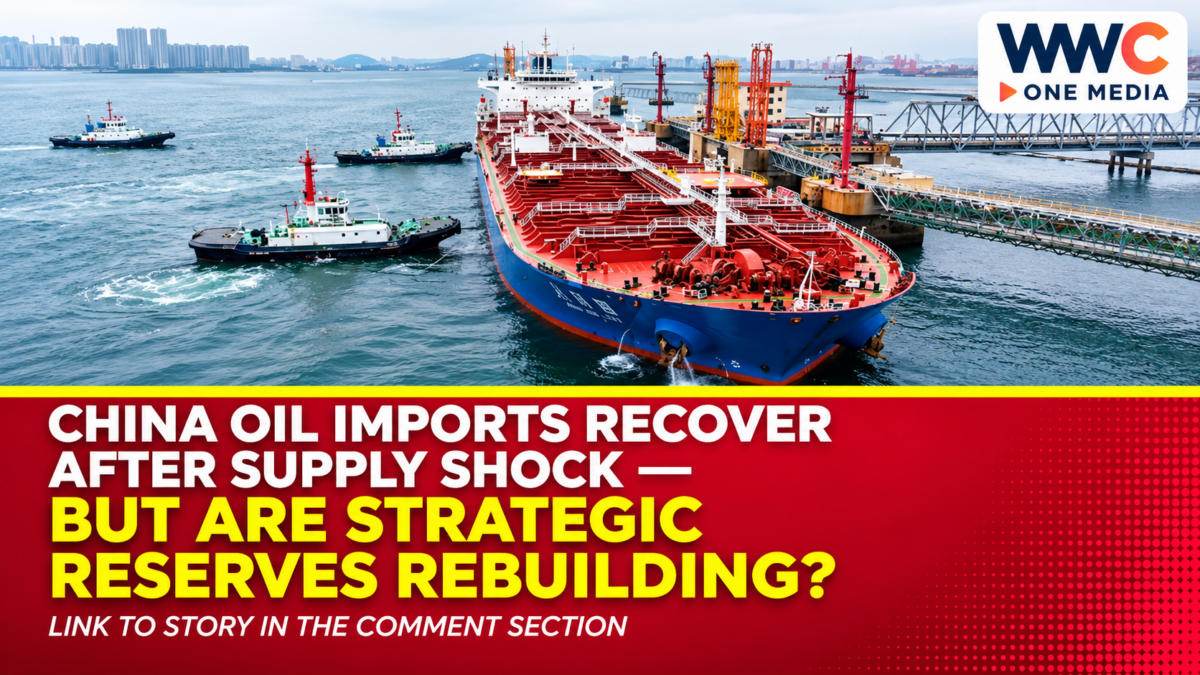
BEIJING — Nov. 19, 2026. China’s crude-oil imports remain below last year’s levels amid questions about whether its emergency energy buffer can recover after a disrupted year. Customs statistics reproduced on a Chinese government website put imports for January through October at approximately 400 million metric tonnes, down 15.1% from the year-earlier period.
The bigger question is how additional arrivals will be used. Refineries, commercial storage companies and strategic stockpile operators all draw on crude supply, and rising purchases do not establish which buyer ultimately receives each barrel. Official refinery data and international inventory reports offer important context without proving a new volume of Chinese state-reserve additions.
China Oil Imports: What Official Data Confirm
The customs figures for the first 10 months describe a market still recovering from disruptions. A decline of 15.1% over that period is consistent with the unusually difficult supply conditions documented this year, but it does not tell readers whether imports rose or fell during each individual month.
October’s more detailed trade tables have been described as showing a month-on-month recovery. However, a complete original customs table establishing the precise October volume and its September comparator was not independently retrieved for this article. The percentage change and daily barrels figure therefore have not been included as independently confirmed facts.
This also means the annual and monthly comparisons must remain separate. Imports may increase from September while still falling short of October 2025. Both statements can be true at once, and neither proves a specific quantity went into storage.
China’s Refineries Show Why Imports and Demand Differ
The National Bureau of Statistics reported that large industrial enterprises processed 58.30 million tonnes of crude in October, down 8.1% year on year. Their processing during January–October amounted to 571.90 million tonnes, a decline of 6.9% from the comparable 2025 period.
Domestic crude production moved differently: October output reached 18.45 million tonnes, up 2.3%, while January–October production totalled 183.04 million tonnes, up 1.1%. The statistics cover industrial enterprises meeting the bureau’s revenue threshold, and their coverage should not be mistaken for every refinery and producer operating in China.
Crude processed is not the same measure as crude imported. A refinery can use domestic production and previously stored oil, while arriving cargoes can remain in tanks for later use. Consequently, comparing one monthly import statistic with one monthly processing statistic cannot generate an audited estimate of strategic-reserve purchases.
Stockpiling Means More Than Filling Government Tanks
A strategic petroleum reserve is designed to help protect an economy against interruption of normal fuel supplies. Commercial stocks, by contrast, support routine refining, distribution and trading operations. Both may increase when buyers anticipate future shortages or find suitable opportunities to procure oil.
The distinction matters for China because the public records reviewed do not specify how much crude went into state-owned emergency storage, how much replenished commercial tanks, or how much stayed in transit. An apparent import surplus also needs adjustments for refinery demand, domestic output, exports and changes in oil afloat.
The International Energy Agency’s November assessment reported that global observed inventories increased by 52 million barrels in October, the first rise since June. Yet it said land-based stocks continued declining and remained at their lowest level since at least 2016. This is a worldwide balance, not a disclosed Chinese strategic-reserve balance.
Middle East Supply Recovery Changes the Calculation
The IEA estimated that global supply rose to 105.4 million barrels per day in October as Gulf exports recovered. It also cautioned that exports from the Gulf, excluding Oman, were still below pre-war levels, while freight rates from the Middle East to Asia remained elevated.
That context explains why purchasing more oil need not signal an immediate revival in Chinese fuel consumption. Buyers can seek to restore buffers after supply interruptions even when refinery activity is weak. The opposite is also possible: greater shipments may be intended primarily for scheduled processing rather than emergency storage.
WWC previously examined maritime risks around the Strait of Hormuz, a route central to Asian crude deliveries. Shipping security, available tankers and freight rates affect how quickly purchased barrels can actually reach storage or refineries.
What This Could Mean for Asian Energy Markets
Analysis: A sustained recovery in Chinese purchasing could compete with other Asian importers for available cargoes, particularly if physical supply or shipping capacity remains constrained. But the effect on prices depends on global output, inventories, demand and the timing of deliveries. It would be misleading to predict a specific increase in oil prices from China’s import figures alone.
The region is already debating stronger emergency reserves. WWC’s analysis of Japan–Philippines petroleum reserve cooperation shows why building resilience involves financing, storage arrangements and access rights—not simply announcing a target quantity.
The corporate dimension also matters. Major producers, refiners and traders have different commercial incentives and operating capacities. WWC has separately assessed China’s leading oil producers and energy security. Their financial performance cannot be used as a direct substitute for government reserve data.
What Happens Next
The next useful evidence will be complete customs figures for November, updated refinery processing data and any authenticated disclosure of strategic or commercial inventories. Changes in Gulf exports and tanker freight costs will also influence how far the recovery can continue.
Until those records are available, the defensible conclusion is measured: China’s imports remain below their year-earlier cumulative level, refinery activity is weak, and the global supply environment has improved from its most severe disruption. Whether Beijing is rebuilding its strategic reserve, and by how much, remains unverified in the primary records reviewed.
Frequently Asked Questions
Did China import more crude oil in October 2026?
Market reports indicate a month-on-month increase, but an original customs table independently establishing the exact October and September quantities was not retrieved. The official cumulative figures confirm that January–October imports were down 15.1% year on year.
Is China adding crude to its strategic petroleum reserves?
The records reviewed do not disclose a confirmed addition to China’s state strategic reserves. Higher imports can also supply refineries and commercial stocks.
How much crude did Chinese refineries process in October?
The National Bureau of Statistics reported 58.30 million tonnes for industrial enterprises above its reporting threshold, down 8.1% year on year.
Could Chinese oil buying increase Philippine fuel prices?
Additional buying may influence regional competition for cargoes, but Philippine retail prices also depend on global supply, refining margins, exchange rates, freight and domestic pricing. No guaranteed price effect follows from these data.