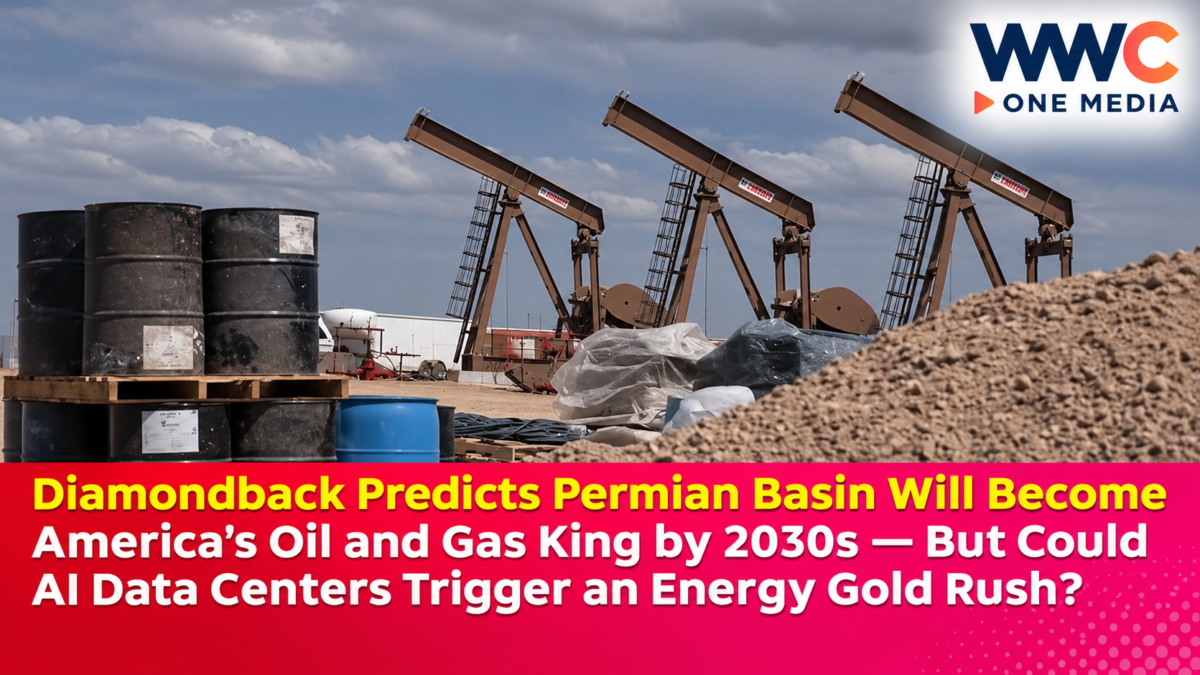
MIDLAND, Texas / MANILA — November 3, 2026. America’s most productive oil region could be preparing for an even bigger transformation as Diamondback Energy predicts that the Permian Basin will emerge as the United States’ largest natural gas-producing region during the 2030s.
The forecast signals a potentially historic shift in the American energy industry, where rising electricity demand from artificial intelligence data centers, expanding liquefied natural gas exports and new pipeline infrastructure are creating opportunities beyond conventional crude oil production.
In its November 2 shareholder letter, Diamondback Energy described a future in which the Permian Basin becomes a leading source of both oil and natural gas.
The projection comes as the Texas-based energy producer reported stronger third-quarter earnings, increased production guidance and stepped up investments intended to move natural gas from West Texas to major consumption markets.
Diamondback reported $5.43 billion in third-quarter revenue and $1.60 billion in net income attributable to the company, supported by higher realized oil prices and greater production.
But behind the impressive financial results lies a much bigger question.
Could the same region that transformed America’s oil industry now become the fuel source for the artificial intelligence revolution — or will pipeline bottlenecks, volatile gas prices and rising energy demand derail the next major American energy boom?
Diamondback Sees the Permian Becoming America’s Natural Gas Powerhouse
Diamondback Energy outlined its long-term outlook in a shareholder letter released alongside its third-quarter earnings.
The company expects the Permian Basin to become the largest natural gas-producing region in the United States during the 2030s, while retaining its dominant position in oil production.
The Permian, stretching across West Texas and southeastern New Mexico, has long been recognized as America’s most important oil-producing region.
But natural gas is increasingly becoming a significant part of its production profile.
Much of that gas is produced alongside crude oil, making it known as associated gas.
As operators develop deeper formations and different geological zones, the proportion of natural gas recovered relative to oil can increase.
Diamondback believes these changes could allow the Permian to expand natural gas production substantially without abandoning its established oil business.
The company also identified previously underdeveloped gas-rich formations as potential sources of additional supply.
However, its forecast depends on future drilling results, infrastructure expansion, commodity prices and customer demand.
The prediction is not a confirmed ranking for the 2030s.
Three Major Forces Could Transform the Permian Basin
Diamondback identified three major opportunities shaping its strategy for the coming decade.
The first involves extracting more oil from existing resources through improved technology and operational practices.
The second is expanding natural gas production and connecting that supply to LNG export facilities and electricity markets.
The third is the development of artificial intelligence data centers and supporting power infrastructure in West Texas.
These opportunities are closely connected.
AI data centers require large amounts of electricity to operate their servers, networking equipment and cooling systems.
Natural gas-fired power plants can provide dispatchable electricity, making them one possible source of energy for facilities requiring continuous operations.
Meanwhile, expanding LNG export capacity can provide another market for natural gas produced in the Permian.
For Diamondback, the opportunity is to improve the value of resources it already controls while developing additional sources of revenue.
That strategy could reshape the economics of a region historically associated primarily with oil.
Diamondback’s Revenue Climbs to $5.43 Billion
The company’s latest financial results provide important context for its expansion plans.
For the third quarter ended September 30, Diamondback reported revenue of approximately $5.43 billion, compared with $3.92 billion a year earlier.
Net income attributable to Diamondback increased from approximately $1.02 billion to $1.60 billion.
Diluted earnings per share rose to $5.69 from $3.51.
Adjusted earnings reached $5.86 per share, exceeding market expectations cited by Reuters.
The company produced an average of approximately 525,000 barrels of crude oil daily.
Combined oil, natural gas and natural gas liquids production reached approximately 1.034 million barrels of oil equivalent per day.
Higher realized oil prices supported profitability.
Diamondback received an average unhedged oil price of $87.30 per barrel during the quarter, compared with $64.60 a year earlier.
These results highlight the importance of its existing oil operations.
Although Diamondback is optimistic about natural gas, crude oil remains central to its earnings.
Its natural gas strategy is therefore an expansion of its business model rather than evidence that it is abandoning oil production.
Diamondback Raises Production and Spending Forecasts
Following its stronger quarterly performance, Diamondback increased its full-year production guidance for the third consecutive quarter.
The company now expects average 2026 oil production of approximately 524,000 barrels per day.
Total production is projected at around 1.015 million barrels of oil equivalent daily.
Diamondback also increased its full-year capital spending forecast to between $3.95 billion and $4 billion.
The higher spending outlook reflects ongoing investment in drilling, production and supporting infrastructure.
For the fourth quarter, Diamondback expects oil output between 518,000 and 528,000 barrels per day.
However, higher production does not automatically guarantee higher profits.
Future earnings will depend on oil and gas prices, production costs, transportation expenses and capital efficiency.
The company must also manage uncertainty surrounding global energy markets.
The Permian’s Biggest Problem: Too Much Gas, Not Enough Pipelines
One of the biggest obstacles facing the Permian Basin is the limited infrastructure available to transport natural gas.
Historically, oil producers have recovered significant volumes of associated gas even when local demand and pipeline capacity were insufficient.
That mismatch has periodically pushed prices at the Waha trading hub in West Texas below zero.
Negative gas prices mean producers may effectively have to pay to move unwanted gas into the market.
During the second quarter of 2026, Diamondback reported average unhedged natural gas realizations of negative $2.15 per thousand cubic feet.
The company explained that inadequate transportation capacity and maintenance restrictions contributed to weak pricing.
However, conditions improved as additional pipeline capacity became available.
Third-quarter unhedged gas realizations recovered to approximately $1.12 per thousand cubic feet.
The improvement illustrates why transportation infrastructure is essential to Diamondback’s long-term strategy.
Producing more gas is only commercially useful if it can be delivered to customers at economically attractive prices.
Diamondback Invests in New Natural Gas Pipeline Infrastructure
Diamondback is taking steps to improve its access to major gas markets.
In its latest earnings announcement, the company confirmed the acquisition of a 7.5% equity interest in the Solitude Pipeline System.
The system is designed to connect Permian natural gas production with the Katy energy hub in Texas.
Katy provides access to major gas markets and transportation infrastructure serving the Gulf Coast.
Reuters also reported in August that a joint venture involving WhiteWater, Devon Energy, MPLX, Diamondback and Western Midstream Partners had approved construction of additional natural gas pipelines.
These developments could help reduce the Permian’s long-standing transportation constraints.
Expanded pipeline capacity may allow producers to access customers outside West Texas and receive prices more closely aligned with larger regional markets.
But pipeline construction requires substantial investment, regulatory approvals and long-term shipping commitments.
Delays or cost overruns could affect project economics.
For Diamondback, improving gas transportation is essential to turning its long-term production forecast into a profitable business opportunity.
AI Data Centers Could Become the Permian’s Next Major Customers
The rapid growth of artificial intelligence is creating new electricity requirements across the United States.
Large data centers use substantial computing resources to train and operate AI models.
These facilities require electricity not only for processors and servers but also for cooling and network infrastructure.
Diamondback believes West Texas offers an attractive location for new data centers because of its abundant energy resources and available land.
The company has indicated that it is exploring opportunities to support large-scale power projects associated with data-center development.
Its strategy could involve using locally produced natural gas to supply electricity to nearby facilities.
This approach may reduce some transportation requirements and connect natural gas production more directly with regional demand.
However, prospective data-center projects should not be described as completed investments unless contracts, permits and financing have been confirmed.
The commercial opportunities will depend on whether technology companies commit to long-term electricity purchases and whether infrastructure can be developed reliably.
America’s LNG Export Boom Could Drive More Permian Gas Production
Another major source of demand is the expanding US liquefied natural gas industry.
LNG allows natural gas to be transported internationally by cooling it into liquid form.
US export facilities along the Gulf Coast receive natural gas through pipelines, process it and load it onto specialized vessels for delivery overseas.
Demand from Europe and Asia has encouraged investment in American LNG infrastructure.
According to Reuters, US natural gas production is expected to reach record levels in 2026 and 2027 as LNG exports and electricity demand increase.
The US Energy Information Administration has identified the Permian and Haynesville regions as major contributors to expected production growth.
In its September 2026 outlook, the agency projected that Permian natural gas production would rise by approximately 1.7 billion cubic feet per day in 2026 and 2.2 billion cubic feet per day in 2027.
These forecasts support Diamondback’s view that natural gas production in the region has considerable room to expand.
But production growth and profitable exports are not the same.
Liquefaction costs, global gas prices, shipping expenses and international competition will influence the ultimate economic benefits.
Bangladesh’s LNG Demand Shows Why American Gas Matters to Asia
Asia’s growing interest in American LNG provides another reason for Diamondback’s optimism.
Several countries depend on imported natural gas to support electricity generation and industrial activity.
Bangladesh, for example, has been seeking additional US LNG supplies as disruptions in the Middle East create uncertainty surrounding international energy shipments.
WWC ONE MEDIA previously reported on the development in Bangladesh Seeks More US LNG as Qatar Supply Crisis Deepens — But Will American Gas Rescue Its Energy-Hungry Economy?.
The report examined Bangladesh’s efforts to secure additional gas contracts and reduce dependence on vulnerable supply routes.
Bangladesh’s experience demonstrates the importance of diversified LNG supply.
American producers could benefit if international customers expand their long-term purchasing commitments.
However, a US natural gas producer does not necessarily sell directly to every foreign LNG buyer.
Gas can pass through multiple intermediaries, pipeline systems and liquefaction operators before reaching an overseas market.
Diamondback’s opportunity depends on how effectively it connects its production to that broader supply chain.
Singapore’s Gas Supply Concerns Reveal Another Opportunity
Southeast Asian energy markets are also experiencing supply challenges.
In October, Indonesia reduced natural gas exports to Singapore to prioritize domestic energy requirements.
Although Singapore’s government said the short-term impact was manageable, the development highlighted the importance of maintaining alternative supply sources.
WWC ONE MEDIA covered the issue in Indonesia Slashes Natural Gas Exports to Singapore as Electricity Price Fears Rise — But Could a Bigger Energy Crisis Be Looming?.
Singapore has developed LNG import infrastructure alongside its pipeline-gas arrangements.
That diversification can provide flexibility when individual suppliers face disruptions.
For the United States, demand from international energy-importing markets could support additional LNG exports.
For the Permian Basin, expanding pipeline capacity to Gulf Coast facilities may improve access to those markets.
However, there is no verified agreement establishing that Diamondback will directly supply the gas replacing Indonesia’s reduced deliveries to Singapore.
The relationship is one of broader market opportunity rather than a confirmed transaction.
Natural Gas Prices Remain a Major Risk
Even as Diamondback expects stronger long-term demand, short-term gas prices remain volatile.
American natural gas futures have recently faced downward pressure from forecasts of relatively mild winter weather.
WWC ONE MEDIA examined the market’s bearish positioning in Hedge Funds Bet Against US Natural Gas With Record 625,150 Short Contracts — But Could One Winter Cold Snap Trigger a Massive Price Surge?.
The report highlighted how expectations of warmer temperatures and reduced heating demand were influencing futures markets.
This creates a challenge for gas producers.
Growing long-term demand from LNG exports and AI data centers does not eliminate seasonal price fluctuations.
Mild winters can reduce heating demand, while unexpectedly cold weather can increase consumption.
High production and adequate storage can limit price increases.
Pipeline constraints can also create substantial price differences between regions.
Diamondback has used hedging arrangements to manage some of these risks.
Nevertheless, the success of its gas strategy will depend on consistently obtaining prices that justify production and infrastructure costs.
The Philippines Could Become a Bigger Buyer of American LNG
The Permian Basin’s potential expansion also carries implications for Philippine energy security.
The country is examining new LNG infrastructure to supplement existing natural gas resources and support electricity demand.
WWC ONE MEDIA recently reported on a proposed investment involving the Aurora Pacific Economic Zone and Freeport Authority.
Read the related story: APECO Signs ₱9.45-Billion LNG Power Agreement With US Partners as Aurora Eyes 2,000 MW — But Can the Project Deliver on Its Ambitions?.
The proposed project involves potential LNG infrastructure and power development in Aurora province.
However, the announced agreement does not mean the facilities are already operational.
Feasibility studies, permits, financing and commercial negotiations remain important requirements.
If Philippine LNG demand expands, additional American export capacity could provide more supply options.
But the cost of importing LNG will depend on international prices, shipping costs, contractual terms and the peso-dollar exchange rate.
The possibility of increased US gas supplies does not guarantee lower electricity prices in the Philippines.
Natural Gas Expansion Faces Environmental and Infrastructure Challenges
Diamondback’s long-term strategy also raises important environmental questions.
Natural gas combustion generally emits less carbon dioxide per unit of electricity than coal under comparable operating conditions.
However, natural gas remains a fossil fuel.
Methane leakage during production, processing and transportation can significantly affect its climate impact.
Large-scale expansion also requires infrastructure such as wells, pipelines, processing facilities and power plants.
These developments can create environmental and community concerns involving land use, water management, air emissions and industrial activity.
For data-center projects, electricity supply must also be coordinated with grid capacity and long-term demand.
The profitability of new investments will depend on reliable infrastructure and manageable operating expenses.
Diamondback’s opportunity is substantial, but it is not free from financial, environmental or regulatory risks.
What Investors Should Watch Next
Investors evaluating Diamondback’s natural gas strategy should monitor the progress of new pipeline projects.
Additional transportation capacity could improve the prices the company receives for its gas.
Another important factor is the pace of natural gas production growth relative to oil output.
The company’s long-term projection assumes that gas volumes will continue expanding as operators develop additional formations.
LNG export capacity and customer demand will also influence future opportunities.
At the same time, investors will be watching whether AI data-center developers commit to large power projects in West Texas.
Finally, Diamondback’s ability to maintain disciplined capital spending and generate free cash flow will remain critical.
The company reported approximately $2.15 billion in third-quarter free cash flow under its non-GAAP definition.
That provides financial flexibility, but future returns remain dependent on commodity prices and operating performance.
The Bigger Question: Could the Permian Become America’s Next Energy Empire?
Diamondback Energy’s latest outlook highlights a potentially major transformation in the American energy industry.
The Permian Basin has already reshaped the United States’ position in global oil markets.
Now, the region could become an increasingly important natural gas supplier as production rises and new pipelines connect West Texas to major energy consumers.
Artificial intelligence data centers, LNG export terminals and growing electricity demand are creating new opportunities.
Diamondback’s stronger quarterly earnings and investments in transportation infrastructure demonstrate its commitment to that future.
But significant uncertainties remain.
Natural gas prices can be volatile.
Pipeline projects may face delays.
AI electricity demand may not develop exactly as expected.
And the economics of expanded gas production will depend on the prices producers ultimately receive.
Diamondback’s forecast of Permian gas dominance in the 2030s is ambitious, but it remains a prediction rather than an established outcome.
As Diamondback positions the Permian Basin to dominate both America’s oil and natural gas markets, could AI data centers and global LNG demand unleash a new energy gold rush — or will pipeline constraints, volatile prices and infrastructure costs prevent the region from reaching its full potential?