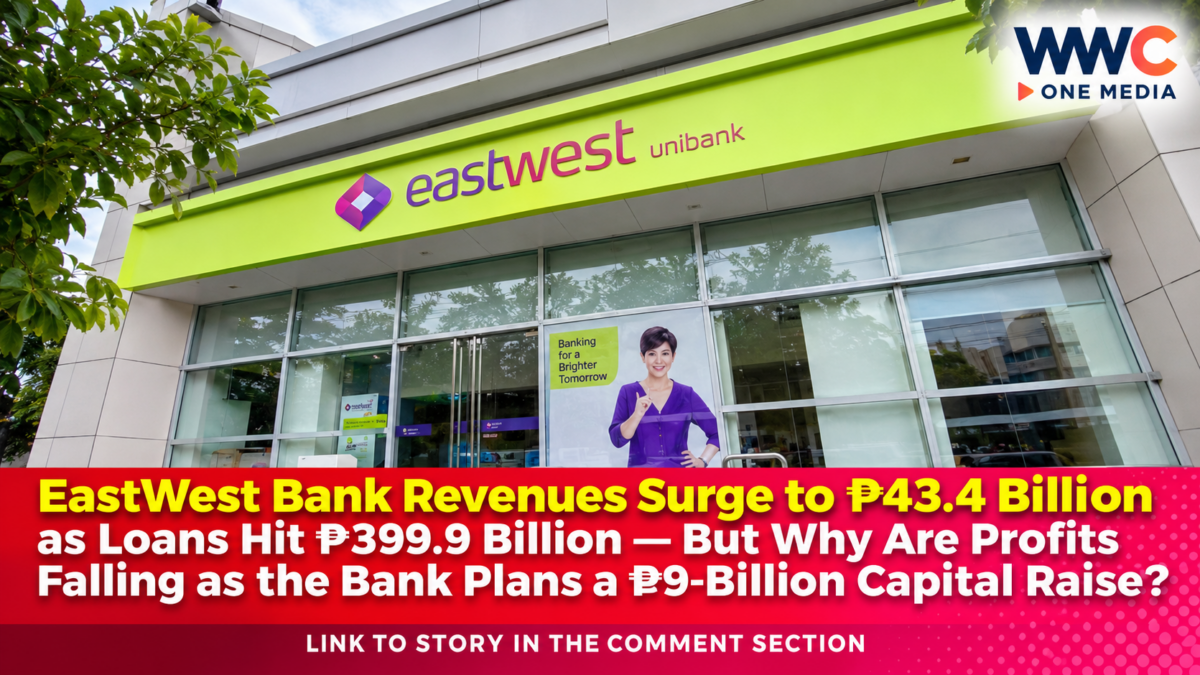
MANILA, Philippines — November 3, 2026. East West Banking Corporation (EastWest), the Gotianun family’s banking arm under the Filinvest Group, is confronting a major profitability challenge after its earnings fell sharply despite stronger revenues, growing deposits, and an expanding loan portfolio.
The bank reported ₱5 billion in net income for the first nine months of 2026, down approximately 24.2% from ₱6.6 billion during the same period in 2025.
What makes the decline particularly striking is that EastWest’s underlying business continued growing.
Net revenues climbed approximately 16% to ₱43.4 billion, net interest income increased 22% to ₱36.2 billion, and operating efficiency improved significantly.
But behind those gains was a growing financial burden: ₱15.9 billion in provisions for expected credit losses, reflecting heightened lending risks and uncertainty surrounding borrowers’ repayment capacity.
The result presents a critical question for the Philippine banking industry: Can banks continue expanding their loan portfolios without sacrificing profitability when credit risks increase?
For EastWest, the answer may determine whether its planned ₱9-billion stock rights offering becomes a foundation for renewed growth or whether additional pressure on lending quality continues weighing on earnings.
EastWest’s ₱5-Billion Profit Reveals the Cost of Growing Credit Risks
EastWest’s financial performance during January to September 2026 presents two contrasting stories.
On the operational side, the bank continued generating stronger revenues from lending, fees, and other banking services.
On the profitability side, higher credit-loss provisions significantly reduced its earnings.
According to reports from InsiderPH, The Philippine Star, and Daily Tribune, EastWest’s net income declined from approximately ₱6.6 billion to ₱5 billion.
The decrease occurred even as the lender continued expanding its income-generating assets.
The main pressure came from expected credit-loss provisions, which reached ₱15.9 billion.
These provisions reflect estimated potential losses on loans and other credit exposures, rather than necessarily representing loans already written off.
For banks, recognizing expected credit losses is an important part of financial reporting and risk management.
But a sharp increase can signal that an institution expects greater difficulty recovering some outstanding loans.
The real challenge for EastWest is whether its stronger operating business can produce a sustainable earnings recovery once credit costs stabilize.
WWC ONE MEDIA previously examined this same financial challenge in its report, EastWest Bank Profit Plunges 24% Despite ₱43.4-Billion Revenue Surge — But Could ₱15.9 Billion in Loan-Loss Provisions Signal Bigger Trouble?.
Revenues Surge 16% to ₱43.4 Billion as Lending Business Expands
Despite the earnings decline, EastWest’s core banking operations demonstrated considerable strength.
Its net revenues increased from approximately ₱37.3 billion in the first nine months of 2025 to ₱43.4 billion in the comparable 2026 period.
That represents growth of around 16.4%.
Net interest income, the difference between interest earned on qualifying financial assets and interest expenses on funding, increased 22% to ₱36.2 billion.
The increase was supported by the bank’s larger interest-earning asset base.
Meanwhile, service charges, fees, and commissions grew 10% to ₱5.8 billion.
These developments suggest that EastWest successfully expanded its revenue-generating activities.
However, stronger revenues do not automatically translate into higher profits.
For financial institutions, the ultimate profitability of lending depends on whether borrowers repay their obligations and whether credit income sufficiently compensates for the risks being taken.
This is particularly important for lenders with significant exposure to consumer financing.
Loan-Loss Provisions Reach ₱15.9 Billion — Why It Matters
The most significant warning sign in EastWest’s latest financial results is the size of its expected credit-loss provisions.
The bank recognized ₱15.9 billion in provisions during the nine-month period, compared with approximately ₱9.9 billion a year earlier, according to WWC ONE MEDIA’s earlier coverage of the bank’s results.
That represents an increase of roughly 61%.
The increase helps explain why EastWest’s operating performance improved while reported net income declined.
Credit-loss provisions are accounting charges recognizing expected losses based on factors such as borrower performance, credit exposure, and forward-looking economic assumptions.
They can rise when lenders identify higher risks of borrowers failing to repay their loans.
But higher provisions do not automatically mean the bank has already lost the entire amount in cash.
Nor do they prove that a specific economic event or borrower category caused all the deterioration.
A detailed examination of the bank’s credit portfolio would be needed to establish which segments contributed most to the increase.
The challenge facing EastWest is therefore not simply generating more lending income.
It is maintaining credit quality while pursuing growth.
EastWest’s Loan Portfolio Nears ₱400 Billion
EastWest’s balance sheet continued expanding during the reporting period.
Its total assets rose 14% to ₱631.8 billion.
The bank’s loan portfolio increased 11% to ₱399.9 billion.
Deposits grew 12% to ₱466.4 billion.
These figures indicate that the bank maintained customer activity and continued attracting funds despite a more challenging operating environment.
Current account and savings account deposits accounted for approximately 77% of its deposit base.
A substantial proportion of these deposits can support a bank’s funding strategy, although their financial value depends on pricing, stability, and other factors.
For EastWest, expanding lending activity provides additional opportunities to earn interest income.
But it also increases the amount of credit exposure requiring continuous monitoring.
If the repayment performance of existing or newly issued loans deteriorates, the financial benefits of rapid lending expansion can weaken.
The bank must therefore balance growth ambitions against the long-term quality of its loan portfolio.
Operating Efficiency Improves Despite Profit Decline
One positive development was EastWest’s improvement in operating efficiency.
Its operating expenses increased approximately 10% to ₱21 billion.
That was slower than the growth in net revenues.
As a result, its cost-to-income ratio improved from 51.4% to 48.4%.
A lower cost-to-income ratio generally indicates that a bank is using a smaller share of operating revenue to cover operating expenses.
EastWest’s pre-provision operating profit increased 24% to ₱22.4 billion.
This metric measures earnings before recognizing the specified credit-loss provisions.
It suggests that EastWest’s underlying banking operations generated stronger results before accounting for credit risk.
But the contrast between stronger operating profits and lower net income reveals the importance of managing potential loan losses.
EastWest is operating more efficiently, yet credit costs are preventing those gains from translating fully into bottom-line growth.
A Bigger Banking Industry Pattern Is Emerging
EastWest is not the only Philippine lender experiencing a disconnect between business expansion and profitability.
BDO Unibank, the country’s largest bank by assets, reported ₱63.6 billion in net income for the first nine months of 2026.
Its loan portfolio expanded 16% to ₱4.1 trillion, yet net income increased by less than 1%.
WWC ONE MEDIA reported these developments in BDO Profit Hits ₱63.6 Billion as Loans Surge to ₱4.1 Trillion — But Why Is Earnings Growth Barely Moving?.
BDO’s experience does not mean its credit conditions are identical to EastWest’s.
The banks differ substantially in size, loan composition, customer base, and risk exposure.
However, their results illustrate why revenue growth and loan expansion should not be assessed in isolation.
Another major lender, Bank of the Philippine Islands, reported ₱48.9 billion in net income during the same nine-month period, according to WWC ONE MEDIA’s coverage of its anniversary bond offering.
BPI’s earnings were approximately 3% lower year on year despite stronger revenue and lending activity.
WWC ONE MEDIA examined the financial results alongside the bank’s fundraising plans in BPI Marks 175 Years With ₱5-Billion Sustainability Bond Offer — But Could Another ₱50-Billion Investor Rush Be Coming?.
These results highlight an important issue: Higher lending income does not necessarily guarantee higher profitability when credit losses and other expenses are rising.
EastWest Priority Wealth Management Assets Rise 35%
Beyond traditional banking, EastWest reported significant expansion in its wealth management business.
Assets under management at EastWest Priority increased 35% to ₱145 billion.
This reflects growth in the value of client assets managed or serviced through the bank’s wealth management operations.
The expansion may help diversify its business by creating opportunities for investment-related fees, financial advisory relationships, and other services.
However, assets under management should not be mistaken for bank revenue or net profit.
The ₱145-billion figure does not represent money earned by the bank during the reporting period.
Its contribution to future profitability will depend on fee structures, customer activity, operating costs, and investment-service demand.
For EastWest, stronger wealth management operations could become an increasingly useful complement to traditional lending activities.
Security Bank’s Restructuring Shows How Philippine Lenders Are Responding
Across the banking industry, companies are adjusting their business strategies to address changing economic conditions.
Security Bank recently confirmed targeted workforce changes as part of efforts to align its operations with business priorities.
The lender reported approximately ₱6.1 billion in first-half 2026 net income, representing 4% growth year on year.
Its first-half loan growth was comparatively subdued.
WWC ONE MEDIA covered the development in Security Bank Confirms Job Cuts as New CEO Victor Lee Restructures Operations — But Is a Bigger Banking Shake-Up Coming?.
Security Bank’s restructuring is a separate development and should not be interpreted as evidence that EastWest plans similar workforce reductions.
Nevertheless, it illustrates how Philippine banks are reassessing efficiency, business priorities, and competitive positioning.
For EastWest, controlling ordinary operating expenses has already produced measurable improvements.
Managing credit quality now appears to be a more pressing challenge.
EastWest Plans ₱9-Billion Stock Rights Offering
EastWest is also pursuing a capital-raising initiative intended to strengthen its financial position.
The bank plans to raise up to ₱9 billion through a stock rights offering.
The initiative is intended to support its capital base and provide additional resources for future expansion.
A stock rights offering typically allows eligible shareholders to subscribe to newly issued shares according to the terms established by the company.
If successfully completed, the offering would provide additional equity capital.
However, the proposed ₱9 billion should not be described as funds already raised.
Completion depends on the applicable approvals, final terms, and execution of the transaction.
The potential capital increase could support EastWest’s lending and other business activities.
But stronger capitalization alone does not resolve underlying credit-quality challenges.
Investors will still need to evaluate the bank’s loan performance, profitability, and future financial results.
Capital Ratios Remain Above Regulatory Minimums
EastWest reported a capital adequacy ratio of 12.2%.
Its Common Equity Tier 1 ratio stood at 11.4%.
Both remained above applicable regulatory minimums, according to the bank.
These capital measures help assess an institution’s ability to absorb potential financial losses relative to its risk-weighted assets.
However, EastWest’s ratios were lower than the comparable year-earlier figures reported by The Philippine Star.
The capital adequacy ratio declined from 13.6%, while the Common Equity Tier 1 ratio fell from 12.7%.
That makes the proposed capital raise especially relevant to the bank’s future financial strategy.
It is important to distinguish declining profitability from insolvency.
The reviewed financial reports do not establish that EastWest is insolvent, facing an imminent collapse, or unable to meet its obligations.
The central concern is whether the bank can restore earnings momentum while maintaining sufficient capital and managing credit risks effectively.
What EastWest Investors Should Watch Next
Several financial indicators will be important in assessing EastWest’s recovery prospects.
The first is the direction of expected credit-loss provisions.
If provisions decline while the bank maintains its operating income, future profitability could improve.
Conversely, continued increases in expected credit losses could place additional pressure on earnings.
The second is the performance of the loan portfolio.
EastWest reported a non-performing loan coverage ratio of approximately 90%.
This figure indicates the relationship between specified credit-loss reserves and non-performing loans under the bank’s reporting approach.
It does not mean that 90% of loans are performing, nor does it guarantee complete protection against future defaults.
The third consideration is capital strength.
Investors will be watching whether the proposed ₱9-billion rights offering proceeds and how any fresh capital is deployed.
Finally, management’s ability to sustain operating efficiency while maintaining appropriate lending standards will be essential.
CEO Jerry Ngo Emphasizes Financial Discipline
EastWest chief executive officer Jerry G. Ngo acknowledged the importance of risk management while emphasizing the strength of the bank’s underlying operations.
In the company’s earnings announcement, Ngo pointed to revenue growth and improved efficiency as positive developments.
He also stressed the importance of maintaining discipline in the bank’s approach to risk and long-term expansion.
The message suggests that EastWest management recognizes the need to balance business growth with financial resilience.
The challenge will be turning that approach into measurable improvements in asset quality and profitability.
Investors and other stakeholders will need to assess management’s progress through subsequent financial disclosures rather than relying on the latest revenue figures alone.
The Bottom Line: Is EastWest’s Profit Decline a Warning or an Opportunity?
EastWest’s first nine months of 2026 reveal a bank with stronger underlying operations but weaker final earnings.
Revenue grew approximately 16% to ₱43.4 billion.
Net interest income increased 22%.
Operating efficiency improved.
Loans reached nearly ₱400 billion, while deposits and wealth management assets continued expanding.
Yet net income dropped approximately 24% to ₱5 billion, weighed down by ₱15.9 billion in expected credit-loss provisions.
The company remains profitable and reports capital ratios above regulatory minimums.
Its proposed ₱9-billion stock rights offering could provide additional financial flexibility.
But the next stage of EastWest’s growth will likely depend on something more fundamental than increasing lending volumes: controlling credit costs while preserving the strength of its banking franchise.
As EastWest continues expanding its loans and revenues, can it bring credit risks under control and rebuild profitability — or will its mounting loan-loss provisions become the biggest obstacle to the bank’s next chapter?