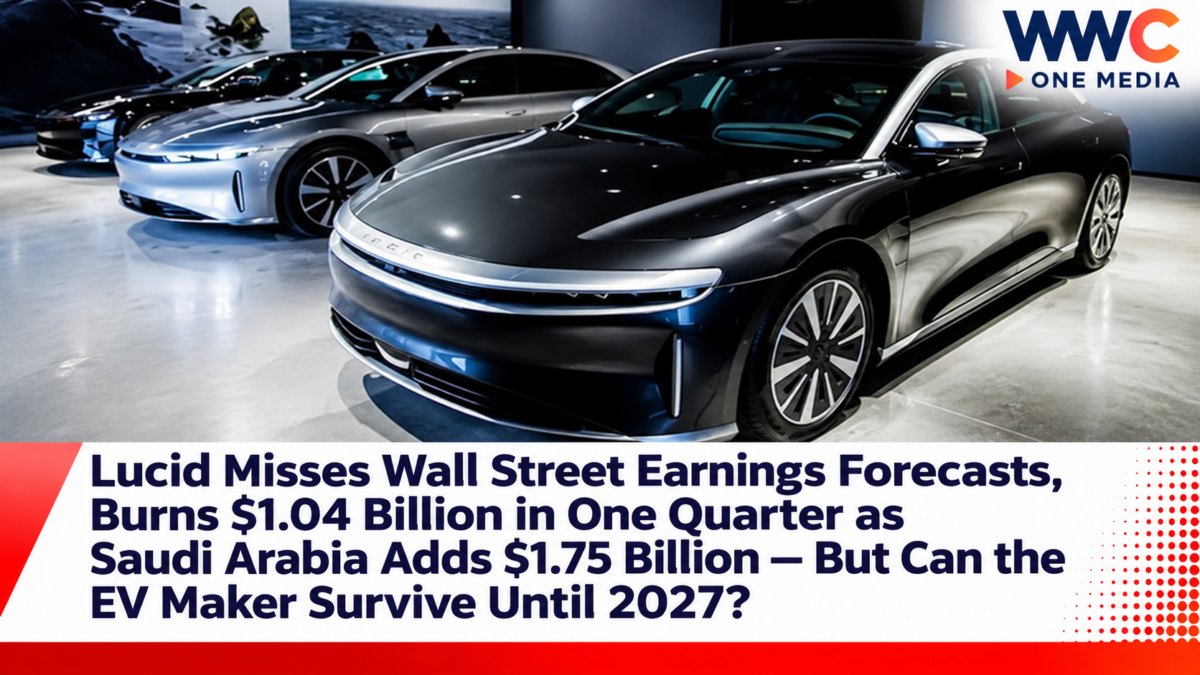
NEWARK, CALIFORNIA — November 10, 2026 — Luxury electric-vehicle manufacturer Lucid Group is facing another critical test of its financial survival after reporting disappointing third-quarter earnings, even as its latest restructuring sharply reduced cash consumption and Saudi Arabia’s sovereign wealth fund expanded its financial backing.
The American automaker reported $350 million in third-quarter revenue, missing Wall Street expectations of approximately $407 million.
Revenue increased 4% from a year earlier, but the result revealed the continuing challenges facing a company competing in a slowing US electric-vehicle market.
Lucid also reported a net loss of approximately $830.9 million, compared with a loss of $978.4 million in the same period last year.
The company has made progress on one of its most important objectives: reducing the amount of cash it consumes.
Quarterly free-cash-flow consumption fell 30% to $1.04 billion, compared with approximately $1.48 billion during the previous quarter.
But the improvement did not eliminate Lucid’s financing problem.
The company continues spending more cash than its operations generate and must finance the development of future vehicles, autonomous-driving technology and new manufacturing facilities.
In response, Lucid announced an additional $1.75 billion in borrowing capacity through a loan facility backed by Saudi Arabia’s Public Investment Fund.
Management believes its expanded financial resources will support operations into the fourth quarter of 2027.
That timetable is especially important because Lucid is preparing to introduce its more affordable midsize electric-vehicle platform in the second half of next year.
The biggest question now is whether Lucid can reduce its losses quickly enough to reach its next generation of vehicles—or whether another multibillion-dollar financing requirement could emerge before the turnaround succeeds.
Lucid Earnings Miss Wall Street Forecasts
Lucid’s November 9 financial results confirmed that the company remains under pressure despite the continued development of its Air sedan and Gravity SUV.
Analysts surveyed by LSEG had expected revenue of approximately $407 million.
Lucid instead generated $350 million.
CNBC also reported a loss-per-share figure of $2.74, compared with an expected loss of $2.28 per share.
Investors reacted negatively to the results, with Lucid shares falling approximately 5% in after-hours trading following the announcement, according to Reuters.
However, the company pointed to improved gross margins and lower cash consumption as evidence that its restructuring is beginning to deliver results.
For shareholders, this creates a mixed picture.
Sales remain below expectations, and losses are substantial.
But management has also demonstrated progress in controlling spending.
That tension is likely to dominate investor discussions until Lucid can deliver sustained improvement in revenue, production efficiency and cash flow.
Lucid Reduces Quarterly Cash Consumption by 30%
The most encouraging development in the earnings report was Lucid’s reduction in free-cash-flow consumption.
The company consumed $1.04 billion during the third quarter, down from approximately $1.48 billion in the second quarter.
The improvement reflects an operational restructuring introduced earlier this year.
Lucid has deliberately reduced manufacturing output, eliminated a second production shift and taken steps to lower inventory and operating expenses.
Chief Financial Officer Alexander De Bock said the company was beginning to see results from those measures.
Lucid has also established a broader $1.4-billion cash-flow improvement plan for 2026.
By the end of September, the company said it had achieved approximately $800 million in improvements under that program.
The remaining target will require further execution.
Importantly, reducing cash consumption does not mean Lucid has become profitable.
The company still used more than $1 billion in free cash flow during the quarter.
If that level of spending continued indefinitely, Lucid would require substantial additional funding.
That is why its financing arrangements remain central to the turnaround.
Saudi Arabia Expands Lucid’s Financial Lifeline by $1.75 Billion
Lucid’s largest investor, Saudi Arabia’s Public Investment Fund, continues to provide critical financial support.
On November 9, the automaker announced a $1.75-billion expansion of its delayed-draw term-loan facility.
The arrangement increases Lucid’s available financing capacity.
At the end of September, the company reported approximately $2 billion in total liquidity, including available borrowing facilities.
After incorporating the newly announced expansion, management calculated pro forma liquidity of approximately $3.75 billion.
This is a crucial distinction.
The $3.75-billion figure does not mean Lucid has that entire amount sitting in its bank accounts.
It includes financing capacity available under specified arrangements.
The company’s balance sheet showed approximately $931 million in cash and cash equivalents at September 30.
Borrowed funds also create repayment obligations and financing costs.
Nevertheless, the additional Saudi support provides Lucid with greater flexibility while it implements its restructuring and prepares new vehicles.
Management expects the expanded liquidity resources to support operations and essential investments into the fourth quarter of 2027.
That forecast depends on its assumptions about cash spending, financing availability and operational progress.
It is not a guarantee that Lucid will never need to raise additional capital.
Why Lucid Is Building Fewer Cars
One of Lucid’s most dramatic operational changes involves production.
During the third quarter, the automaker manufactured 2,954 vehicles and delivered 3,806 vehicles.
Deliveries exceeded production because Lucid was deliberately reducing existing inventory.
The strategy follows the company’s decision to remove its second manufacturing shift in Arizona.
Lucid believes producing fewer vehicles in the near term can help prevent unwanted inventory from accumulating.
That is important because finished vehicles tie up working capital until they are sold.
Factories also incur substantial expenses even when production volume is limited.
The reduction in output reflects a difficult balancing act.
Lucid needs enough vehicles to meet customer demand and support future growth.
But producing cars significantly faster than customers buy them can place additional pressure on cash.
As previously reported by WWC ONE MEDIA, Lucid’s October production announcement highlighted a 38% sequential drop in output and its emphasis on reducing cash consumption.
Related WWC ONE MEDIA coverage: Lucid Delivers 3,806 EVs in Q3 as Production Plunges 38% — But Its Bigger Battle Is Burning Less Cash
The November earnings report now provides a clearer view of the financial consequences of that strategy.
Cash consumption improved significantly, although total losses remained high.
Workforce Reductions Become Part of the Turnaround
The financial restructuring has also affected Lucid employees.
Reuters reported that the company’s workforce declined by approximately 28% between the first and third quarters of 2026.
The reduction followed earlier cost-cutting announcements and operational changes.
Management has sought to simplify its organizational structure, reduce expenses and improve accountability.
The decision to eliminate a second manufacturing shift also reflects an effort to match factory operations more closely with actual vehicle demand.
But workforce reductions create their own risks.
Companies must retain the engineering, manufacturing, service and technical expertise needed to launch new products.
If restructuring weakens those capabilities, cost savings could come at the expense of future growth.
Lucid’s next major challenge is demonstrating that it can operate with a smaller cost base while still delivering complex automotive programs.
Lucid’s Affordable Midsize SUV Could Determine Its Future
Lucid’s existing vehicles compete primarily in the premium electric-vehicle market.
The Lucid Air and Gravity offer advanced technology, but their pricing limits the number of potential buyers.
To expand beyond that segment, the company is developing a more affordable midsize platform.
The first vehicle is expected to enter production during the second half of 2027.
Lucid plans to announce additional details concerning the vehicle’s reveal and production schedule during the first quarter of next year.
The company is targeting a price category below its existing luxury vehicles, potentially placing it in a more competitive part of the EV market.
However, the midsize program has already experienced delays.
Production was previously expected earlier.
The revised schedule creates additional pressure on the company to manage cash carefully until the vehicle becomes available.
The product also faces major competition.
Tesla, Rivian and established global manufacturers continue expanding their electric-vehicle lineups.
As WWC ONE MEDIA previously reported, Tesla delivered 486,532 vehicles worldwide during the third quarter despite facing its own market challenges.
Related WWC ONE MEDIA coverage: Tesla Delivers 486,532 Vehicles and Beats Wall Street — But the Bigger EV Recovery Is Far From Even
Lucid’s midsize model could dramatically expand its potential customer base.
But its success will depend on pricing, manufacturing costs, vehicle quality, competition and consumer demand.
Uber and Nuro Robotaxi Partnership Offers Another Growth Opportunity
Lucid is also working to establish a business beyond conventional vehicle sales.
The company is developing autonomous ride-hailing vehicles through a partnership with Uber and self-driving technology company Nuro.
Lucid reported that the program had achieved its scheduled third-quarter milestones.
By August, the project involved more than 100 vehicles operating within its development and testing program.
The collaboration uses Lucid vehicles equipped with autonomous-driving systems.
The long-term objective is to deploy driverless vehicles in commercial ride-hailing services.
A successful robotaxi business could provide Lucid with a new source of demand.
Instead of relying entirely on private consumers purchasing expensive electric cars, the company could supply vehicles for mobility fleets.
But the project remains subject to development, safety requirements and regulatory approvals.
Vehicles undergoing testing are not equivalent to a fully deployed, profitable commercial fleet.
The partnership therefore represents an opportunity, not a guaranteed solution to Lucid’s financial difficulties.
Bolt Partnership Opens Another Potential Market in Europe
Lucid’s autonomous-driving ambitions also extend to Europe.
The company announced a partnership with mobility platform Bolt, with an initial deployment ambition involving at least 25,000 vehicles.
The arrangement reflects the industry’s growing interest in autonomous ride-hailing.
Bolt is also participating in other driverless-transportation initiatives involving different manufacturers.
As previously covered by WWC ONE MEDIA, Bolt and Stellantis have been involved in plans to test autonomous vehicles in Greater Paris beginning in 2028.
Related WWC ONE MEDIA coverage: Bolt and Stellantis to Bring Self-Driving Cars to Paris by 2028 — But Could Robotaxis Replace Human Drivers by 2030?
That Paris project is separate from Bolt’s partnership with Lucid.
The connection is the wider market interest in developing autonomous mobility services.
For Lucid, fleet partnerships may eventually help justify its investment in vehicles and self-driving technology.
But these initiatives require considerable time and capital before they can generate meaningful revenue.
Saudi Manufacturing Plant Expected to Open in Early 2027
Lucid is also expanding its manufacturing footprint outside the United States.
The company’s Advanced Manufacturing Plant 2, or AMP-2, is under development in Saudi Arabia.
Management said the facility had entered the final stages of industrialization and commissioning.
Its inauguration is expected in early 2027.
The project is strategically important to Saudi Arabia’s effort to diversify its economy beyond oil.
It also deepens the relationship between Lucid and its largest financial backer.
However, expanding a manufacturing facility requires substantial investment.
The plant will need to achieve operational readiness, establish production processes and manage supplier relationships.
An inauguration milestone does not mean the factory will immediately operate at full capacity or generate profits.
Lucid will need to balance the costs of developing the Saudi operation against its continuing need to conserve cash.
Rivian’s Results Show the EV Industry’s Financial Challenge
Lucid is not alone in trying to balance growth and cash consumption.
Rivian, another American electric-vehicle manufacturer, has faced similar questions about scaling production and financing future models.
While Rivian has reported stronger revenue growth, it also continues to manage significant capital requirements.
As WWC ONE MEDIA previously examined, Rivian’s growing sales have not eliminated investor concerns about cash burn.
Related WWC ONE MEDIA coverage: Rivian Revenue Surges 38% to $2.16 Billion as R2 Becomes Its Best-Seller — But Can the EV Maker Survive Its $1.1-Billion Cash Burn?
The companies have different products, manufacturing strategies and financing arrangements.
But both illustrate a structural challenge in the EV industry.
Designing and producing automobiles requires significant capital before manufacturers achieve sufficient scale.
Revenue growth alone does not necessarily produce positive cash flow.
Automakers also need efficient factories, manageable operating costs and sustainable pricing.
US Electric-Vehicle Demand Adds More Pressure
Lucid is implementing its turnaround during a difficult period for the US battery-electric-vehicle market.
According to S&P Mobility figures cited by the company, the US battery-electric-vehicle market declined approximately 41% year over year during the third quarter.
Changes in tax incentives, vehicle affordability and consumer demand have affected the industry.
Some automakers have reduced production or revised their plans for new electric models.
Others have focused on hybrid vehicles or more affordable options.
Lucid’s 4% revenue increase compares favorably with the broader market contraction cited in its earnings release.
However, the comparison does not eliminate the company’s underlying challenges.
Its sales remain relatively small compared with major automakers.
Its losses are substantial.
And demand for premium EVs may remain sensitive to economic conditions.
These pressures strengthen the argument for developing more affordable vehicles and lowering fixed costs.
What Investors Should Watch Before the End of 2026
Several developments will determine whether Lucid’s turnaround continues.
The first is free cash flow.
Investors will want to see whether the company can reduce cash consumption further without compromising product development.
The second is inventory.
Lower production can improve working capital, but the company must also demonstrate sustainable customer demand.
The third is the midsize vehicle program.
Further delays could increase pressure on liquidity.
The fourth is Saudi manufacturing.
The AMP-2 facility needs to progress according to its expected schedule.
The fifth is autonomous mobility.
Lucid’s partnerships with Uber, Nuro and Bolt must eventually move beyond testing and commitments toward commercial deployment.
Finally, the company will need to explain how its financial position evolves as it draws on available borrowing facilities.
Lucid plans to provide 2027 guidance and additional medium-term financial targets alongside its year-end results.
Those disclosures may help investors assess whether management’s planned improvements are achievable.
The Bigger Picture: Is Lucid Finally Turning Around?
Lucid’s third-quarter results show real progress in financial discipline.
The company reduced free-cash-flow consumption by 30%.
It has achieved approximately $800 million of its $1.4-billion cash-flow improvement target.
And Saudi-backed financing provides greater liquidity as the automaker prepares its next generation of vehicles.
But Lucid remains unprofitable.
Revenue missed Wall Street expectations.
The company continues to spend more than $1 billion in free cash flow during a single quarter.
And its future growth depends heavily on projects that have not yet achieved full commercial scale.
The midsize vehicle could reach a wider customer base.
Robotaxi partnerships could provide large institutional orders.
Saudi manufacturing could strengthen production capabilities.
But every one of these opportunities involves execution risks.
Lucid has bought itself more time and demonstrated an ability to cut costs. It has not yet proved that its business can sustain itself without repeated financing support.
And as Saudi Arabia expands its financial backing while Lucid prepares a more affordable SUV and autonomous-vehicle partnerships, the question facing investors is becoming impossible to ignore: Will the company’s $3.75-billion liquidity buffer finally carry it into a profitable new era—or will the cash run out faster than the turnaround can deliver?