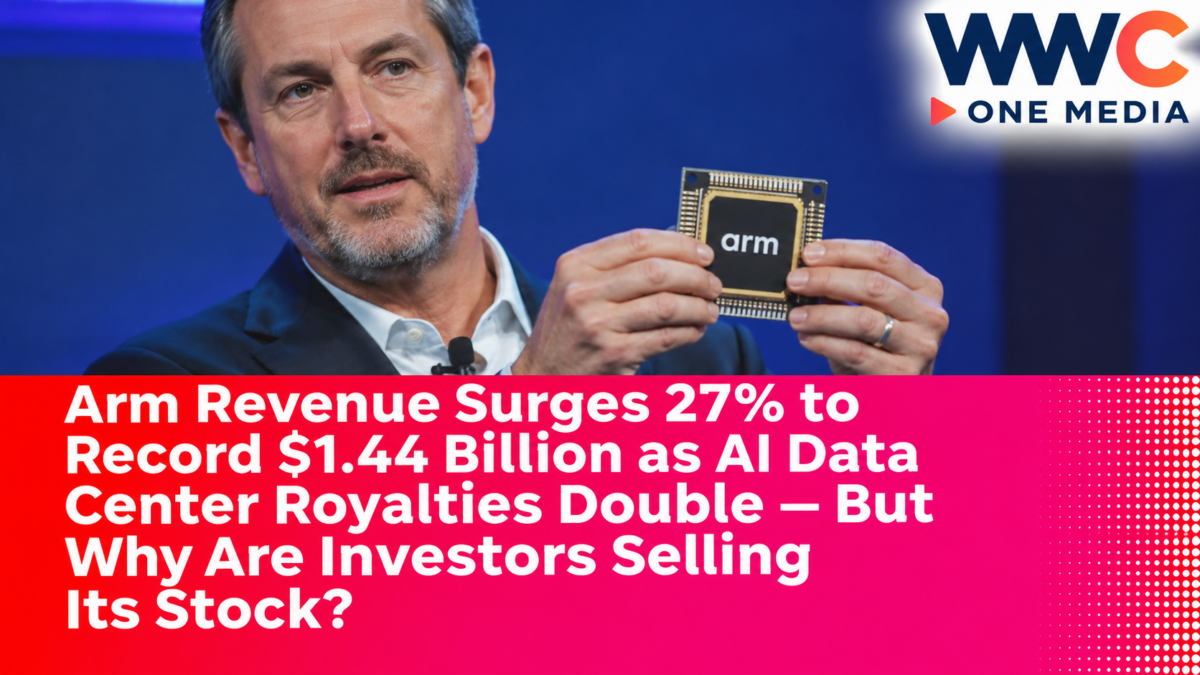
CAMBRIDGE, UNITED KINGDOM / NEW YORK / MANILA — British semiconductor technology giant Arm Holdings has delivered a record $1.44 billion in quarterly revenue, fueled by surging demand for artificial intelligence computing and a rapid expansion of its chip architecture inside the world’s largest data centers.
The results offer fresh evidence that the global AI infrastructure boom is creating enormous opportunities beyond companies manufacturing high-performance graphics processors.
But Wall Street’s reaction was surprisingly cautious.
Despite beating analysts’ revenue and earnings forecasts, Arm shares declined in after-hours trading as investors questioned whether the company’s future growth outlook was strong enough to justify its elevated valuation.
Arm reported a 27% increase in revenue for its fiscal second quarter ended September 30, 2026, marking its fifth consecutive quarter of annual revenue growth exceeding 20%.
Licensing and other revenue jumped 50% to $773 million, while royalty revenue increased 8% to $670 million.
Most significantly, royalties generated by data center applications doubled from a year earlier.
The company also strengthened its confidence in generating up to $2 billion from its new Arm AGI CPU across fiscal 2027 and fiscal 2028, as orders from major technology customers accelerate.
Yet the business faces growing challenges from a weakening smartphone market, expensive memory components, semiconductor supply constraints and uncertainty surrounding the profitability of the broader AI investment boom.
As Arm expands its influence across global cloud computing and prepares to sell its own AI server processors, can it turn record demand into sustainable profits—or will Wall Street’s expectations prove impossible to satisfy?
Arm Reports Record $1.44 Billion in Quarterly Revenue
Arm’s November 4 earnings announcement confirmed another period of strong revenue growth.
Total revenue reached approximately $1.443 billion, an increase of 27% compared with the corresponding quarter a year earlier.
The result exceeded the approximately $1.38 billion expected by analysts surveyed by LSEG.
Adjusted earnings reached $0.52 per share, above estimates of roughly $0.47 to $0.48.
On a generally accepted accounting principles basis, however, net income declined to approximately $130 million, compared with $238 million a year earlier.
That distinction matters because adjusted earnings exclude certain expenses and accounting adjustments that remain relevant to shareholders.
Arm’s financial performance was supported by growing licensing agreements with technology customers and increasing deployment of its processor architecture in AI computing systems.
Chief Executive Rene Haas emphasized that artificial intelligence is expanding demand for computing power across cloud infrastructure, consumer devices and autonomous systems.
But the company’s outlook was less dramatic than some investors had hoped.
Arm Forecasts $1.54 Billion in Revenue for the Next Quarter
For its fiscal third quarter, covering October through December 2026, Arm forecast approximately $1.54 billion in revenue, plus or minus $50 million.
That compares with Wall Street’s average estimate of approximately $1.53 billion.
The company also projected adjusted earnings of about $0.56 per share, plus or minus $0.04.
Although the revenue forecast was slightly above consensus, it did not represent a major upward surprise.
Reuters reported that Arm shares fluctuated following the announcement and fell during extended trading.
The muted reaction reflected the difference between reporting strong results and exceeding investors’ already elevated expectations.
Arm had experienced a substantial share-price advance during 2026, increasing sensitivity to even modest disappointments.
Investors must therefore distinguish the company’s underlying growth from the valuation assigned to that growth by the stock market.
Strong operating results do not guarantee a rising share price.
AI Data Center Royalties Double as Arm Challenges Intel and AMD
Perhaps the most important development in Arm’s earnings report was the expansion of its data center business.
The company said royalties from data center applications doubled compared with a year earlier.
It also reported that Arm-based processors accounted for more than 50% of server deployments at leading hyperscale cloud providers during calendar 2025, compared with approximately 15% in 2024.
Arm expects that figure to exceed 60% by the end of 2026.
These are Arm’s reported market-share estimates and projections for a defined group of major cloud operators, not independently verified figures for the entire global server market.
Nevertheless, the increase demonstrates the company’s growing importance in high-performance computing.
For years, Intel’s x86 architecture dominated traditional servers, with AMD becoming a significant competitor.
Arm has steadily expanded its position through processor designs focused on power efficiency and increasingly sophisticated computing workloads.
The AI revolution has made that efficiency more valuable.
Data centers require enormous amounts of electricity to operate processors, networking equipment and cooling systems.
Even relatively small improvements in performance per watt can become financially important when deployed across thousands of servers.
Amazon, Google and Microsoft Are Driving Adoption
Arm’s growth is closely linked to custom chip development among the world’s largest cloud companies.
Amazon Web Services uses its Arm-based Graviton processors in cloud computing services.
Google has developed the Arm-based Axion processor.
Microsoft’s Azure cloud platform has introduced Cobalt processors.
Nvidia is also using Arm technology in its Vera CPU platform.
Arm said major customers are increasingly choosing its architecture as they optimize computing systems for specific AI and cloud workloads.
These deployments can benefit Arm in two ways.
First, technology companies may pay licensing fees to incorporate Arm designs or intellectual property into their products.
Second, Arm can receive royalties when qualifying chips using its technology are shipped.
The expansion of custom processors could therefore create recurring revenue opportunities.
However, the value of future royalties will depend on chip volumes, contract terms, product mix and technology adoption.
Arm’s New AGI CPU Could Transform Its Business Model
Arm is also taking a more direct role in the semiconductor market.
Historically, the company has been best known for licensing processor intellectual property rather than selling its own completed chips.
Its new Arm AGI CPU represents a significant expansion of that business model.
The company plans to supply purpose-built processors designed for demanding AI and data center applications.
Arm said it now has greater confidence in achieving up to $2 billion in AGI CPU revenue across fiscal 2027 and fiscal 2028.
Management cited stronger customer demand, additional production capacity and purchase orders extending through calendar 2027.
The company expects its first commercial deliveries during the fourth quarter of fiscal 2027.
Oracle Cloud Infrastructure has announced plans to offer instances based on the processor in 2027.
Arm’s move into direct chip sales could increase its potential revenue per customer.
But it also creates new operational challenges.
Selling physical silicon requires manufacturing arrangements, supply-chain management, inventory planning and greater exposure to component availability.
These are different risks from those associated with licensing intellectual property.
The projected $2 billion is a forward-looking business target—not completed revenue.
Memory Shortages Could Become Arm’s Biggest Unexpected Problem
One of the most important risks involves memory chips.
AI infrastructure requires substantial quantities of advanced memory, placing pressure on global manufacturing capacity.
The resulting shortages and price increases can affect other parts of the electronics market.
Arm benefits from strong AI investment, but the same investment cycle can make smartphones and other devices more expensive to manufacture.
Higher memory costs may reduce device shipments or encourage manufacturers to delay upgrades.
That can affect the number of processors incorporating Arm technology.
Arm’s royalty revenue increased only 8% in the quarter, significantly below the 50% growth in licensing revenue.
Reuters reported that royalty revenue also missed analysts’ estimates.
This suggests that booming AI licensing demand is not yet translating into equally rapid growth across all royalty-generating products.
WWC ONE MEDIA previously examined the supply-chain challenge in Nokia Says AI Data Centers Could Be Built Twice as Fast — But Power and Memory Are Becoming the Real Bottleneck.
The broader issue is that AI demand can simultaneously create new revenue opportunities and increase production costs elsewhere in the technology industry.
AMD’s AI Chip Boom Shows How Fierce the Competition Has Become
Arm’s growth comes as semiconductor competitors race to benefit from AI infrastructure spending.
Advanced Micro Devices recently reported a major increase in data center revenue and issued an optimistic outlook for its next quarter.
WWC ONE MEDIA covered the development in AMD’s $17 Billion AI Chip Forecast Crushes Wall Street Estimates as Data Center Sales Soar 97% — But Can Lisa Su Finally Challenge Nvidia’s Dominance?.
The competition is complicated because Arm is both a technology supplier to some chip developers and a competitor in selected processor markets.
An AMD server processor may compete against an Arm-based alternative.
At the same time, Nvidia and other technology companies use Arm intellectual property in their products.
The distinction means Arm can benefit from industry growth without depending entirely on one processor manufacturer winning market share.
However, its increasing involvement in selling completed CPUs could create more direct competition with companies that have traditionally been customers or ecosystem partners.
Nvidia’s Growing Arm Ecosystem Creates Opportunities
Nvidia’s expanding AI computing platform is another important source of interest.
Modern AI systems require more than graphics processing units.
They also depend on CPUs to coordinate computing tasks, manage workloads and operate supporting infrastructure.
Arm-based processors are increasingly appearing alongside specialized AI accelerators.
WWC ONE MEDIA previously examined the broader Nvidia ecosystem in Nvidia’s Jensen Huang Backs $115-Billion Marvell–Lumentum AI Megadeal — But Why Did Investors Wipe Billions Off Both Stocks?.
That report explored the financial and technological pressures affecting suppliers of advanced computing and connectivity products.
The relevance to Arm is the increasing complexity of AI infrastructure.
Large computing systems require processors, accelerators, memory, networking components and high-speed connections.
Demand for more specialized systems creates opportunities for companies supplying foundational semiconductor technologies.
But investment opportunities across this ecosystem carry different commercial and execution risks.
Foxconn’s AI Server Expansion Supports the Demand Outlook
Strong demand for AI computing equipment is also visible among major electronics manufacturers.
Foxconn has reported substantial growth in its cloud and networking business and ambitious plans to expand AI server production.
WWC ONE MEDIA covered the strategy in Foxconn Targets 50% of Global AI Server Market as Factories Fill Up for 18 Months — But Could a Trillion-Dollar AI Spending Gamble Backfire?.
Foxconn’s management has described strong customer demand and significant production commitments.
That supports the broader view that AI infrastructure investment remains substantial.
However, strong orders at a server manufacturer do not establish that all products use Arm technology.
Different systems may combine x86 processors, Arm-based CPUs, GPUs and other specialized components.
Arm must continue winning specific design opportunities and converting those designs into shipments that generate revenue.
Electricity Consumption Is Becoming Central to the AI Race
Arm’s power-efficiency strategy is becoming more important as governments and companies confront the cost of operating AI data centers.
Large facilities may require substantial upgrades to electricity networks and cooling systems.
In some locations, power connections can take years to secure.
Higher electricity demand can also create political opposition to new infrastructure projects.
For semiconductor companies, this raises the value of technology that delivers more computing performance for each unit of energy consumed.
Arm is positioning its architecture around that demand.
However, independent performance comparisons must be interpreted carefully.
Results can depend on workloads, system configuration, software optimization and the specific processors being tested.
A favorable benchmark does not prove that one architecture is superior for every application.
The commercial importance of efficiency will ultimately depend on how customers evaluate total system costs and actual performance.
Why Arm’s Licensing Business Still Matters
Despite the excitement surrounding its new AGI CPU, licensing remains central to Arm’s operations.
Licensing and other revenue increased 50% to $773 million during the quarter.
That growth reflected stronger demand for advanced processor technology and the timing of major licensing agreements.
Licensing revenue can be an early indication of future product development.
A customer may purchase access to Arm technology well before a completed chip reaches commercial production.
If that chip succeeds and ships in substantial volume, Arm may subsequently generate royalty revenue.
But not every licensed design becomes a high-volume commercial product.
Some projects are delayed, modified or canceled.
For that reason, the 50% licensing increase should not be interpreted as a guarantee that future royalty revenue will grow by the same percentage.
The latest results show strong demand for Arm’s technology while leaving important questions about future shipment volumes.
Why Qualcomm’s Legal Dispute Is Another Risk
Arm’s earnings announcement also followed developments in its legal dispute with Qualcomm.
A Delaware jury recently found that Arm had breached certain provisions of its licensing agreement with Qualcomm and interfered with Qualcomm’s relationship with Meta.
The jury awarded nominal damages of $2.
However, other disputes concerning licensing arrangements and future contractual obligations remained unresolved.
The verdict does not automatically determine the outcome of every issue between the companies.
A judge is expected to address outstanding matters.
The dispute is significant because Arm’s business depends on long-term licensing relationships with semiconductor developers.
Legal uncertainty can influence how investors assess future royalty payments, customer relationships and commercial arrangements.
Nevertheless, the existence of litigation does not establish that Arm’s broader licensing model is invalid.
What Arm’s Results Mean for Asian Semiconductor Companies
The company’s expansion has important implications for Asia.
Taiwan plays a central role in manufacturing advanced semiconductor products.
South Korean companies supply memory chips essential to AI infrastructure.
Major Asian electronics manufacturers assemble servers, smartphones and other devices using technologies licensed from Arm and its competitors.
A growing market for Arm-based server processors could create additional opportunities across these supply chains.
However, changes in processor architecture may also affect companies differently.
Manufacturers specializing in one platform may need to adjust equipment, software or product designs.
For the Philippines, expanding global semiconductor investment could support opportunities in electronics manufacturing, testing and related services.
But the degree of benefit would depend on actual contracts, local investment and the capabilities of individual companies.
Arm’s strong results alone do not guarantee additional jobs or exports in the Philippines.
Could the AI Spending Boom Become a Financial Bubble?
The scale of investment in artificial intelligence remains a major concern for financial markets.
Technology companies are spending enormous sums on chips, servers, networking equipment and electricity infrastructure.
For suppliers such as Arm, these investments create opportunities to license technology and sell processors.
But their long-term sustainability depends on whether AI services generate enough economic value to support the infrastructure being built.
WWC ONE MEDIA examined that dilemma in Marvell’s $115-Billion Lumentum Deal Sends Its Stock Tumbling as AI Fears Explode — But Did Wall Street Just Reject the Biggest Bet on Optical Chips?.
The broader lesson is that strong AI demand does not eliminate financial risk.
High valuations may leave little room for disappointing forecasts.
Rising construction or component costs can pressure profitability.
And customers may reconsider spending if returns fall short of expectations.
Arm’s after-hours share-price reaction shows that investors are becoming more selective about how they value AI-related growth.
Three Critical Developments Investors Should Watch
First, can Arm deliver its new AGI CPU at commercial scale?
The company expects first commercial deliveries during its fiscal fourth quarter of 2027 and is targeting up to $2 billion in combined revenue across fiscal 2027 and 2028.
Actual shipments and sales will be critical.
Second, will licensing growth translate into stronger royalties?
Licensing revenue surged 50%, but total royalties increased only 8%.
Investors will monitor whether new chip designs move into high-volume production.
Third, can Arm maintain its cloud-computing momentum?
The company expects Arm-based processors to account for more than 60% of server deployments at leading hyperscalers by the end of 2026.
Achieving that projection would strengthen its position in an increasingly competitive market.
The Bigger Picture: Is Arm Becoming an AI Infrastructure Powerhouse?
Arm’s record quarterly results highlight an important transformation in the semiconductor industry.
The company is no longer associated primarily with smartphones.
Its processor architecture is becoming increasingly important in cloud computing, AI infrastructure, personal computers and intelligent devices.
Revenue grew 27% to $1.44 billion.
Licensing revenue surged 50%.
Data center royalties doubled.
And management expressed greater confidence in the commercial potential of its new AGI CPU.
Yet the company also faces meaningful risks.
Royalty growth remains uneven.
Smartphone demand is sensitive to component prices.
The new silicon business introduces manufacturing and supply-chain challenges.
Legal disputes continue.
And investors have already assigned substantial value to Arm’s future growth.
The next stage of its development will depend on turning processor designs and customer commitments into recurring revenue and sustainable profitability.
As Arm’s data center royalties double and its revenue climbs to a record $1.44 billion, can the company become one of the biggest winners of the global AI revolution—or will supply shortages, slowing royalty growth and sky-high investor expectations turn its remarkable expansion into Wall Street’s next disappointment?