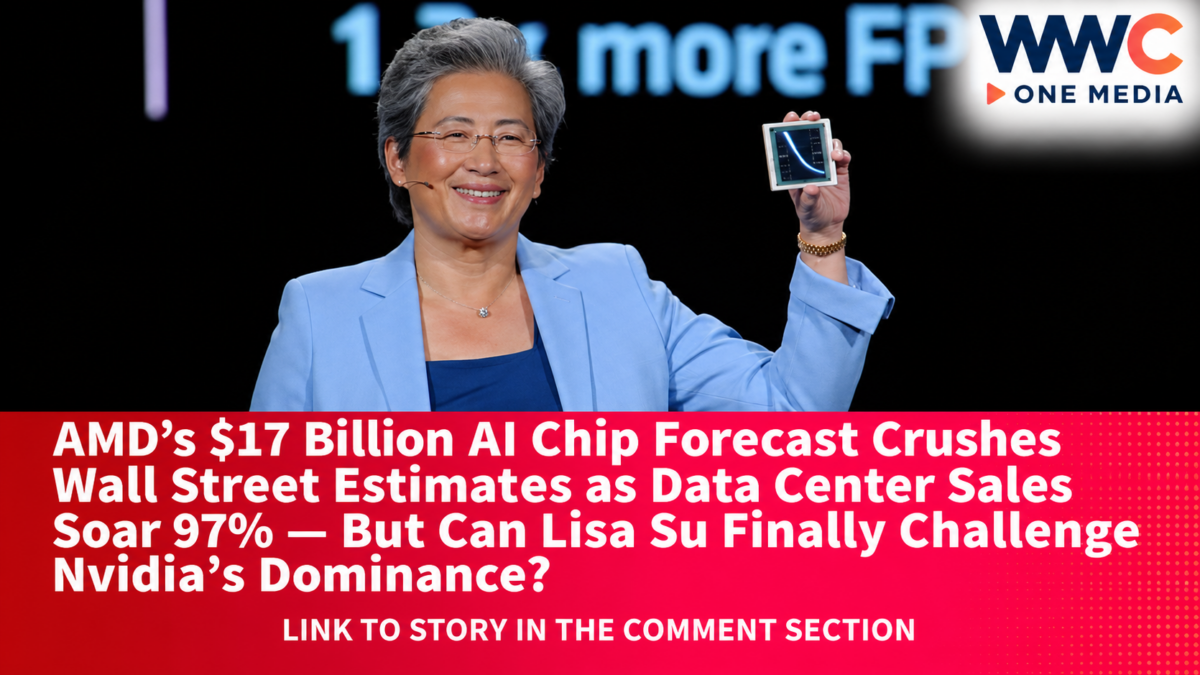
SANTA CLARA, CALIFORNIA / MANILA — Advanced Micro Devices (AMD) has delivered one of the strongest earnings performances in its history, forecasting a staggering $17 billion in fourth-quarter revenue as demand for artificial intelligence processors and data center infrastructure accelerates.
The announcement sent AMD shares sharply higher in after-hours trading on November 3, offering Wall Street fresh evidence that the global AI spending boom continues to generate substantial revenue for semiconductor manufacturers.
According to Bloomberg, Reuters and AMD’s official earnings release, the company’s fourth-quarter revenue outlook exceeded analysts’ expectations of approximately $16.2 billion to $16.3 billion.
The forecast followed record third-quarter revenue of $13.38 billion, a 45% increase from the previous year.
More importantly, AMD’s data center division generated approximately $8.55 billion, surging 97% year over year as demand strengthened for EPYC server processors and Instinct artificial intelligence accelerators.
CEO Lisa Su also delivered a remarkable prediction: AMD expects total revenue to grow more than 80% in 2027, with its data center business driving much of that expansion.
But behind the extraordinary figures lies a much bigger question.
As AMD races to challenge Nvidia’s dominance, global memory shortages, soaring infrastructure costs and intense competition threaten to complicate its expansion.
Can AMD turn the AI computing revolution into a lasting competitive advantage—or could the next phase of the semiconductor boom become its most dangerous financial gamble?
AMD Forecasts $17 Billion in Fourth-Quarter Sales, Beating Wall Street Expectations
AMD’s latest earnings announcement delivered a significant upside surprise.
For the fourth quarter of 2026, the company expects revenue of approximately $17 billion, with a possible variation of 3%.
That implies a revenue range of approximately $16.49 billion to $17.51 billion.
Analysts surveyed by LSEG had expected around $16.23 billion.
At the midpoint, AMD’s guidance is approximately $770 million above that estimate.
The projected fourth-quarter revenue would represent growth of about 66% from the corresponding period in 2025 and approximately 27% from the third quarter of 2026.
The outlook demonstrates the momentum AMD is experiencing as major technology companies expand their artificial intelligence infrastructure.
However, the $17 billion figure is a projection rather than completed sales.
Actual results will depend on customer demand, production capacity, product deliveries and other market conditions.
AMD also expects a fourth-quarter adjusted gross margin of approximately 55%.
That is slightly below its third-quarter adjusted margin of 56%, demonstrating that rapid revenue growth does not automatically guarantee improving margins.
AMD’s Third-Quarter Revenue Jumps 45% as Profits Surge
AMD reported revenue of $13.377 billion for the third quarter, up from $9.246 billion a year earlier.
The company’s financial performance improved substantially across several key measures.
Operating income under generally accepted accounting principles rose 123% to approximately $2.83 billion.
GAAP net income increased 95% to $2.43 billion.
Adjusted operating income climbed 75% to $3.92 billion, while adjusted net income rose 77% to $3.47 billion.
Adjusted diluted earnings per share reached $2.09, representing 74% annual growth.
That exceeded the approximately $1.97 per share expected by analysts.
The results indicate that AMD is generating stronger profitability as its data center business expands.
The company is benefiting not only from rising demand for advanced computing hardware but also from greater scale in its operations.
Still, investors should distinguish AMD’s reported GAAP earnings from adjusted figures, which exclude certain expenses.
The two measures provide different perspectives on profitability and should not be used interchangeably.
Data Center Revenue Nearly Doubles to $8.55 Billion
The strongest evidence of AMD’s transformation came from its data center business.
The division generated approximately $8.55 billion in third-quarter revenue, an increase of 97% from the previous year.
That represented almost 64% of AMD’s total quarterly revenue.
The growth was supported by demand for two major product categories.
AMD Instinct accelerators are designed for demanding artificial intelligence workloads, including training and running large AI models.
AMD EPYC server processors support cloud computing, enterprise applications and the broader processing requirements of modern data centers.
The combination allows AMD to participate in multiple parts of the AI infrastructure market.
Its customer base includes major cloud providers, AI developers and businesses expanding computing capacity.
The latest performance suggests that demand is extending beyond the specialized graphics processors typically associated with the AI boom.
Server CPUs remain important because AI systems require extensive supporting computing resources to handle data, applications and increasingly complex automated workloads.
This gives AMD an opportunity to benefit from demand across different parts of the data center.
Lisa Su Predicts More Than 80% Revenue Growth in 2027
AMD’s most ambitious projection concerns 2027.
During the company’s earnings conference call, CEO Lisa Su said AMD expects overall revenue to grow by more than 80% next year.
The prediction exceeded the approximately 77% growth anticipated by analysts surveyed by LSEG.
Su expects data center products to account for around 80% of the company’s revenue in 2027.
If achieved, that would represent a dramatic transformation for a business historically associated with desktop processors, laptops, gaming hardware and server chips.
The company is increasingly positioning itself as a comprehensive supplier of AI computing infrastructure.
However, the forecast is not guaranteed.
Revenue depends on AMD’s ability to increase production, secure critical components, deliver products on schedule and maintain demand from major customers.
WWC ONE MEDIA previously examined AMD’s supply-chain ambitions in AMD Plans Major Chip Supply Increase in 2027 as AI Demand Surges.
That report highlighted Su’s efforts to secure additional manufacturing capacity and prepare suppliers for several years of expected computing demand.
The company’s latest financial guidance suggests that expanding chip supply has become essential to its growth strategy.
AMD’s Helios AI Systems Take Direct Aim at Nvidia
AMD is also changing how it competes in artificial intelligence.
Instead of focusing exclusively on individual processors, the company is expanding into complete rack-scale computing systems.
Its Helios platform combines high-performance accelerators, server processors, networking and other infrastructure components into integrated systems.
This approach is important because large AI customers increasingly want complete computing solutions rather than purchasing individual chips and assembling every component independently.
Nvidia has built a formidable competitive position through its GPUs, software ecosystem, networking technologies and integrated AI infrastructure.
AMD is attempting to offer customers an alternative.
According to Reuters, Helios systems have entered production, with initial units being tested by Meta and a broader rollout planned for the fourth quarter.
AMD’s partnerships with major AI developers and cloud providers could help it expand market share.
But challenging Nvidia involves more than manufacturing powerful processors.
Software compatibility, networking performance, power efficiency, product availability and long-term support all influence purchasing decisions.
Nvidia remains the dominant supplier of AI accelerators.
AMD’s rapid growth does not establish that it has overtaken its rival.
Instead, it suggests that the market may be large enough to support expanding sales for more than one major supplier.
A $115 Billion AI Networking Deal Shows How Intense the Competition Has Become
The semiconductor industry is also experiencing enormous strategic transactions as companies attempt to strengthen their positions in AI infrastructure.
Marvell Technology’s proposed acquisition of Lumentum Holdings highlights the growing importance of optical networking and high-speed data transmission.
WWC ONE MEDIA examined the deal in Marvell’s $115-Billion Lumentum Deal Sends Its Stock Tumbling as AI Fears Explode — But Did Wall Street Just Reject the Biggest Bet on Optical Chips?.
The proposed transaction illustrates how competition in artificial intelligence increasingly extends beyond processors.
Large AI systems need high-speed connections between thousands of chips.
As infrastructure becomes more complex, networking capacity, memory bandwidth and power efficiency become essential.
For AMD, these developments raise the strategic importance of offering customers systems that perform efficiently at scale.
They also increase competitive pressure as semiconductor companies spend heavily to acquire technologies and expand product portfolios.
The Marvell-Lumentum deal remains proposed and subject to completion conditions; its headline value is not evidence of revenue already generated.
AI Memory Shortages Could Become AMD’s Biggest Supply-Chain Problem
Despite AMD’s strong outlook, the semiconductor industry faces a major constraint: memory availability.
Artificial intelligence servers require substantial quantities of high-bandwidth memory, or HBM, to process large datasets efficiently.
Demand from AI data centers has placed significant pressure on memory manufacturers and related supply chains.
According to Reuters, the global shortage of high-bandwidth memory remains a challenge for AMD’s expansion.
The shortage can affect both the availability and cost of advanced AI computing systems.
Semiconductor suppliers must coordinate production across chip fabrication, packaging, memory manufacturing and system integration.
A shortage in one part of the supply chain can delay deliveries even when demand for the finished products remains strong.
The pressure is also affecting consumer electronics.
As manufacturers prioritize high-value AI products, supplies of certain components for laptops and desktop computers can become more constrained.
Higher memory prices may increase the cost of personal computers and gaming hardware.
This creates a paradox for AMD.
The AI boom is driving exceptional growth in its data center operations while also increasing cost and supply pressures in its traditional consumer markets.
PC and Gaming Revenue Declines Despite the AI Boom
Not every part of AMD’s business is experiencing rapid growth.
The company reported combined Client and Gaming segment revenue of approximately $3.7 billion, down 8% from the previous year.
Within that segment, client revenue reached about $2.9 billion, rising 7% year over year.
However, gaming revenue fell approximately 40% to $773 million.
The decline reflected weakness in semi-custom processor and graphics sales.
This divergence illustrates how different parts of the semiconductor market are moving in opposite directions.
AI data center spending remains exceptionally strong.
Consumer technology demand is more sensitive to prices and replacement cycles.
Su expects overall PC shipments to decline by a double-digit percentage in 2027 because of higher system costs and other market pressures.
AMD expects to outperform the broader PC market, but that remains a management forecast.
For investors, the contrast raises an important question about the company’s future revenue mix.
AMD is increasingly dependent on data center growth to offset weakness elsewhere.
That concentration can be highly profitable while demand remains strong, but it may increase exposure if major AI customers eventually slow their spending.
Foxconn’s AI Server Boom Supports AMD’s Demand Outlook
AMD’s optimism is consistent with growing activity among major AI server manufacturers.
Taiwanese manufacturing giant Foxconn has reported exceptionally strong demand for AI infrastructure.
Its chairman, Young Liu, has said that production capacity is heavily booked, reflecting continued investment by cloud providers and technology companies.
WWC ONE MEDIA previously reported the development in Foxconn Targets 50% of Global AI Server Market as Factories Fill Up for 18 Months — But Could a Trillion-Dollar AI Spending Gamble Backfire?.
Foxconn’s manufacturing outlook provides another indication that demand for advanced computing equipment remains substantial.
However, its projected market share and future revenue mix are management expectations, not guaranteed outcomes.
The distinction matters because suppliers across the industry are investing heavily based on forecasts of continued growth.
For AMD, stronger demand from server manufacturers and cloud providers could support additional sales.
But the company must still deliver products at competitive prices while managing component shortages and production costs.
Bank of America’s $2.1 Trillion Data Center Forecast Reveals the Opportunity
The longer-term potential remains enormous.
Bank of America Global Research has projected that worldwide data center spending could reach approximately $2.1 trillion in 2028.
The forecast reflects anticipated investment in processors, networking equipment, computing facilities, electricity systems and supporting infrastructure.
WWC ONE MEDIA examined the projection in Bank of America Predicts $2.1 Trillion AI Data Center Explosion by 2028 — But Could a Global Power Shortage Bring the Entire Boom Crashing Down?.
If global data center construction continues expanding, suppliers such as AMD could benefit from sustained demand for advanced computing products.
But the projection is not guaranteed spending.
Data center projects can be delayed by electricity shortages, construction constraints, financing difficulties or changes in customer demand.
Building facilities also requires specialized equipment, access to reliable power and adequate cooling capacity.
For AMD, the opportunity depends not simply on how much capital technology companies plan to invest, but on how much of that spending ultimately turns into orders for its products.
Wall Street’s AI Bubble Debate Gets a New Reality Check
AMD’s earnings arrived during a period of nervousness across global technology markets.
Investors have increasingly questioned whether the enormous cost of artificial intelligence infrastructure will generate adequate financial returns.
Some of the world’s largest technology companies are spending extraordinary amounts on new computing capacity.
That spending has supported semiconductor sales but also raised concerns about debt, free cash flow and future profitability.
AMD’s latest results provide evidence that suppliers are benefiting from actual orders and recognized revenue.
However, strong semiconductor sales do not independently prove that every AI customer is earning an attractive return on its investment.
The difference is important.
Chipmakers recognize revenue when they sell qualifying products and services.
Their customers must then generate sufficient economic value from that equipment over its useful life.
A profitable expansion for a chip supplier can coincide with substantial financial risks for the companies purchasing its technology.
This is one reason investors remain divided about whether the AI infrastructure cycle is sustainable.
Taiwan’s Semiconductor Industry Faces Both Opportunity and Risk
AMD’s expansion also has major implications for Taiwan, a central hub of advanced semiconductor manufacturing.
The company depends on a network of manufacturing and technology partners to produce sophisticated processors.
As AMD increases demand for advanced chips, manufacturers and packaging companies may benefit from higher production volumes.
But the same dependence creates potential bottlenecks.
WWC ONE MEDIA explored the market risks in Taiwan Stocks Sink Toward Correction Territory as Global AI Selloff Deepens — But Could TSMC Drag Asia Into a Bigger Market Rout?.
That report examined how semiconductor valuations had become sensitive to fears of excessive AI spending.
The broader industry faces two competing possibilities.
Continued expansion could support semiconductor manufacturing, exports and technology investment.
A sudden slowdown could affect suppliers that have already committed substantial capital to new production capacity.
For AMD, strong supply-chain partnerships will remain essential as it attempts to convert rising demand into revenue.
What AMD’s Record Earnings Mean for the Philippines
The global AI semiconductor expansion also has implications for the Philippine technology and electronics industries.
The Philippines participates in international semiconductor supply chains through electronics manufacturing, assembly, testing and related industrial services.
Growing demand for advanced computing hardware could create opportunities for companies operating in those sectors.
However, AMD’s earnings do not establish that the company has announced additional manufacturing investment or employment in the Philippines.
Any direct local economic impact would depend on specific supply-chain contracts, investment decisions and the capabilities of Philippine manufacturers.
The wider implications also extend to electricity infrastructure, data centers and digital services.
As more businesses deploy AI systems, demand may increase for computing facilities and supporting technology.
But capturing these opportunities will require reliable power, skilled workers, infrastructure development and competitive operating costs.
What Happens Next? Three Critical Tests for AMD
AMD’s strong earnings have raised expectations for the coming year.
The company now faces three major tests.
First, delivering its $17 billion fourth-quarter revenue forecast.
Investors will assess whether AMD can fulfill its outlook while maintaining profitability and managing supply constraints.
Second, executing its ambitious 2027 expansion.
Management expects revenue growth exceeding 80%, driven heavily by data center demand.
Reaching that target will require successful production increases and continued customer spending.
Third, competing effectively with Nvidia.
AMD must demonstrate that its processors, software and integrated Helios systems can provide compelling alternatives for major AI customers.
The company does not necessarily need to overtake Nvidia to achieve substantial growth.
But its valuation and future performance will depend partly on how much of the expanding AI infrastructure market it can capture.
The Bigger Picture: Can AMD Turn AI Momentum Into Lasting Market Power?
AMD’s third-quarter results demonstrate the extraordinary financial impact of the artificial intelligence revolution.
Revenue reached a record $13.38 billion.
Data center sales increased 97%.
Adjusted earnings per share climbed 74%.
And the company expects approximately $17 billion in fourth-quarter revenue, exceeding Wall Street’s expectations.
Lisa Su’s projection of more than 80% growth in 2027 suggests that AMD believes the current expansion is far from over.
Yet the risks are substantial.
Nvidia remains the dominant AI accelerator supplier.
Memory shortages threaten production capacity.
Consumer gaming demand remains weak.
And some investors are increasingly concerned about the financial sustainability of massive AI infrastructure investments.
The company’s latest results strengthen the argument that demand for AI computing remains exceptionally high.
But one record-breaking quarter cannot guarantee that the spending boom will continue indefinitely.
As AMD’s data center sales nearly double and Lisa Su prepares for another explosive year of growth, can the chipmaker transform itself into Nvidia’s most formidable competitor—or could a global memory shortage and a sudden slowdown in AI spending turn its biggest opportunity into its most dangerous test?