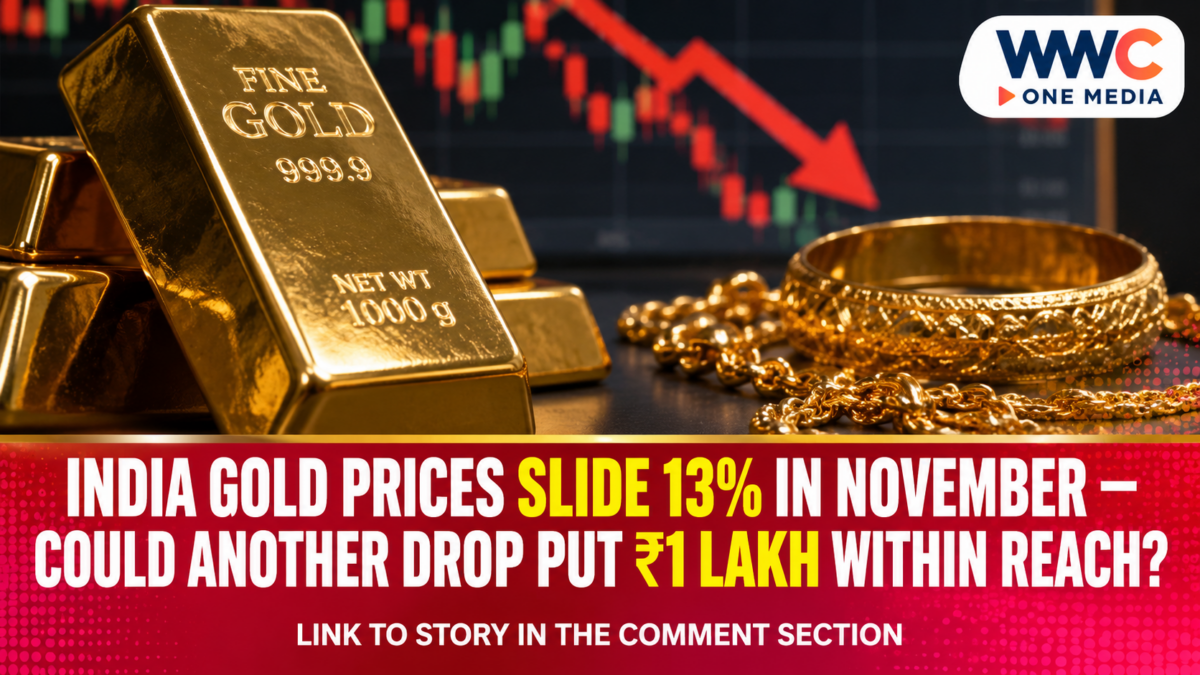
India’s gold market has entered a significant correction, with the India Bullion and Jewellers Association (IBJA) recording a 999-purity gold opening rate of ₹123,584 per 10 grams on November 20, 2026. The benchmark had stood at ₹142,420 on November 10, marking a decline of approximately 13.23% in just 10 calendar days.
The latest figures raise an important question for India’s jewellery industry, household buyers and investors: is the correction approaching a bottom, or could another round of selling push bullion closer to ₹100,000 per 10 grams?
The distinction matters because a lower market quotation does not automatically signal that prices will continue falling. Currency movements, international bullion demand, interest-rate expectations and investor positioning all influence the direction of gold.
For now, official market records establish the correction. They do not establish where the next bottom will be.
India Gold Prices: What the November Numbers Reveal
The latest IBJA daily market-rate document provides a useful picture of the speed of the adjustment.
On November 10, the association recorded 999-purity gold at ₹142,420 per 10 grams during the morning session. By November 13, the opening benchmark had declined to ₹135,884.
The downward movement continued during the following week.
On November 17, the opening rate was ₹134,418. It subsequently declined to ₹131,505 on November 18 and ₹129,985 on November 19.
By November 20, the recorded opening benchmark had reached ₹123,584.
That represents a reduction of ₹18,836 per 10 grams from the November 10 level.
The association also recorded a November 20 opening price of ₹113,203 for 916-purity gold, commonly associated with 22-karat jewellery.
These figures demonstrate that the adjustment extends beyond the pure-gold benchmark.
However, buyers should distinguish between benchmark bullion prices and actual jewellery quotations. Retail prices can include applicable taxes, making charges, retailer margins and other costs.
The IBJA figures are therefore reference prices, not guaranteed final checkout prices. Ibjarates+1
Why the Global Gold Market Is Under Pressure
India’s correction is part of a wider international movement.
The World Gold Council’s November 17 market update documented substantial weakness during October and the beginning of November.
International gold prices ended October at US$3,913 per ounce, representing a 6.3% monthly decline. By November 12, the benchmark had fallen further to US$3,870 per ounce.
The Council identified three important pressures: expectations of additional US Federal Reserve rate increases, a stronger US dollar and investor selling.
These factors can work together to weaken demand for bullion.
Gold does not generate interest payments. Consequently, when interest-bearing investments become more attractive, some investors may reconsider their exposure to precious metals.
A stronger dollar can create another challenge because international gold is commonly priced in US currency. When the dollar strengthens, gold can become more expensive for buyers using other currencies.
Currency movements also affect the domestic Indian quotation.
The World Gold Council reported that the Indian rupee strengthened by 1.7% between the end of October and November 12. It attributed part of the sharper domestic price decline to this currency movement.
This distinction is important: the international gold price and the Indian rupee-denominated price do not necessarily move by identical percentages. World Gold Council
Lower Prices Are Not Eliminating Gold Demand
A falling quotation does not mean that every category of gold buyer has disappeared from the market.
The World Gold Council’s November update described healthy Indian jewellery and bullion purchases during the Dhanteras and Diwali period.
Retailer feedback indicated that lower prices helped encourage buying across jewellery, bars and coins.
There was also evidence of consumers adjusting their purchasing behaviour.
Rather than necessarily buying larger quantities, some jewellery customers preferred lighter pieces. Smaller denominations of gold bars and coins also attracted interest.
This suggests that affordability and purchase size remain important considerations even when market prices are declining.
Investment demand presents another interesting picture.
Indian gold exchange-traded funds recorded their fifth consecutive month of positive net inflows in October.
The Council reported October inflows of ₹35 billion, equivalent to approximately US$364 million. Holdings increased by 2.2 tonnes to 126 tonnes.
It also estimated additional net inflows of ₹24.5 billion between November 1 and November 11.
These figures suggest that some financial investors continued adding gold exposure despite the market correction.
Nevertheless, ETF inflows should not be interpreted as proof that prices have already reached their lowest point. World Gold Council
Central Banks Continue to Provide an Important Demand Signal
Another important factor is the behaviour of central banks.
The World Gold Council’s third-quarter 2026 Gold Demand Trends report recorded 321.2 tonnes of central-bank and institutional gold demand during the quarter.
That was 42% higher than the corresponding period a year earlier.
Year-to-date purchases reached 675 tonnes, representing a 6% increase compared with the same period in 2025.
The report also recorded global gold-backed exchange-traded fund inflows of 211.2 tonnes during the third quarter.
However, the broader demand picture was mixed.
Global jewellery consumption declined 17% year-on-year to 312.9 tonnes during the quarter, while bar and coin demand declined 19% to 267.8 tonnes.
These figures demonstrate why gold prices cannot be explained by a single indicator.
Central-bank purchases and investment flows can provide underlying support, while weaker jewellery demand, higher interest rates and changing investor preferences can create downward pressure.
The Council’s assessment points to continued central-bank buying as an important source of demand, although future purchases remain uncertain. World Gold Council+1
Could Gold Actually Reach ₹100,000 Per 10 Grams?
The possibility deserves examination, but it should not be confused with a verified forecast.
Using the November 20 IBJA opening benchmark of ₹123,584, gold would need to decline another ₹23,584 per 10 grams to reach ₹100,000.
That represents an additional reduction of approximately 19.1%.
Such a movement would require further substantial weakness.
Potential contributing factors could include a stronger US dollar, higher real interest rates, continued liquidation of investment positions and weaker demand for physical bullion.
The opposite scenario is also possible.
A weaker dollar, renewed geopolitical uncertainty, stronger investment inflows or continued central-bank purchases could help stabilise prices.
The World Gold Council’s November assessment also highlights an important domestic factor: Indian prices are influenced by the relationship between international bullion values, currency movements and local market conditions.
Consequently, a forecast based exclusively on the international dollar quotation would be incomplete.
For additional context, WWC ONE MEDIA has previously examined how Federal Reserve expectations are affecting international gold demand, as well as the precious metal’s earlier decline below US$4,000.
Neither a return to previous highs nor a fall to ₹100,000 can be established from the available market records.
The responsible conclusion is that further volatility remains possible.
What the Correction Means for Jewellery Buyers and Investors
For households purchasing jewellery, declining bullion quotations may eventually improve affordability.
However, the actual savings depend on the purity, weight, making charges, applicable taxes and the retailer’s selling price.
Consumers should compare final quotations rather than relying exclusively on headlines announcing lower gold rates.
For investors, the correction highlights the importance of distinguishing between short-term price movements and longer-term portfolio considerations.
Gold can experience substantial declines even when central banks continue purchasing the metal.
It can also recover during periods when market sentiment improves, sometimes before broader economic conditions become clearer.
WWC ONE MEDIA’s earlier examination of gold’s international price reversal provides additional context for understanding how monetary policy and geopolitical developments can affect bullion.
No particular purchase price should be treated as a guaranteed bargain.
For businesses in India’s jewellery sector, the adjustment also creates a balancing challenge: lower metal costs can attract customers, but rapidly changing prices make inventory management and pricing decisions more difficult.
What Happens Next
The next phase of India’s gold market will depend on several developments.
First, investors will watch US monetary-policy signals and the movement of the dollar.
Second, domestic market participants will monitor fresh IBJA benchmarks and international bullion prices.
Third, investment flows, jewellery demand and central-bank purchasing will help determine whether the correction stabilises or continues.
The November 20 opening benchmark provides a clear indication of how far prices have retreated.
But the ₹100,000 level remains a hypothetical scenario rather than an established destination.
For now, the most defensible assessment is that India’s gold market is undergoing a substantial correction while important sources of underlying demand remain active.
The next market direction will need to be established by actual trading data, not by predictions based on previous price highs.