MANILA, PHILIPPINES — November 10, 2026 — GCash has delivered a powerful response to investors who questioned whether the Philippines’ biggest digital finance platform had already reached its growth ceiling.
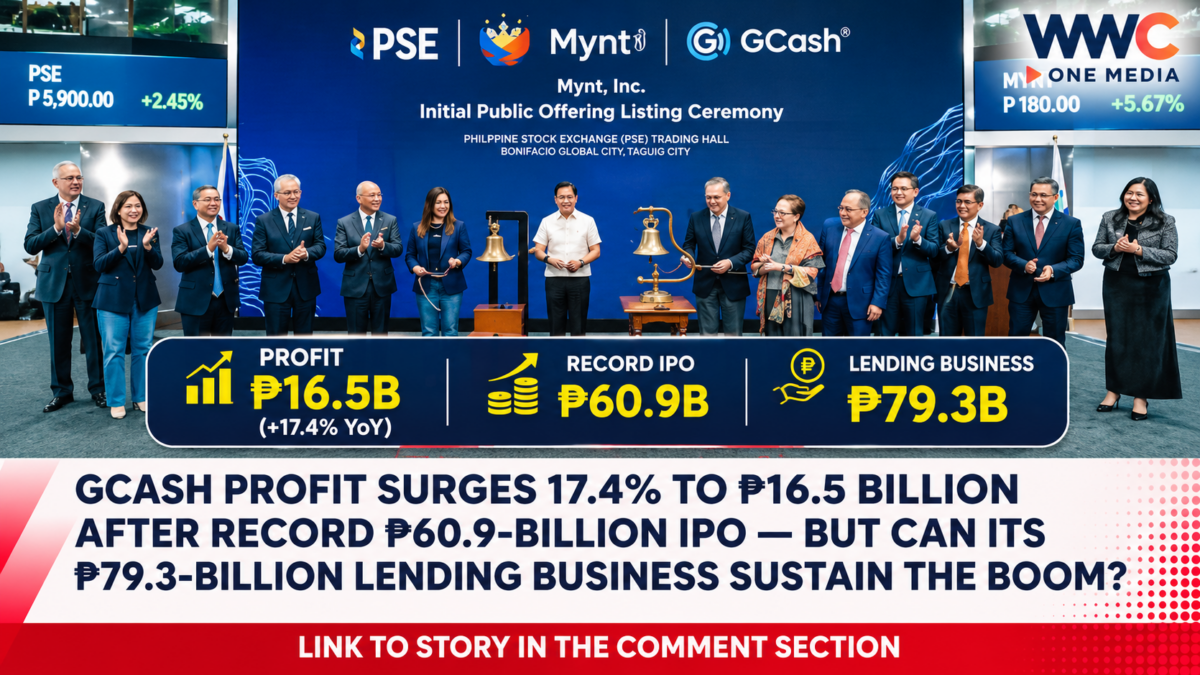
Just weeks after its historic stock-market debut, GCash parent Mynt Inc. reported ₱16.5 billion in net income for the first nine months of 2026, a 17.4% increase from a year earlier.
The results suggest that the financial technology company is finding new opportunities to expand beyond its massive mobile-wallet user base.
Adjusted revenue climbed 12.2% to ₱67.1 billion, while payment transactions processed through the platform reached an extraordinary ₱15.1 trillion.
The company also reported 42.1 million monthly active users, reinforcing its position as one of the most widely used financial platforms in the Philippines.
But perhaps the biggest surprise came from lending.
Mynt’s loan portfolio surged 43.3% to ₱79.3 billion, as the company continued expanding access to digital credit for millions of Filipinos.
The figures were released on November 9, shortly after Mynt completed the Philippines’ largest initial public offering, which raised approximately ₱60.9 billion including the overallotment.
According to InsiderPH, the earnings report challenges concerns that GCash’s enormous scale had left little room for further growth.
Yet the strong performance brings a different challenge.
With lending expanding rapidly, competition intensifying and stock-market investors demanding sustained profitability, can GCash maintain its momentum—or will rising credit risks and regulatory pressures become the next major test?
GCash Reports ₱16.5 Billion in Profit as Earnings Growth Accelerates
Mynt’s latest financial results show that profitability accelerated during the third quarter.
Net income increased 17.4% year on year to ₱16.5 billion during January–September 2026.
That compares with just 7.3% profit growth during the first six months of the year.
The improvement is significant because it suggests that GCash’s earnings momentum strengthened despite concerns about the company’s maturity and the increasing competitiveness of digital financial services.
Revenue growth accelerated as well.
Adjusted revenue increased 12.2% to ₱67.1 billion during the nine-month period, compared with 9.8% growth during the first half, according to Mynt’s official announcement.
Third-quarter adjusted revenue alone reached ₱24 billion, a 16.6% increase from the same quarter last year.
The company said both quarterly revenue and net income reached record levels.
However, Mynt did not separately disclose an exact third-quarter net income figure in its November 9 press release.
The latest results therefore establish stronger year-on-year profitability, but they do not provide a complete assessment of how every underlying business line contributed to earnings.
Why Investors Thought GCash Was Running Out of Room to Grow
GCash has already achieved enormous adoption across the Philippines.
Its digital wallet is widely used for transferring money, purchasing mobile load, settling bills and paying merchants.
The platform also offers access to loans, savings, investments and insurance products.
Such widespread adoption led some investors to question whether further customer growth would become increasingly difficult.
As a financial platform matures, acquiring new users can become more expensive.
Existing customers may also become more sensitive to transaction charges.
Banks, digital wallets and other financial technology providers continue competing for the same customers.
InsiderPH reported that questions about GCash’s remaining growth potential intensified ahead of its IPO.
The latest earnings offer an important response.
Although GCash is already operating at substantial scale, more people are using its services and existing customers are transacting more frequently.
But customer growth is only one part of the company’s strategy.
Mynt is increasingly focused on generating more value from the financial relationships it has already established.
GCash Now Has 42.1 Million Monthly Active Users
The company’s monthly active user base reached 42.1 million during the third quarter of 2026.
That represents a 9.7% increase from the same period last year.
The figure is particularly important because it measures active use rather than merely counting all accounts ever created.
A registered account does not necessarily represent a person who uses the platform regularly.
Monthly active users provide a more meaningful indication of ongoing customer engagement.
Mynt also reported that average daily transactions reached 64.4 million during the first nine months, increasing 16% from a year earlier.
That growth suggests the platform is becoming more deeply integrated into everyday financial activity.
Customers may use GCash for multiple purposes, from paying household bills to transferring money and purchasing goods.
The more frequently customers use a financial platform, the greater the opportunities to offer related services.
However, higher transaction activity does not automatically translate into proportional revenue growth.
Different transactions generate different fees, and some services carry little or no direct charge.
₱15.1 Trillion in Payments Shows the Scale of GCash
One of the largest numbers in Mynt’s report is the gross transaction value generated by its Payment Solutions business.
For January–September 2026, the figure reached ₱15.1 trillion, an increase of 23.1% from a year earlier.
This demonstrates the enormous amount of payment activity flowing through GCash-related services.
But there is an important accounting distinction.
₱15.1 trillion is not GCash revenue or profit.
It represents the gross value of payments processed through the relevant business.
Mynt earns revenue from selected fees and services associated with those transactions.
For example, a ₱1,000 payment processed through a digital wallet does not mean the wallet operator earns ₱1,000.
The company’s actual revenue depends on the applicable commercial arrangements and charges.
The growing payment value nevertheless provides evidence that GCash remains an important participant in the Philippine digital economy.
It may also support opportunities in merchant services, lending and other financial products.
Lending Becomes GCash’s Next Major Growth Engine
While payments remain central to GCash, the company’s CreditTech business is becoming increasingly important.
As of September 30, Mynt reported 7.8 million active borrowers.
Its total loan portfolio reached ₱79.3 billion, an increase of 43.3% from a year earlier.
The expansion reflects greater use of digital credit products.
GCash offers access to services including GCredit, GLoan and GGives through its financial technology ecosystem.
Its lending business operates through entities including Fuse Financing.
For consumers, digital credit can provide an alternative to traditional lending channels.
Some customers may be able to apply without visiting a physical bank branch.
The platform may also use permitted transaction and customer information to support credit assessments.
For small businesses and individuals with limited conventional credit histories, this can create additional financing opportunities.
However, digital lending must remain responsible.
Borrowers still need to understand interest rates, fees, repayment schedules and the consequences of missed payments.
Rapid loan growth is attractive to investors only if the company can continue managing credit risk effectively.
The 4.8% Bad-Loan Ratio Is Now a Critical Number
The expansion of GCash’s lending portfolio brings increased attention to loan quality.
Mynt reported a 4.8% nonperforming loan ratio at the end of September.
The ratio was broadly unchanged from the previous quarter.
That indicates relative stability over the reported period despite the growth in the loan portfolio.
But it does not mean credit risk has disappeared.
A nonperforming loan generally involves a borrower failing to meet the applicable repayment requirements.
A rising nonperforming loan ratio can signal that more borrowers are struggling to repay.
For a company expanding digital lending, this metric is especially important.
If the loan book grows rapidly while credit performance deteriorates, future earnings could come under pressure through higher expected credit losses and collection costs.
Mynt’s latest figures provide evidence that the reported ratio remained stable in the third quarter.
The next challenge is maintaining acceptable loan quality as more customers borrow.
GCash’s ₱60.9-Billion IPO Raised Expectations
The strong earnings arrived shortly after Mynt made Philippine stock-market history.
On October 20, 2026, the company debuted on the Philippine Stock Exchange under the ticker GCASH.
Its shares were offered at ₱6.60 apiece.
The IPO raised approximately ₱60.9 billion including the overallotment, making it the country’s largest public offering.
The transaction valued the company at approximately ₱442 billion, or around US$7 billion, at the offering price.
It also attracted major domestic and international institutional investors.
Reuters reported that the stock closed at its IPO price of ₱6.60 on its first trading day after briefly trading higher.
The listing established GCash as one of the Philippines’ most valuable publicly traded companies.
But going public also changes expectations.
Investors now have regular opportunities to evaluate earnings, cash generation, loan quality and management decisions.
As previously reported by WWC ONE MEDIA, the historic offering attracted international investors and created a new test for the Philippine financial technology sector.
Related WWC ONE MEDIA coverage: GCash’s Record ₱60.9-Billion IPO Draws BlackRock, Citadel and Global Investors — But the Real Test for Philippine Tech Begins Now
The latest earnings give investors their first major set of operating results since the listing.
However, the nine-month numbers describe operations before the October IPO, not performance generated by its new public-market capital.
Ernest Cu Says GCash’s Biggest Opportunity Is Still in the Philippines
Globe Telecom President and CEO Ernest Cu, who also chairs Mynt, has previously emphasized the importance of GCash remaining focused on the Philippine market.
Speaking at a Kaya Founders gathering in November, Cu argued that expanding into additional countries does not automatically create a stronger company.
GCash built its business by addressing financial needs in a market it understands.
The platform benefits from local distribution, customer familiarity and extensive adoption.
That strategy can provide opportunities to deepen existing customer relationships without immediately taking on the costs of operating across several international markets.
As WWC ONE MEDIA previously reported, Cu described the company’s development from a mobile-money service into a multibillion-dollar financial platform.
Related WWC ONE MEDIA coverage: GCash Hits $7-Billion Valuation After Record ₱60.9-Billion IPO — But Ernest Cu Says Its Biggest Opportunity Is Still in the Philippines
The latest earnings support the argument that significant opportunities remain within the domestic market.
But maintaining that growth will require continued innovation, reliable service and strong risk management.
Digital Investing Could Create Another Revenue Opportunity
GCash is also expanding the range of financial services available through its app.
GStocks PH allows eligible customers to access stock-market investment services through a participating brokerage.
The platform was used to distribute Mynt IPO shares to retail investors.
That arrangement helped bring the historic offering closer to customers who already use GCash for everyday financial transactions.
As WWC ONE MEDIA previously reported, eligible users were able to subscribe to Mynt shares through GStocks PH at ₱6.60 each during the offering period.
Related WWC ONE MEDIA coverage: Mynt IPO Opens to Retail Investors Through GStocks PH at ₱6.60 Per Share
The development illustrates how GCash is moving beyond digital payments toward broader financial participation.
However, investment services involve market risk.
Customers can lose money when share prices decline, and investment products are not equivalent to insured bank deposits.
The platform’s ability to expand financial access will depend partly on whether users understand these differences.
GCash Is Also Expanding Everyday Digital Payment Services
Growth does not depend exclusively on introducing new lending and investment products.
GCash continues developing services designed to make ordinary payments more convenient.
One example is GSukli, a feature that allows shoppers at participating merchants to receive small amounts of cash change directly into their digital wallets.
The initiative is intended to connect traditional cash transactions with digital financial services.
As previously covered by WWC ONE MEDIA, the feature allows qualifying amounts of change of up to ₱199.99 to be transferred to a customer’s GCash wallet without a separate GSukli service fee.
Related WWC ONE MEDIA coverage: GCash Is Turning Your Loose Change Into Digital Money — But One GSukli Limit Could Catch Shoppers Off Guard
Services like this may encourage more frequent use of digital wallets.
But their financial impact depends on actual adoption, merchant participation and the company’s cost structure.
The announcement of a new feature does not automatically mean it will generate substantial additional earnings.
Regulation and Lower Transaction Fees Remain Risks
GCash’s earnings outlook is also affected by regulatory developments.
The Bangko Sentral ng Pilipinas has introduced measures intended to improve digital financial services and consumer protection.
Some regulations can reduce transaction costs for customers while placing pressure on the fees collected by providers.
Earlier this year, Mynt disclosed that lower bank-transfer charges and restrictions affecting certain payment activities were among the factors influencing profitability.
GCash reduced its transfer charge for certain bank transfers from ₱15 to ₱10 in July.
Lower fees may help make transactions more affordable and encourage customer activity.
But they can also reduce revenue per transaction.
A growing digital-finance company must therefore manage the tradeoff between transaction volume and the amount it earns from each activity.
Regulatory compliance, cybersecurity investment and customer protection also create ongoing operating costs.
These pressures are important as Mynt expands its product portfolio.
Fourth-Quarter Earnings Face a Major Test
Mynt’s nine-month results are encouraging, but they do not guarantee similarly strong full-year performance.
The company has warned that most one-time expenses related to its IPO are expected to be recognized in the fourth quarter.
Seasonally higher operating costs may also affect results.
These expenses were not fully reflected in the January–September performance.
Consequently, investors should not simply annualize the ₱16.5-billion nine-month profit and assume that the fourth quarter will follow the same pattern.
The next earnings report will provide a more complete picture of the company’s first year as a publicly traded business.
Analysts will also be examining whether the improvement in payment activity continues.
Lending performance will be particularly important.
With a loan portfolio approaching ₱80 billion, even relatively small changes in credit quality may affect future earnings.
Mynt’s Earnings Release Is Only the First Test
The company’s November 9 announcement gives investors an initial view of how the business performed before the October listing.
A formal analysts’ briefing on the nine-month results was scheduled for November 10 at 4 p.m., according to its Philippine Stock Exchange filing.
That session may provide additional details on management’s outlook and financial performance.
But as of this article’s preparation, statements that might be made at that scheduled briefing should not be treated as already delivered.
The key questions remain straightforward.
Will monthly active users continue increasing?
Can GCash maintain transaction growth while digital payment fees face pressure?
Will lending remain profitable as the loan portfolio expands?
And can management control operating expenses while investing in security, technology and new financial products?
The answers will help determine whether the company’s strong nine-month results represent sustained momentum.
The Bigger Picture: Can GCash Grow Beyond Its Digital Wallet Success?
GCash has entered a new stage of its development.
It is no longer simply a fast-growing digital wallet trying to attract more users.
It is a publicly traded financial technology company with millions of active customers, trillions of pesos in annual payment activity and an expanding lending business.
Its first major earnings announcement since listing delivered several encouraging signals.
Profit increased 17.4%.
Adjusted revenue reached ₱67.1 billion.
Monthly active users climbed to 42.1 million.
And the loan portfolio expanded 43.3% to ₱79.3 billion.
Those figures challenge the argument that GCash has exhausted its growth opportunities.
But they also reveal how the business is changing.
Future earnings may depend increasingly on lending, financial services and deeper customer engagement rather than simply adding new wallet accounts.
That shift creates opportunities, but it also introduces risks involving credit quality, regulation and operating expenses.
The biggest question is not whether millions of Filipinos will continue using GCash. It is how effectively Mynt can convert that activity into sustainable, responsible and profitable financial services.
And as GCash celebrates ₱16.5 billion in nine-month earnings following the Philippines’ largest IPO, one question now defines its next chapter: Can the company’s expanding lending business power another record year—or will rising financial risks test the very growth story that investors have placed billions of pesos behind?