TOKYO / SINGAPORE — October 30, 2026. The Japanese yen strengthened on Friday after the Bank of Japan delivered a historic shift in its inflation assessment, giving currency traders fresh reason to expect another interest-rate increase before the end of the year.
Although the central bank left its benchmark borrowing rate unchanged at 1.25%, its latest economic outlook stated that underlying inflation had reached a level broadly consistent with the country’s 2% price-stability target.
The declaration marks an important turning point after nearly 14 years of efforts to establish sustainable inflation through aggressive monetary stimulus.
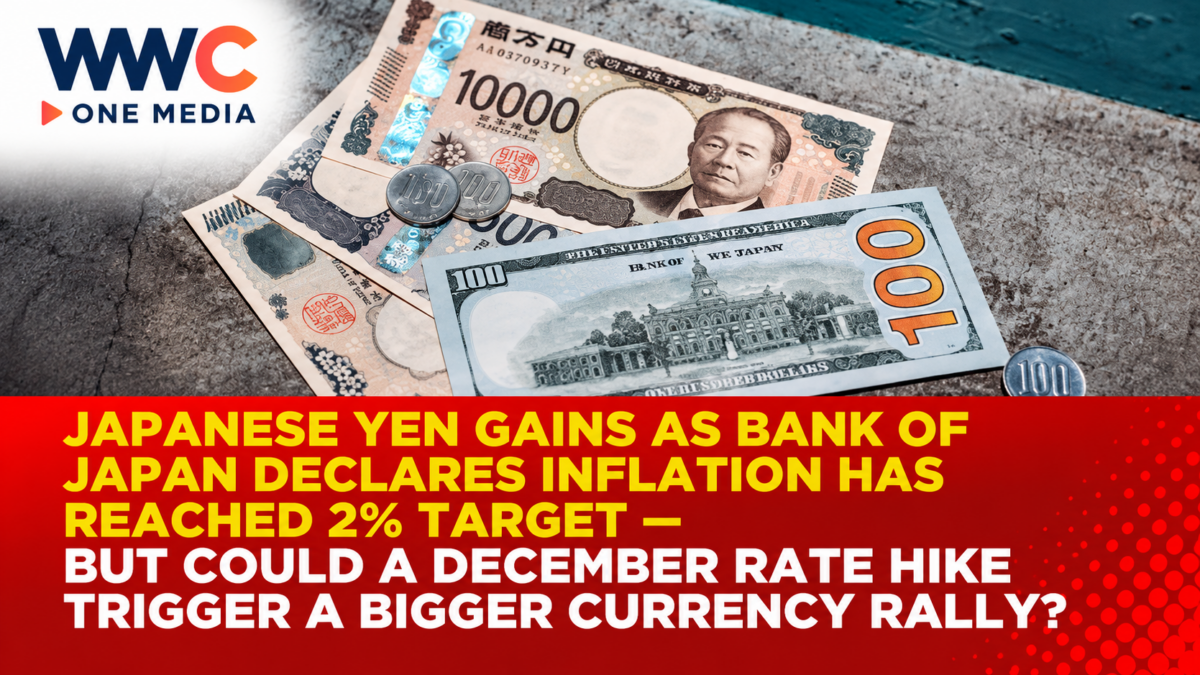
The yen appreciated to approximately 157.115 per US dollar in Friday’s trading, according to Reuters, recovering most of its losses for October.
The currency also benefited from declining US Treasury yields and a broad retreat from riskier financial assets as international technology shares fell.
But the more important development may lie ahead.
With investors increasingly expecting another Bank of Japan rate increase in December, could Japan’s long-awaited monetary-policy normalization trigger a sustained yen rally—or will global market volatility prevent the currency from holding its gains?
Bank of Japan holds rates at 1.25% but delivers a hawkish message
At the conclusion of its October 29–30 monetary-policy meeting, the Bank of Japan decided to maintain its short-term interest-rate target at 1.25%.
The decision passed by an 8–1 vote.
Board member Hajime Takata dissented, favoring an immediate 25-basis-point increase that would have raised the policy rate to 1.50%.
The decision to hold was widely expected.
Japan had already raised its benchmark interest rate in September, and officials wanted more time to assess the impact of previous increases.
Yet the accompanying economic outlook sent a more important signal.
For the first time in the current normalization cycle, the central bank assessed underlying inflation as having broadly reached its long-standing 2% target.
That assessment strengthens the case for additional monetary tightening.
The BOJ reiterated that it could continue raising interest rates if economic and inflation developments unfold in line with its projections.
However, it did not announce a December increase or commit to a fixed timetable.
Why Japan’s 2% inflation milestone is historic
Japan spent decades struggling with extremely low inflation and recurring deflationary pressure.
When prices stagnate or decline over long periods, businesses may hesitate to invest, while households can become reluctant to spend.
Those conditions can weaken economic growth and wage increases.
In 2013, the Bank of Japan adopted an ambitious monetary-easing campaign intended to lift inflation sustainably toward 2%.
The program involved extraordinary asset purchases and very low interest rates.
More recently, stronger wages, higher import costs and changing business pricing behavior have transformed the inflation outlook.
The latest assessment suggests that Japan is no longer primarily struggling to generate enough inflation.
Instead, policymakers are increasingly concerned about preventing prices from rising too rapidly.
This change has major implications for interest rates and the yen.
Underlying inflation is not the same as headline CPI
The BOJ’s announcement requires an important distinction.
Its assessment concerns underlying inflation, which attempts to identify more persistent price movements after accounting for temporary influences.
That is not identical to the latest headline consumer price index.
Official Japanese data showed that core CPI, excluding fresh food, rose 2.1% year on year in September.
A separate measure excluding both fresh food and energy increased 2.4%.
Those figures already indicated broader price pressures.
The BOJ’s October statement goes further by recognizing that the economy’s underlying inflation trend has become broadly consistent with its target.
But reaching the target does not mean inflation has become permanently stable.
The bank warned that price pressures could exceed its objective if energy costs, wages or business demand continue rising.
That risk is influencing expectations for further rate increases.
The yen strengthens to around 157 per dollar
The currency market responded positively to the BOJ’s message.
Reuters reported that the yen strengthened to a session high of around ¥157.115 against the US dollar.
The quotation means one US dollar could be exchanged for approximately 157.115 yen.
A decline in the USD/JPY exchange rate therefore indicates that the Japanese currency is strengthening.
The yen’s appreciation was supported by expectations of additional Japanese rate increases.
Higher domestic interest rates can make yen-denominated investments more attractive relative to assets in other currencies.
But Japan’s policy decision was not the only factor.
Global technology-stock weakness encouraged investors to reduce exposure to riskier assets.
At the same time, US Treasury yields declined, weighing on the dollar.
The yen consequently benefited from both Japan-specific policy developments and broader international market conditions.
Currency strategists see a more hawkish Bank of Japan
Analysts generally interpreted the inflation assessment as a meaningful shift.
Masahiko Loo, chief fixed-income strategist at State Street Investment Management, characterized the decision as a routine pause accompanied by a more hawkish direction.
His analysis suggested that the BOJ could continue normalizing policy while remaining sensitive to global financial conditions.
Tohru Sasaki, chief strategist at Fukuoka Financial Group and a former BOJ official, highlighted the significance of the central bank’s upgraded inflation assessment.
However, he also noted that falling global equities and tighter financial conditions reduced the immediate pressure for another Japanese rate increase.
The contrast is important.
The inflation statement strengthens the case for future tightening.
But the central bank may still decide to wait if markets become unstable or economic conditions weaken.
Currency strategists therefore see potential support for the yen without assuming that a sustained rally is guaranteed.
December is emerging as the next major market test
Financial markets are increasingly focused on the BOJ’s December meeting.
Before the October decision, a Bloomberg survey indicated that more than 80% of economists expected another interest-rate increase in December.
Such a move would likely take the policy rate from 1.25% to 1.50%.
But that remains an expectation, not an official policy decision.
The central bank will examine inflation, wages, economic growth and financial-market conditions before determining its next step.
WWC ONE MEDIA previously analyzed the outlook in Japan Inflation Hits 2.1% as BOJ Eyes December Rate Hike.
That report explored how September’s inflation figures increased pressure on policymakers to consider further tightening.
The October 30 decision reinforces the possibility of another increase.
Nevertheless, investors should avoid confusing a widely anticipated outcome with a guaranteed one.
Higher inflation forecasts reinforce the case for tighter policy
The Bank of Japan also revised some of its economic projections.
Its median forecast for core consumer inflation in fiscal 2027, ending March 2028, increased to 2.6% from 2.4%.
The bank retained its fiscal 2026 core inflation forecast at 2.5%.
It also expects inflation to ease toward 2% in the following fiscal year.
These projections suggest that officials are concerned about inflation remaining above their preferred level for longer than previously anticipated.
The BOJ slightly upgraded its fiscal 2026 economic-growth outlook to 0.7%.
That combination—continued economic growth and inflation above target—may provide policymakers with room to increase borrowing costs.
But growth projections remain relatively modest.
If the economy weakens unexpectedly, the central bank could choose a slower tightening path.
Japan’s wage growth is changing the inflation debate
Wages are increasingly important to Japan’s monetary-policy outlook.
For many years, weak salary growth made it difficult for businesses to raise prices sustainably.
That pattern has begun to change.
Government figures released earlier in October showed that inflation-adjusted wages increased 1.5% in August compared with a year earlier.
It marked the eighth consecutive month of real wage growth.
Nominal pay rose 3.8% over the same period.
The improvement could support household spending and make inflation more sustainable.
WWC ONE MEDIA examined the transition in Japan’s Inflation Enters a New Era as Wages Rise and Interest Rates Hit 31-Year High.
The report discussed how rising wages could help Japan move beyond decades of deflation.
However, stronger wages may also contribute to additional price increases if companies pass higher labor costs on to customers.
The BOJ must therefore balance improving household purchasing power against the risk of persistent inflation.
The Iran war is complicating Japan’s inflation outlook
Japan imports much of the energy it consumes.
That makes global oil prices particularly important for domestic inflation.
The continuing conflict involving Iran has disrupted oil shipments and increased transportation and energy costs.
Higher crude prices can raise the cost of electricity, manufacturing, transport and imported goods.
The problem becomes more severe when the yen weakens.
Because oil is generally priced internationally in dollars, a weaker Japanese currency increases the local-currency cost of imported petroleum, all else being equal.
The BOJ has identified the Middle East energy shock as one of the risks that could keep inflation elevated.
Its latest policy outlook therefore reflects more than domestic wage growth.
External supply shocks are also affecting how quickly policymakers may need to tighten.
The AI boom is adding another source of price pressure
Artificial intelligence has become an unexpected part of Japan’s monetary-policy debate.
Global demand for AI-related technology is supporting Japanese manufacturers of industrial equipment, electronic components and semiconductor-related products.
That can strengthen exports and business investment.
But rapid investment can also create pressure on prices when production capacity, specialized equipment or skilled labor is constrained.
Bank of Japan officials have identified AI-related demand as one factor affecting the economic outlook.
WWC ONE MEDIA reported on the issue in Japan’s Central Bank Signals More Rate Hikes After 31-Year High — But an AI-Driven Inflation Shock Could Change Everything.
The article examined how the global AI investment cycle could support Japan’s economy while complicating inflation control.
However, AI demand is only one influence among several.
It would be inaccurate to describe the current inflation environment as being caused entirely by artificial intelligence.
Why the yen carry trade matters to global markets
Japan’s relatively low interest rates have supported a major international investment strategy known as the yen carry trade.
Investors borrow in yen, convert the proceeds into other currencies and invest in assets offering potentially higher returns.
The strategy can be profitable when borrowing costs remain low and exchange rates move favorably.
But higher Japanese interest rates reduce the advantage of borrowing in yen.
A strengthening yen can also increase the cost of repaying those loans.
If many investors close positions at the same time, they may need to sell foreign assets and buy back yen.
That process can amplify currency and stock-market volatility.
WWC ONE MEDIA previously examined the risk in BOJ Warns Japan Could Face Rapid Rate Hikes if Inflation Surges — But One Number Shows Why the Risk Is Growing.
Reuters had reported approximately 360 trillion yen in cross-border yen borrowing by March 2026.
That is a broad measure of lending exposure, not a confirmed total of speculative carry-trade positions.
It should not be portrayed as money that will necessarily be withdrawn from global markets.
Global stock-market weakness is supporting the yen
The BOJ’s decision coincided with a sharp decline in global technology shares.
Investors have become more concerned about whether enormous spending on AI data centers and computing infrastructure will generate sufficient profits.
Reuters reported significant selling in Asian technology stocks on October 30.
Japanese and South Korean equities weakened while investors sought safer assets.
US Treasury yields also declined as bond prices rose.
Such conditions can support the yen because the currency has historically attracted demand during periods of global financial stress.
However, the relationship is not automatic.
The yen can weaken during some crises, depending on liquidity conditions and the relative performance of other currencies.
For October 30, the available evidence suggests both the BOJ’s hawkish outlook and broader risk aversion contributed to the currency’s gains.
Bank of Japan accelerates sales of ETF holdings
The central bank also announced changes to its program for selling exchange-traded fund holdings.
Beginning in January, the BOJ plans to increase the annual pace of ETF sales to approximately 860 billion yen, measured by book value.
The previous pace was around 330 billion yen annually.
The change reflects the bank’s effort to unwind investments accumulated during years of extraordinary monetary easing.
However, analysts expect the immediate market impact to be limited.
The unwinding process remains gradual and could take decades at the announced pace.
The ETF decision should therefore be understood as another step toward normalization, not an immediate liquidation of all central-bank equity holdings.
For stock markets, the impact will depend on the execution of sales and prevailing investor demand.
Why a stronger yen is not always good for Japan
A stronger yen can help reduce the cost of imported energy, food and raw materials.
That may ease some pressure on households and businesses.
However, it can also create challenges for exporters.
Japanese companies selling products overseas may receive fewer yen when foreign-currency revenue is converted back into domestic currency.
Exporters can partially offset this through currency hedging, overseas production and pricing adjustments.
Tourism businesses may also face changing demand if Japan becomes more expensive for international visitors.
The effects therefore vary across industries.
A stronger currency can improve purchasing power while placing pressure on some export-oriented businesses.
The BOJ’s challenge is to keep inflation stable without causing excessive disruption to growth.
What does this mean for the Philippines?
Japan is an important trading partner, investor and source of tourism for the Philippines.
Currency changes can influence the cost of travel, imported goods and financial transactions between the two countries.
A stronger yen generally makes yen-denominated expenses more costly when measured in pesos, assuming the peso’s value relative to other currencies remains unchanged.
That can affect Filipino travelers and businesses purchasing Japanese products.
Conversely, peso-denominated transfers from Japan can rise in value if the yen strengthens against the Philippine currency.
However, the USD/JPY exchange rate alone does not determine the peso-yen rate.
Movements in the Philippine peso against the US dollar also matter.
Further BOJ tightening may affect regional capital flows, but no specific Philippine interest-rate change follows automatically from Japan’s decision.
Could the Bank of Japan move toward 2% interest rates?
Some financial strategists believe Japan’s eventual policy rate could reach approximately 1.75% or higher.
State Street’s Masahiko Loo has cited an expected terminal rate near 1.75%.
Other analysts have discussed scenarios approaching 2%, depending on inflation and economic activity.
These are projections rather than established BOJ targets.
The central bank has not committed to a final interest-rate ceiling.
If inflation proves more persistent than expected, officials may consider additional tightening.
But if economic growth weakens or global markets experience severe instability, the pace could slow.
That uncertainty means the yen’s future direction is likely to remain sensitive to every new inflation report, wage figure and central-bank statement.
What currency investors should watch next
The immediate focus will be Governor Kazuo Ueda’s explanation of the decision and the central bank’s assessment of financial conditions.
Market participants will also monitor the BOJ’s December meeting.
Additional inflation reports and wage data could strengthen or weaken the argument for another increase.
US Federal Reserve policy will also influence the yen.
If American interest rates remain high relative to Japan’s, the interest-rate gap may continue supporting the dollar.
Conversely, narrowing differences could make yen-denominated assets more attractive.
Oil prices and global financial-market sentiment will be important additional factors.
The yen could strengthen further, but no particular exchange-rate target is guaranteed.
The bigger question: Is Japan entering a new monetary era?
Japan’s October 30 decision represents more than another routine interest-rate announcement.
The BOJ has formally recognized that underlying inflation is broadly consistent with its long-standing target.
That marks an important change for an economy that spent decades struggling against weak prices and sluggish wage growth.
The central bank is now focused on managing the risks of inflation becoming too persistent.
Currency strategists believe the more hawkish stance can support the yen.
But the market will ultimately judge the policy through actual rate decisions, economic data and Japan’s ability to sustain growth.
The yen has strengthened as the Bank of Japan signals that its long battle to achieve 2% inflation has reached a turning point. But with another rate increase possible in December and global markets already under pressure, the decisive question is whether Japan can normalize monetary policy without triggering a disruptive currency surge or a broader financial-market shakeout.