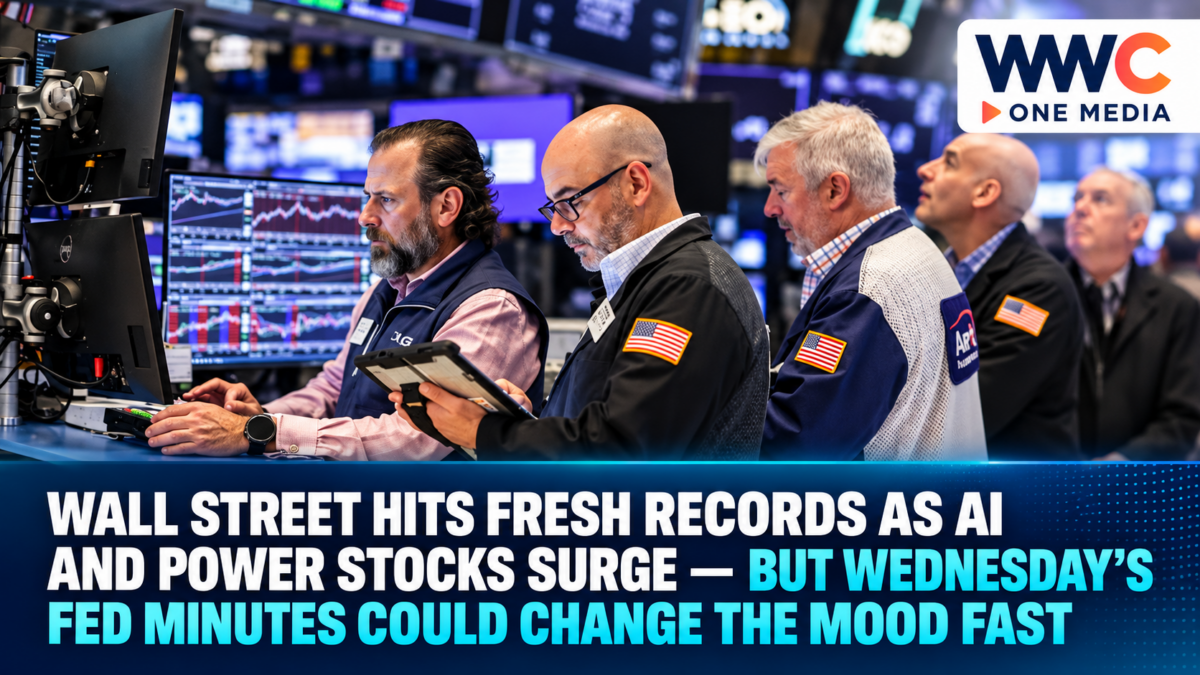
NEW YORK — Wall Street is heading into Wednesday from record territory, but investors may have little time to celebrate.
The S&P 500 and Nasdaq Composite both closed at fresh all-time highs Tuesday, October 6, as enthusiasm over artificial intelligence, data-center spending and corporate profits overpowered concerns about $100 oil, historically high Treasury yields and another potentially hawkish Federal Reserve signal.
The S&P 500 rose 0.6% to 7,818.93, its first close above 7,800.
The Nasdaq advanced about 0.4% to 27,599.79, posting its second consecutive record close.
The Dow Jones Industrial Average gained around 0.5% to 51,521.28.
But Wednesday could quickly test whether Wall Street’s latest record run has enough strength to continue.
Investors will be watching the Federal Reserve, AI-related power stocks, software companies and another round of corporate earnings for clues about whether the rally can broaden — or whether the market remains dependent on a small group of high-flying technology names.
Constellation Energy Becomes One of Wall Street’s Biggest AI Winners
One of Tuesday’s biggest stories wasn’t a semiconductor company.
It was a nuclear-power producer.
Constellation Energy surged roughly 15% after Alphabet’s Google agreed to purchase power from the company under a long-term agreement tied to growing electricity demand.
The deal involves approximately 890 megawatts of nuclear power, highlighting one of Wall Street’s newest AI investment themes:
Artificial intelligence needs enormous amounts of electricity.
For years, investors primarily expressed their AI enthusiasm by buying Nvidia and other semiconductor stocks.
That trade is now spreading.
Utilities, nuclear operators, electrical-equipment companies and data-center infrastructure providers are increasingly being viewed as indirect winners from the hundreds of billions of dollars being poured into artificial-intelligence computing.
Constellation’s rally shows how dramatically that investment thesis has expanded.
AI is no longer only a chip story.
It is becoming a power-generation story.
Vistra Joins the Power Rally
Constellation was not alone.
Vistra jumped roughly 12% after reports that it secured around $4.2 billion in federal financing, adding momentum to a broader rally in power producers linked to surging U.S. electricity demand.
The connection to artificial intelligence is straightforward.
Hyperscale data centers operated by companies including Google, Microsoft, Amazon and Meta require enormous, continuous supplies of electricity.
That demand has revived investor interest in nuclear energy and other reliable power-generation sources.
The market is effectively betting that the next stage of the AI boom will require not only more processors — but more power plants, transmission infrastructure and electricity contracts.
Marvell Surges as AI Ambitions Get Much Bigger
Marvell Technology rose roughly 5% Tuesday after laying out an ambitious long-term revenue target of approximately $70 billion to $90 billion by fiscal 2031.
Investors interpreted the forecast as another sign that demand for networking and custom AI chips could remain enormous for years.
Marvell has become one of the semiconductor industry’s major beneficiaries of spending on AI networking infrastructure.
Its technology helps move massive amounts of data between processors and servers inside data centers.
That role becomes increasingly important as AI clusters grow larger.
The company’s optimism adds another layer to the market’s biggest investment debate:
Is AI capital spending approaching a peak — or is the industry still near the beginning of a multiyear infrastructure cycle?
Wall Street is currently betting heavily on the second scenario.
AMD Climbs as Meta AI Expectations Grow
Advanced Micro Devices also joined Tuesday’s AI rally.
AMD gained nearly 4% after Citi raised its price target on the chipmaker, citing stronger expectations for AI demand, including potential business connected to Meta’s expanding infrastructure investments.
AMD has spent years attempting to reduce Nvidia’s overwhelming lead in the AI accelerator market.
Any evidence that large cloud companies are willing to diversify their chip suppliers could therefore become an important catalyst for AMD shares.
But the gap remains substantial.
Nvidia continues to dominate the high-end AI accelerator business and has moved close to an extraordinary $6 trillion market valuation.
That makes every major cloud-provider procurement decision increasingly important.
Nvidia Is Still the Market’s Center of Gravity
Nvidia itself rose again Tuesday, adding to a remarkable 2026 run.
The stock has become so large that even relatively small percentage moves can shift the entire S&P 500 and Nasdaq.
That concentration creates both opportunity and risk.
AI leaders have helped Wall Street overcome rising oil prices, tighter monetary policy and historically expensive borrowing costs.
But it also means that weakness in just a handful of mega-cap technology companies could quickly drag the broader indexes lower.
The seven largest U.S. technology companies collectively command a market capitalization estimated near $25 trillion, underscoring how dependent benchmark indexes have become on a small group of stocks.
Software Stocks Are Quietly Joining the AI Rally
Another important development has received less attention.
Software stocks are coming back.
The S&P 500 software and services index rose 1.3% Tuesday to a 2026 high, according to Reuters.
That follows its strongest quarterly performance since the second quarter of 2020.
Earlier this year, investors worried that generative AI would destroy traditional software businesses by allowing companies to build their own applications more cheaply.
That fear became known in some corners of Wall Street as the “SaaSpocalypse.”
So far, it hasn’t happened.
Companies including Salesforce, ServiceNow and Accenture have instead benefited from AI adoption, while cybersecurity companies such as CrowdStrike, Fortinet and Palo Alto Networks have gained from rising demand for AI-assisted security tools.
Analysts now expect software-sector earnings to grow roughly 20.6% in 2026, up sharply from expectations of just 13.8% earlier this year.
That reversal could become increasingly important if the market’s leadership broadens beyond semiconductors.
Lamb Weston Shows Earnings Still Matter
Artificial intelligence wasn’t the only reason stocks rose Tuesday.
Lamb Weston jumped after reporting earnings and guidance that beat expectations, providing another indication that corporate profits remain strong despite high borrowing costs and persistent inflation pressures.
Wall Street is becoming increasingly focused on third-quarter earnings.
Analysts are expecting unusually strong year-over-year profit growth across the S&P 500, which helps explain why investors continue buying equities despite bond yields near levels that historically created substantial pressure on stock valuations.
The market’s logic is simple:
If profits keep rising fast enough, expensive stocks can remain expensive.
But if earnings disappoint, investors may become far less willing to tolerate today’s valuations.
Option Care Health Rockets on a Multibillion-Dollar Takeover
One of Tuesday’s most dramatic individual moves came from Option Care Health, which surged more than 30% after agreeing to a multibillion-dollar acquisition involving McKesson and Clayton, Dubilier & Rice.
The transaction values the home-infusion provider at roughly $5.8 billion.
The deal reflects another major healthcare trend:
More medical treatments are moving away from hospitals and into lower-cost outpatient and home settings.
That shift has made companies involved in home infusion, specialty drugs and outpatient care increasingly attractive acquisition targets.
Wednesday Brings Applied Digital
One of Wednesday’s important earnings names is Applied Digital, a company closely associated with the AI data-center infrastructure boom.
Applied Digital is expected to report after the closing bell.
Analysts tracked by Kiplinger expect revenue to rise approximately 94% from a year earlier, even as the company is forecast to post another quarterly loss.
That combination makes the report particularly important.
Applied Digital represents exactly the type of company Wall Street has been willing to reward during the AI infrastructure boom:
rapid revenue growth today in exchange for the expectation of much greater profits later.
If growth disappoints, however, investors may become less forgiving.
Levi Strauss Will Test the Consumer
Levi Strauss is also scheduled to report Wednesday after the market closes.
The denim maker offers a very different window into the economy.
While AI companies tell investors about corporate spending, Levi’s can provide information about household demand.
That matters because consumer confidence has weakened even as Wall Street has hit record highs.
Persistent inflation, expensive credit and higher energy costs continue squeezing household budgets.
Strong Levi’s results could reinforce the argument that American consumers remain resilient.
Weak results could revive concerns that households are finally becoming more cautious.
The Biggest Wednesday Catalyst May Not Be a Stock at All
The event with the greatest potential to move markets Wednesday may come at 2 p.m. Eastern Time.
That’s when the Federal Reserve is scheduled to release the minutes from its September 15–16 policy meeting.
That meeting produced the Fed’s first rate increase in more than three years.
Investors will be studying the minutes for evidence of how strongly policymakers support additional tightening.
Markets currently see only a relatively small probability of another rate increase at the Fed’s October meeting, following softer employment and inflation data.
But investors still see a significantly greater chance of another move later this year.
A hawkish set of minutes could push Treasury yields higher.
That could be dangerous for technology stocks.
A more cautious tone could do the opposite — encouraging investors to keep buying risk assets.
Treasury Yields Remain the Market’s Biggest Threat
The benchmark 10-year U.S. Treasury yield eased Tuesday but remained near 5.3%.
The 30-year yield has recently traded above 5.6%.
Those levels matter because investors can now earn historically attractive yields from government bonds without taking equity-market risk.
Higher Treasury yields also increase corporate borrowing costs and reduce the present value of profits expected many years into the future.
That is especially important for high-growth AI and technology companies.
So far, rising earnings expectations have been powerful enough to overcome those pressures.
The question is whether that can continue indefinitely.
Oil Is Another Risk Wall Street Cannot Ignore
Brent crude remained around $100 a barrel Tuesday, while U.S. crude traded near $89.
Prices have been pushed higher by supply disruptions related to the ongoing Iran conflict.
But improved Middle Eastern exports and planned emergency stock releases have helped stabilize the market.
If oil surges again, inflation could accelerate.
And if inflation accelerates, the Federal Reserve could be forced to tighten monetary policy more aggressively.
That means a geopolitical event thousands of miles from Wall Street still has the potential to derail the stock-market rally.
The Record High Is Hiding a Strange Market
Despite Tuesday’s celebrations, not every corner of the market is participating.
The Russell 2000 fell 0.6% Tuesday, even as the S&P 500 and Nasdaq hit records.
Small companies are particularly vulnerable to expensive borrowing costs.
That divergence reinforces a recurring concern:
The headline indexes may look healthier than the average stock.
Mega-cap technology shares continue to exert enormous influence over the S&P 500.
When Nvidia, Microsoft, Alphabet, Amazon and other giants rise, they can pull the index higher even if many smaller businesses are struggling.
That is why investors will be watching not only whether the S&P 500 keeps climbing Wednesday.
They will be watching which stocks are actually participating.
What Wall Street Is Watching Wednesday
Wednesday’s session could become an important test of several competing narratives.
AI infrastructure: Can power, semiconductor and software stocks extend their rally?
Corporate earnings: Can companies justify today’s market valuations?
The consumer: Will Levi Strauss show that household demand remains resilient?
Interest rates: Will Fed minutes revive fears of additional rate hikes?
Market breadth: Can small-cap and nontechnology shares finally join the record run?
Wall Street enters the session with enormous momentum.
The S&P 500 is up roughly 14.2% in 2026, while the Nasdaq has gained about 18.7%.
Corporate profits remain strong.
AI spending remains enormous.
And investors have repeatedly bought every meaningful market pullback.
But record highs create their own challenge.
Expectations become harder to beat.
The market has survived an oil shock, a bond-market selloff, renewed Federal Reserve tightening and geopolitical uncertainty.
Wednesday will test whether investors are still willing to ignore those risks — or whether one Fed document, one earnings disappointment or one jump in Treasury yields is enough to finally make Wall Street reconsider how much optimism is already priced in.