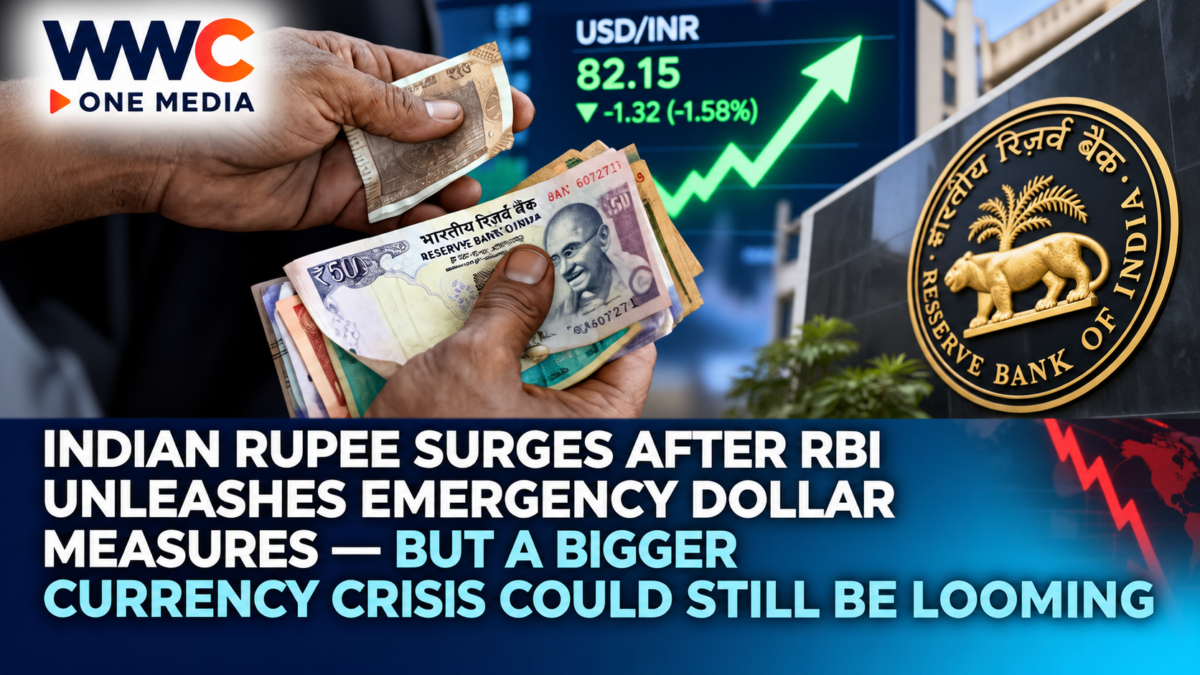
MUMBAI, India — October 12, 2026 — India’s rupee staged a dramatic rebound on Monday after the Reserve Bank of India introduced some of its most aggressive currency-support measures in more than a decade, seeking to prevent a deeper slide toward 97 rupees per US dollar.
The currency strengthened sharply in offshore trading after the central bank announced a special dollar supply arrangement for state-owned oil companies and new restrictions on foreign-exchange derivatives.
According to Bloomberg, one-month dollar-rupee non-deliverable forwards initially moved as much as 2.7% in the rupee’s favor, reaching 94.17 per dollar before surrendering much of the advance.
When domestic trading opened, the rupee strengthened around 1% to approximately 95.74–95.77 per dollar, according to Reuters.
The sharp recovery followed a difficult period for India’s currency, which has depreciated roughly 6.5% against the dollar in 2026.
But the central bank’s intervention is raising a much bigger question.
Can the RBI stabilize the rupee without exhausting its foreign-exchange buffers or imposing additional costs on Indian businesses already struggling with expensive imported energy?
RBI Takes Its Strongest Currency-Defense Measures Since 2013
The Reserve Bank of India announced a package of measures on October 10 aimed at reducing dollar demand and discouraging speculative pressure against the rupee.
Bloomberg described the response as among the central bank’s strongest currency-defense actions since the 2013 taper tantrum, when fears of reduced US monetary stimulus triggered severe pressure on several emerging-market currencies.
The latest intervention came after the rupee approached a record low near 97 per dollar.
India’s central bank had already raised its benchmark interest rate by 25 basis points to 5.5% earlier in October.
However, the rate increase had not been sufficient to reverse the currency’s slide.
With oil prices elevated and dollar demand remaining strong, policymakers introduced additional measures designed to change how importers, banks and corporations obtain foreign currency.
The strategy combines direct dollar supply, tighter derivatives rules and higher costs for selected hedging transactions.
Special Dollar Window for India’s Biggest Oil Companies
One of the most important measures is a special foreign-exchange facility for three state-owned oil marketing companies.
The arrangement covers Indian Oil Corporation, Bharat Petroleum Corporation and Hindustan Petroleum Corporation.
Beginning October 12, the RBI will meet their daily US dollar requirements through designated banks.
The Economic Times reported that the three companies require approximately $200 million in dollars each day for their import-related needs.
Under normal circumstances, major oil importers purchase dollars through the foreign-exchange market to pay international suppliers.
That demand can place pressure on the rupee, especially when crude prices rise.
By supplying dollars through a dedicated arrangement, the RBI hopes to reduce large purchases in the open market and improve short-term exchange-rate stability.
However, the facility does not remove India’s underlying need to purchase imported oil.
It changes how the dollar demand is met.
If the central bank supplies foreign currency from its reserves, the strategy may reduce spot-market pressure while drawing on official foreign-exchange resources.
New 20% Reserve Requirement Raises Hedging Costs
The RBI also introduced a Foreign Exchange Risk Reserve requirement for specified derivatives transactions.
Under the new rule, banks must maintain a 20% reserve against qualifying foreign-exchange exposures.
The requirement is intended to discourage positions that may intensify pressure on the rupee.
Reuters reported that the change could raise some corporate hedging costs by approximately 80 to 150 basis points.
Hedging is commonly used by companies to protect themselves against unfavorable exchange-rate movements.
Importers may purchase dollars forward to protect against a weaker rupee.
Exporters may use derivatives to manage the value of future dollar receipts.
However, when many businesses simultaneously increase their dollar hedges because they expect depreciation, that activity can add pressure to currency markets.
The RBI’s new framework seeks to discourage excessive or speculative positions.
But higher costs could also affect companies with legitimate needs to manage exchange-rate risk.
RBI Slashes Derivatives Threshold From $100 Million to $5 Million
Another significant measure involves foreign-exchange derivative contracts without an underlying commercial exposure.
The RBI reduced the permitted threshold for certain transactions from $100 million to $5 million.
It also restricted the rebooking of canceled rupee-linked derivative contracts.
The changes are designed to limit speculative positioning and discourage activities that could amplify currency volatility.
According to financial-market analysts, the measures could significantly reduce demand for forward dollars.
However, tighter rules can also reduce market flexibility.
Banks and corporate treasury departments may need to adjust their risk-management strategies.
The restrictions therefore create a trade-off between currency stability and the efficient operation of financial markets.
Offshore Rupee Rebounds as Traders React
The first major market reaction appeared in offshore currency trading.
Bloomberg reported that one-month dollar-rupee non-deliverable forwards fell as much as 2.7% to 94.17 per dollar in early Asian trading.
The movement indicated stronger expectations for the rupee following the central bank’s intervention.
However, the offshore rate later pared its move to approximately 0.7%.
Non-deliverable forwards are derivative contracts settled without physically delivering the two currencies.
They are widely used by international investors to hedge or take positions on currencies.
Their quoted exchange rates can differ from the domestic spot rate because they reflect the contract’s maturity, interest-rate conditions and market expectations.
That distinction matters because the offshore 94.17 quotation was not the actual domestic cash exchange rate.
When India’s onshore market opened, the rupee traded around 95.74–95.77 per dollar.
Rupee Gains Nearly 1% in Domestic Trading
The domestic currency responded strongly when Indian markets opened on Monday.
Reuters reported that the rupee rose approximately 1% to 95.74 per dollar.
The Financial Express recorded a level near 95.77, compared with Friday’s close around 96.73.
The difference between quotations reflects timing and reporting across the trading session.
The gains positioned the rupee among Asia’s stronger-performing currencies on the day.
The rally demonstrated that the RBI’s measures had an immediate market effect.
However, a strong opening does not guarantee a lasting recovery.
Currency markets can reverse quickly as investors reassess underlying economic pressures.
Why India’s Rupee Has Been Under Pressure
India’s currency weakness reflects several overlapping economic forces.
One of the biggest is the country’s dependence on imported petroleum.
When global crude prices rise, Indian refiners and oil marketing companies must spend more dollars on fuel imports.
That increases demand for foreign currency.
India has also faced withdrawals of foreign investment from financial markets, reducing some sources of dollar inflows.
Meanwhile, higher US interest rates have supported demand for dollar-denominated assets.
These pressures can reinforce one another.
A weaker rupee increases the local-currency cost of imports, while higher import costs can add pressure to inflation.
Investors may then demand greater compensation for currency risk.
The result is a difficult environment for policymakers seeking to maintain financial stability.
The Iran War Has Made India’s Currency Problems Worse
The continuing Middle East conflict has significantly complicated India’s economic outlook.
Disruptions to petroleum shipments and concerns about the Strait of Hormuz have contributed to higher international oil prices.
India is particularly vulnerable because it imports most of the crude oil it consumes.
Expensive crude can increase the national import bill and put pressure on the current account.
It can also raise costs for transportation, manufacturing and household consumption.
On October 12, Brent crude was trading around $103–$104 per barrel, according to contemporaneous market reporting.
Although prices had eased during the session, they remained elevated.
For the rupee, sustained high oil prices create a structural challenge that foreign-exchange intervention alone cannot resolve.
The central bank can manage the timing and location of dollar demand, but it cannot eliminate the country’s requirement to pay for imported energy.
India’s Foreign-Exchange Reserves Face Growing Pressure
The RBI has accumulated substantial foreign-exchange reserves to manage external financial shocks.
However, repeated intervention can reduce those buffers.
Reuters reported that India’s reserves had fallen to approximately $734 billion from a peak near $785 billion in September.
The decline is significant, although changes in reserve values can reflect multiple factors, including intervention, valuation effects and other transactions.
The central bank’s reserve position remains substantial.
But markets are closely watching how aggressively the RBI uses its foreign-currency resources.
Selling dollars can support the rupee in the short term.
However, a prolonged period of intervention may become increasingly expensive if underlying demand for dollars remains high.
For policymakers, the objective is to limit disorderly volatility without creating the impression that reserves will be used indefinitely to defend a particular exchange rate.
Interest-Rate Hike Failed to Halt the Rupee’s Slide
The RBI’s latest actions followed an October 7 decision to increase its policy rate by 25 basis points to 5.5%.
The increase was intended partly to address inflation risks associated with elevated oil prices.
Higher interest rates can support a currency by making local assets more attractive and reducing some inflationary pressure.
But rate increases also have costs.
They can make loans more expensive for households and businesses.
They may also discourage investment in sectors dependent on affordable financing.
In India’s case, the interest-rate increase did not immediately stop the rupee’s depreciation.
That helped explain why the central bank introduced additional foreign-exchange market measures over the weekend.
The intervention shows policymakers are using several tools rather than relying on monetary tightening alone.
Analysts Warn the Recovery May Be Temporary
Despite Monday’s sharp appreciation, financial-market analysts remain cautious.
Galvin Chia, an emerging Asia strategist at Société Générale in Hong Kong, said the extent of the RBI’s measures reflected how much pressure the currency had faced.
Reuters also reported analyst warnings that the rupee could resume a gradual depreciation trend unless India’s underlying balance-of-payments pressures improve.
The central bank’s measures can reduce immediate demand for dollars.
But they cannot guarantee lower oil prices, stronger foreign investment inflows or a weaker US currency.
Those external conditions will continue influencing the rupee.
Markets will also assess how long the special oil-dollar facility remains necessary and whether the derivatives restrictions significantly affect market liquidity.
Importers and Exporters Face New Currency Challenges
For Indian businesses, the new measures have mixed implications.
Companies importing oil, machinery and other goods may benefit from a stronger rupee because their dollar-denominated purchases become less expensive in local-currency terms.
However, higher hedging costs could make it more expensive to manage future exchange-rate risks.
Exporters face a different set of considerations.
A stronger rupee means dollar revenues convert into fewer units of domestic currency.
That can affect profit margins for firms with substantial local expenses.
However, exporters may also benefit from lower costs for imported inputs.
The overall financial impact therefore varies between companies and industries.
What the RBI’s Strategy Means for Asian Markets
India’s latest intervention is attracting attention because it illustrates how central banks can respond to currency stress.
The RBI is combining market intervention with regulatory restrictions and higher reserve requirements for selected derivatives.
The Indian Express noted similarities between the Foreign Exchange Risk Reserve approach and techniques used by China’s central bank.
Such strategies may influence expectations in other emerging markets facing currency volatility.
However, India’s financial system and economic circumstances are distinct.
Other Asian central banks have different reserve positions, exchange-rate arrangements and policy priorities.
The broader lesson is that currency management can involve more than interest-rate changes and direct intervention.
But each additional measure creates potential effects on market liquidity and business activity.
Why the Philippines and ASEAN Should Pay Attention
India is one of Asia’s largest economies, and its currency movements are relevant to regional investors and businesses.
A weaker rupee can change the competitiveness of Indian exports and influence prices for companies trading with India.
It can also affect the returns earned by foreign investors.
For Southeast Asian economies, India’s experience highlights the risks created by heavy dependence on imported energy during periods of geopolitical instability.
The Philippines faces its own exposure to international oil prices and US dollar movements.
However, India’s intervention does not imply that the Bangko Sentral ng Pilipinas will adopt the same measures.
Exchange-rate policies depend on each country’s financial conditions and monetary framework.
The important regional issue is how central banks balance currency stability, inflation control and economic growth when global energy prices remain elevated.
The Bigger Question: Can the RBI Defend the Rupee Without Creating New Risks?
The rupee’s sharp rebound demonstrates that the Reserve Bank of India’s intervention has influenced financial markets.
The special dollar facility for oil companies reduces one source of immediate pressure.
Tighter derivatives rules may discourage speculative activity.
And the 20% reserve requirement raises the cost of certain foreign-exchange positions.
Together, these steps have helped reverse part of the currency’s recent decline.
But the fundamental pressures have not disappeared.
India still faces expensive imported oil, foreign capital-flow uncertainty and a strong US dollar.
Its foreign-exchange reserves have also declined from their September peak.
For investors, the next question is whether the rupee can maintain its gains without continued extraordinary intervention.
For businesses, the challenge is adjusting to higher hedging costs and evolving currency regulations.
And for policymakers, the priority is ensuring that financial stability measures do not create unnecessary obstacles to economic activity.
The RBI has demonstrated its ability to influence the currency market, but stabilizing the exchange rate over the longer term will depend on the health of India’s external finances.
A durable recovery would be easier to sustain if oil prices declined, foreign capital returned and pressure on the US dollar eased.
Until then, the currency remains vulnerable to global developments.
India’s rupee has surged after the RBI introduced aggressive dollar-market measures — but the bigger test is whether New Delhi can prevent another slide toward 97 per dollar without placing additional strain on reserves and businesses.