DENVER, COLORADO / WASHINGTON / MANILA — November 7, 2026 | WWC ONE MEDIA | US Politics, Global Economy, Taxation and Wealth
America’s growing movement to tax wealthy individuals has scored a major political victory after voters in Colorado narrowly approved a sweeping tax overhaul that will nearly double the state’s highest marginal income tax rate.
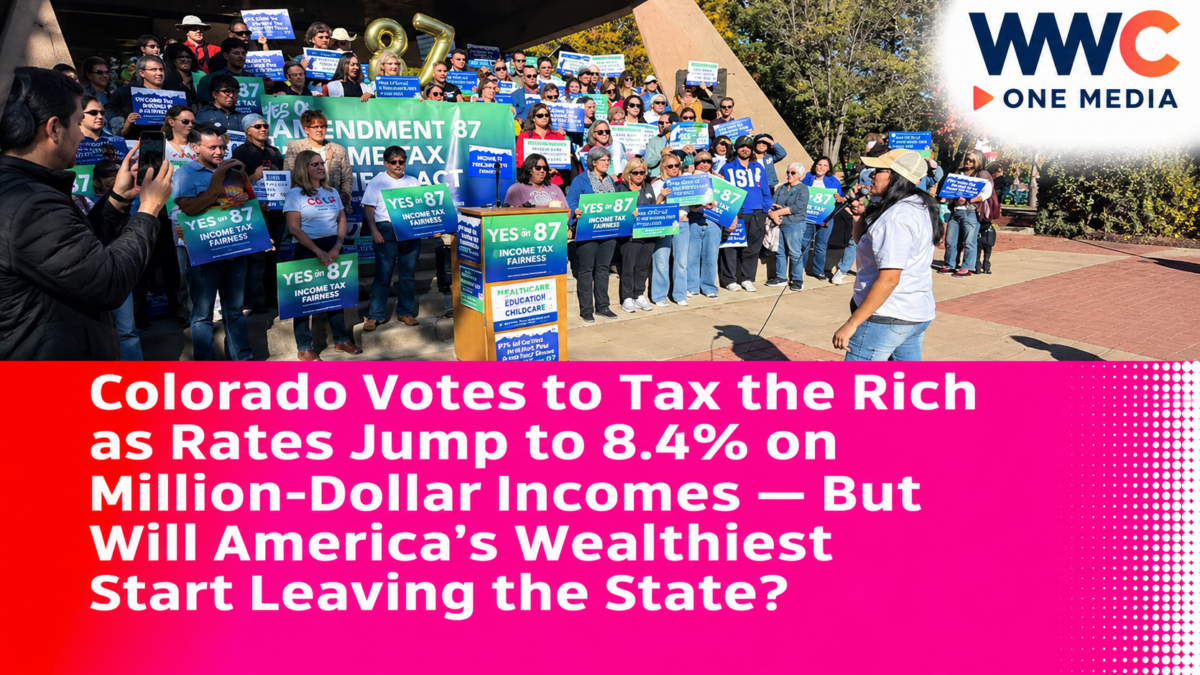
In one of the most closely watched tax battles of the November 2026 midterm elections, Colorado voters approved Amendment 87, replacing the state’s longstanding 4.4% flat income tax with a graduated system featuring rates as high as 8.4% on taxable income above $1 million.
The measure also introduces higher tax brackets beginning above $500,000 in annual taxable income while lowering taxes for many ordinary households.
The Associated Press called the race on November 6, after preliminary election results showed approximately 51.4% of voters supporting the proposal.
The victory marks a significant shift in Colorado’s fiscal policy and delivers a boost to progressive groups seeking to increase taxes on higher-income Americans.
Supporters argue that the new structure could generate billions of dollars for public schools, healthcare and childcare while reducing the income-tax burden on most residents.
Opponents warn that the tax increase could discourage investment, motivate wealthy households to relocate and weaken Colorado’s competitiveness against lower-tax states.
The stakes are significant.
Colorado has long attracted wealthy entrepreneurs, business executives and investors drawn to its outdoor lifestyle, growing economy and comparatively favorable tax environment.
Its wealthy communities include Aspen, Boulder and parts of metropolitan Denver.
Now, the state is preparing to become a major test case for a politically divisive economic question.
Can higher taxes on wealthy Americans strengthen public services without driving away the businesses, investors and high-income residents that contribute substantially to state revenue?
Colorado Voters Deliver a Narrow Victory for the Tax-the-Rich Movement
The November 3 vote was exceptionally close.
Early results showed Amendment 87 moving between narrow approval and rejection as ballots were counted across the state.
By Friday, November 6, the measure had secured approximately 51.4% support, according to preliminary results cited by Axios and the Colorado Secretary of State’s Office.
Bloomberg reported that the Associated Press had called the race in favor of the proposal.
Supporters declared victory after an intense campaign centered on tax fairness and public services.
The measure received significant support in Democratic-leaning urban and suburban communities, including Denver, Boulder and several counties along Colorado’s Front Range.
Opposition was stronger in many rural areas and more conservative communities.
The narrow result demonstrates that Colorado voters remain deeply divided over the appropriate role of taxation in funding government services.
But despite the small victory margin, the policy implications are substantial.
Amendment 87 changes a central feature of Colorado’s tax structure that had existed for decades.
Instead of taxing most income at the same flat rate, the state will apply different marginal rates as taxable income increases.
The change is expected to take effect for tax years beginning January 1, 2027.
How Colorado’s New Income Tax System Works
Before the election, Colorado applied a flat 4.4% income tax rate.
That meant a taxpayer earning $50,000 and another earning $5 million generally faced the same state income tax rate on taxable income, subject to applicable deductions and tax rules.
Amendment 87 replaces that system with six marginal brackets.
Under the new structure:
- Taxable income up to $25,000 faces a 3.7% rate.
- Income from $25,001 to $100,000 faces a 4.2% rate.
- Income from $100,001 to $500,000 faces a 4.4% rate.
- Income from $500,001 to $750,000 faces a 7.4% rate.
- Income from $750,001 to $1 million faces a 7.9% rate.
- Taxable income above $1 million faces an 8.4% rate.
The rates apply to portions of taxable income within each bracket, rather than applying the highest rate to a taxpayer’s entire income.
That is an important distinction.
For example, someone with $1.2 million in taxable income would not pay 8.4% on the entire $1.2 million.
Only the amount above $1 million would enter the highest bracket.
The rest would be taxed at the applicable lower marginal rates.
The measure also includes special treatment for certain gains from the sale of a principal residence, preserving a 4.4% rate on qualifying income.
The full impact on a taxpayer will depend on filing circumstances and the applicable legal definition of taxable income.
The broader result is that Colorado is shifting more of its income-tax burden toward higher earners.
Could 97% of Colorado Taxpayers Actually Pay Less?
One of the most important features of Amendment 87 is that it does not simply increase taxes across the board.
Supporters estimate that approximately 97% of Colorado taxpayers could receive an income-tax reduction under the new structure.
The measure lowers the rates applied to the first two income brackets, creating potential savings for a wide range of taxpayers.
According to CBS Colorado’s reporting on nonpartisan fiscal estimates, many taxpayers below approximately $550,000 in annual income could receive reductions of roughly $175 to $325 per year.
Actual outcomes vary according to taxable income and filing circumstances.
Higher-income individuals may also benefit from lower rates on their first portions of income.
However, those savings can be outweighed by the higher marginal rates applied to income exceeding the new thresholds.
Some taxpayers earning slightly above $500,000 could still experience small overall savings because the lower rates on initial income brackets offset the higher rate on a relatively limited amount of income.
That means the $500,000 threshold should not be interpreted as the exact income level at which every taxpayer begins paying more overall.
The measure also affects businesses subject to Colorado’s income-tax system.
For supporters, this structure is central to their argument that the reform is intended to increase progressivity while protecting most taxpayers from higher tax bills.
For critics, the concern is that the additional tax burden will be concentrated among individuals and businesses capable of moving capital, employment and investment to other states.
The $2.7-Billion Question: Where Will the Money Go?
The ballot measure was promoted as a way to generate approximately $2.7 billion annually in additional state revenue.
That headline estimate became a major feature of the campaign.
However, Colorado’s official fiscal analysis provides a more detailed projection.
Legislative analysts estimated that the measure would generate approximately $958.4 million in additional revenue during fiscal year 2026–27 and about $1.97 billion during fiscal year 2027–28.
The initial fiscal year captures only part of the first tax year.
Differences between the ballot’s headline estimate and fiscal forecasts reflect differing assumptions and forecasting periods.
Therefore, the $2.7-billion figure should not be presented as money the state has already collected or guaranteed annual proceeds.
The funds are expected to support three broad priorities.
Public education: Additional resources could be used to improve kindergarten through 12th-grade education, strengthen career and technical training, and increase teacher compensation.
Healthcare: The funding could help improve access to medical care, address healthcare affordability, support behavioral health services and respond to funding pressures affecting vulnerable residents.
Early childhood programs: Additional resources could support childcare affordability, early learning services and compensation for childcare workers.
The measure creates the Colorado Future’s Account to receive the additional revenue and requires public reporting on its use.
Supporters argue that dedicated funding will help address longstanding gaps in essential services.
However, the precise allocation across eligible programs will depend on subsequent budget decisions and applicable legal requirements.
The money has not yet been collected or distributed.
Colorado Breaks Away From Nearly Four Decades of Flat-Tax Policy
The result represents one of the most significant changes to Colorado’s income-tax system in decades.
Colorado’s existing flat-tax structure dates back to the late 1980s.
The state’s constitutional framework was subsequently shaped by the Taxpayer’s Bill of Rights, commonly known as TABOR, which voters approved in 1992.
TABOR limits certain government revenue and spending growth and generally requires voter approval for specified tax increases.
Amendment 87 removes the constitutional requirement for a single uniform state income tax rate.
It also exempts the additional revenue generated by the new structure from the ordinary TABOR revenue limit.
That exemption is particularly important.
Without it, increases in tax collections could potentially trigger refund requirements under Colorado’s existing fiscal rules.
With the exemption, the state can retain and spend the new revenue for the purposes specified in Amendment 87.
The change therefore affects both the amount of taxes collected and the government’s ability to use those funds.
It is not merely a technical adjustment to income-tax brackets.
Colorado voters have changed how the state distributes tax burdens and how additional tax revenue can be retained.
Voters Reject a Competing Plan to Keep Taxes Capped at 4.4%
Amendment 87 was not the only tax-related proposal appearing on Colorado’s November ballot.
Voters also considered Proposition 136, a competing initiative that would have established a statutory maximum income tax rate of 4.4%.
The proposal was designed to preserve the existing flat-rate ceiling and prevent substantially higher rates from taking effect.
However, Colorado voters rejected Proposition 136.
According to the reported results, the measure failed with approximately 52% voting against it.
Its defeat removed a potential legal conflict between the competing tax policies.
Had both measures passed, Colorado could have faced disputes over how their conflicting provisions should be implemented.
The results demonstrate that voters favored the graduated income-tax system over an alternative designed to preserve a 4.4% rate cap.
For supporters, the outcome provides a stronger political mandate for reform.
For opponents, the narrow victory margin suggests continuing public concern about the state’s future economic competitiveness.
Even Colorado’s Democratic Leaders Opposed the Tax Increase
One of the most surprising elements of the election was the division among prominent Colorado Democrats.
Although progressive organizations strongly supported Amendment 87, several influential Democratic political figures opposed it.
Axios reported that Governor Jared Polis, Governor-elect Phil Weiser and former US Senator Ken Salazar were among those who raised concerns about the measure.
Their opposition reflected worries about potential economic consequences, including reduced investment and the possibility of higher-income residents relocating.
Weiser nevertheless pledged to implement the measure if voters approved it.
That commitment is significant because he is expected to oversee the beginning of the new policy after taking office.
The division shows that taxation remains a contested issue even among politicians belonging to the same party.
Some Democrats favor higher taxes on wealthy households to fund public services.
Others worry that aggressive state-level taxation could reduce investment or put local businesses at a disadvantage.
The Colorado outcome may intensify that debate nationally.
Could Wealthy Residents Leave Colorado?
The possibility of wealthy households relocating has become one of the most politically charged arguments surrounding Amendment 87.
Opponents say higher marginal rates could encourage wealthy individuals, entrepreneurs and business owners to consider moving to states with lower income taxes.
Texas, Florida and Nevada are frequently cited as alternatives because they do not impose broad individual state income taxes.
For a high-income resident, the difference in state tax liabilities can be substantial.
The financial incentives can become especially significant for entrepreneurs planning major business sales, executives receiving large compensation packages and investors realizing sizable taxable gains.
However, tax rates are only one factor influencing residential and business decisions.
Access to skilled workers, industry networks, schools, infrastructure, housing, climate and lifestyle preferences also matter.
Colorado offers advantages in several of these areas.
Denver has developed a substantial professional services and technology economy.
Boulder attracts businesses and workers connected to research, education and innovation.
Aspen remains an internationally recognized destination for wealthy property owners and visitors.
Those characteristics could help retain some high-income residents despite the tax increase.
There is currently no verified evidence that Amendment 87 has already caused a large exodus of wealthy Colorado residents.
Any such claim would require migration, tax-filing and employment data collected after implementation.
The potential for relocation is a legitimate economic concern, but it remains a risk rather than an established consequence of the vote.
California’s Billionaire Tax Fight Shows a Divided America
Colorado’s decision forms part of a broader national debate over how much wealthy Americans should contribute to government revenue.
California recently faced its own high-profile battle over a proposed one-time tax on billionaire fortunes.
As WWC ONE MEDIA previously reported in its examination of California’s proposed 5% billionaire wealth tax, supporters argued that extraordinary private wealth should contribute more toward public healthcare and other essential programs.
Opponents warned about potential investor departures, complicated asset valuations and legal challenges.
But the two proposals are fundamentally different.
California’s initiative targeted billionaire net worth through a proposed one-time wealth tax.
Colorado’s Amendment 87 changes recurring state income-tax rates.
A wealth tax generally targets the value of covered assets, while an income tax applies to taxable income generated during a particular period.
Those differences can produce very different economic and administrative consequences.
The California proposal was rejected in the November election, while Colorado voters narrowly approved their graduated income-tax amendment.
Together, the outcomes show that voters are not delivering a uniform national endorsement of every proposal to increase taxes on wealthy individuals.
Instead, they are making different judgments about the types, scale and purposes of taxation.
New York’s Luxury Home Tax Adds Another Front to the Battle
The debate is also unfolding in New York, where policymakers have pursued additional taxes on expensive second homes.
As WWC ONE MEDIA reported on a New York appeals court decision involving Mayor Zohran Mamdani’s luxury property surcharge, litigation over the measure has highlighted the legal and economic challenges associated with targeting high-value property ownership.
The New York policy is different from Colorado’s graduated income tax.
It concerns qualifying residential properties rather than broadly increasing taxes on personal income.
Nevertheless, both debates involve efforts to collect additional public revenue from residents or asset owners with substantial financial resources.
Supporters argue that such policies can help fund services while reducing pressure on less wealthy households.
Opponents question whether the additional revenue will justify the economic risks and administrative complexity.
The issue increasingly reaches beyond the question of whether wealthy individuals should pay more.
It also concerns which forms of wealth or income should be taxed, how those taxes should be administered and whether the revenue will produce measurable public benefits.
America’s Millionaires Are Not All Silicon Valley Billionaires
Colorado’s measure also highlights a frequently overlooked distinction between high-income taxpayers and the ultrawealthy.
Not everyone earning more than $500,000 annually is a billionaire, a corporate chief executive or a Wall Street financier.
Some high-income taxpayers are physicians, law firm partners, entrepreneurs, professional services providers or owners of closely held businesses.
As WWC ONE MEDIA previously examined in its report on America’s broader millionaire class, substantial wealth is spread across many sectors and communities, not just among famous technology founders.
Research by economists Owen Zidar and Eric Zwick highlights the importance of business owners in understanding how wealth is distributed across the United States.
That distinction matters for Colorado.
The measure does not apply solely to the richest billionaires.
It changes taxes for qualifying individuals and businesses at income levels substantially below billionaire wealth.
A household can earn more than $500,000 in a single year without owning anything close to $1 billion in assets.
Likewise, a billionaire could report taxable income that differs greatly from the yearly increase in the value of their investments.
Income and net worth are separate measures.
Therefore, describing Amendment 87 as a billionaire wealth tax would be inaccurate.
It is a graduated income-tax measure that increases marginal rates for higher levels of taxable income.
Business Groups Warn About Investment and Employment
Opposition to Amendment 87 extended beyond wealthy individuals concerned about their personal tax bills.
Business organizations and conservative advocacy groups argued that the higher rates could weaken Colorado’s ability to compete for investment.
Companies evaluating where to establish offices, expand operations or locate their headquarters may consider state tax conditions alongside infrastructure, labor availability and operating costs.
Higher taxes can reduce the after-tax returns available to business owners and some investors.
Critics say those changes could influence decisions about hiring, investment and expansion.
They also argue that Colorado’s government should demonstrate greater spending discipline before collecting billions of dollars in additional revenue.
Supporters reject the idea that modest tax relief for most residents and improved public services necessarily come at the expense of economic growth.
They argue that well-funded schools, affordable childcare and better healthcare can strengthen the labor force and make Colorado more attractive to families and employers.
For example, expanded childcare access could help more parents participate in the workforce.
Improved education could support long-term productivity.
Better access to medical care could reduce financial insecurity and improve worker health.
However, such benefits would depend on how effectively the government spends the additional revenue.
Neither the supporters’ projected economic improvements nor the opponents’ predicted business departures are guaranteed.
The Tax Fight Could Influence America’s 2028 Political Debate
Colorado’s vote arrives amid broader political changes following the November 2026 midterm elections.
Taxation, inflation, healthcare spending and government deficits have emerged as important issues for politicians seeking to shape economic policy.
The Colorado outcome may encourage advocates in other states to consider graduated income-tax proposals.
But copying the policy would require addressing local constitutional requirements, political conditions and existing tax structures.
Some states already impose progressive income taxes.
Others rely on flat rates or do not levy a broad individual income tax at all.
The debate may also become more prominent at the federal level.
Progressive politicians could argue that Colorado demonstrates public support for higher taxes on high-income households when revenues are tied to widely used services.
Conservative politicians could highlight the narrow result and potential competitiveness risks as arguments against expanding progressive taxation.
The election is therefore relevant to the wider debate over tax fairness, investment and the financing of public services.
But Colorado’s result should not be interpreted as proof that American voters universally favor higher taxes on wealthy households.
Other states reached different conclusions in the same election cycle.
What Colorado’s Decision Means for the Philippines
Although Colorado’s income-tax system operates under a different legal framework, the vote raises questions that are also relevant to Philippine fiscal policy.
The Philippines already uses a graduated personal income-tax structure.
Higher levels of taxable income generally face higher marginal rates under the country’s income-tax framework.
This reflects the principle that taxpayers with greater capacity to pay may contribute a larger share of their taxable income.
But progressive taxation also involves trade-offs.
Governments must balance revenue collection against investment incentives, compliance costs and economic competitiveness.
The Philippines faces continuing debates over how to generate sufficient revenue for education, healthcare, infrastructure and social programs while supporting private-sector growth.
The Colorado experience illustrates why these discussions cannot be reduced to a simple choice between taxing wealthy households and supporting business development.
Public services require funding.
Businesses require a competitive operating environment.
And taxpayers expect governments to demonstrate that revenue is spent effectively.
The most important lesson will emerge from Colorado’s actual experience after implementation.
If the state raises substantial revenue without major economic disruption, supporters elsewhere may cite it as evidence that more progressive taxation can be workable.
If revenue disappoints or investment weakens, critics may use the experience to argue against similar reforms.
For now, neither conclusion can be drawn.
What Happens When the New Tax Takes Effect in January 2027?
The next stage will focus on implementation.
Colorado officials must prepare tax administration systems, issue guidance and establish procedures for applying the new brackets.
Legislators will also determine how additional revenue should be allocated among eligible programs.
Taxpayers and businesses will need to understand how the new structure applies to their particular circumstances.
Accountants and tax advisers may be required to update withholding estimates, projected tax payments and financial plans.
Public officials will then face the more difficult task of demonstrating measurable benefits from the extra revenue.
Supporters will expect improvements in education, healthcare and childcare.
Opponents will monitor possible changes in employment, business investment and taxpayer migration.
The state will also need to track how much revenue the new brackets actually generate.
That figure could differ from election-campaign estimates because income growth, investment returns and taxpayer behavior are difficult to forecast precisely.
The first full years of implementation will provide more meaningful evidence about the measure’s fiscal and economic consequences.
Could the Tax-the-Rich Movement Spread Across America?
Colorado has now become a major example of voters directly approving a significant increase in taxes on higher-income residents.
The decision could influence political debates elsewhere.
But states differ widely in their economic structures.
A tax policy appropriate for one state may have different consequences in another.
Places with large concentrations of high-income taxpayers may generate substantial revenue from higher rates.
At the same time, relying heavily on relatively small groups of taxpayers can make government collections more sensitive to economic cycles and changes in residency.
Capital gains, business profits and executive compensation can fluctuate considerably from year to year.
That creates uncertainty in revenue projections.
The challenge for Colorado will be to manage those fluctuations while providing predictable support for essential services.
If lawmakers commit ongoing spending based on temporarily elevated tax receipts, future revenue declines could create budget pressure.
That makes prudent fiscal management particularly important.
The measure may be a major political victory for supporters of progressive taxation, but its long-term success will depend on financial performance and economic outcomes.
The Bigger Question: Will Colorado’s Wealthy Stay or Go?
Colorado’s November election has delivered a major shift in American state tax policy.
Voters narrowly approved a new graduated income-tax structure that lowers marginal rates for lower levels of income and increases them for higher earners.
The top rate will reach 8.4% on taxable income above $1 million.
Supporters expect additional revenue to strengthen education, healthcare and childcare.
Opponents warn that the policy could undermine competitiveness and encourage some wealthy residents and businesses to relocate.
Both sides now face a test.
For supporters, the challenge is proving that higher taxes on top earners can deliver meaningful public benefits.
For opponents, the challenge is demonstrating whether the feared economic consequences actually occur.
The outcome could influence taxation debates across the United States.
But the most important results will not be determined by political speeches or campaign advertisements.
They will emerge from future data on tax collections, economic activity, public services and taxpayer behavior.
Colorado has voted to change who pays more and who pays less. Whether the new system makes the state more prosperous will depend on what happens after the votes are counted.
And as America’s wealthiest taxpayers confront higher state income-tax rates, one question now hangs over Colorado’s economy: Will the rich stay and help finance a new era of public investment—or will the state’s tax revolution drive some of its most valuable taxpayers away?