
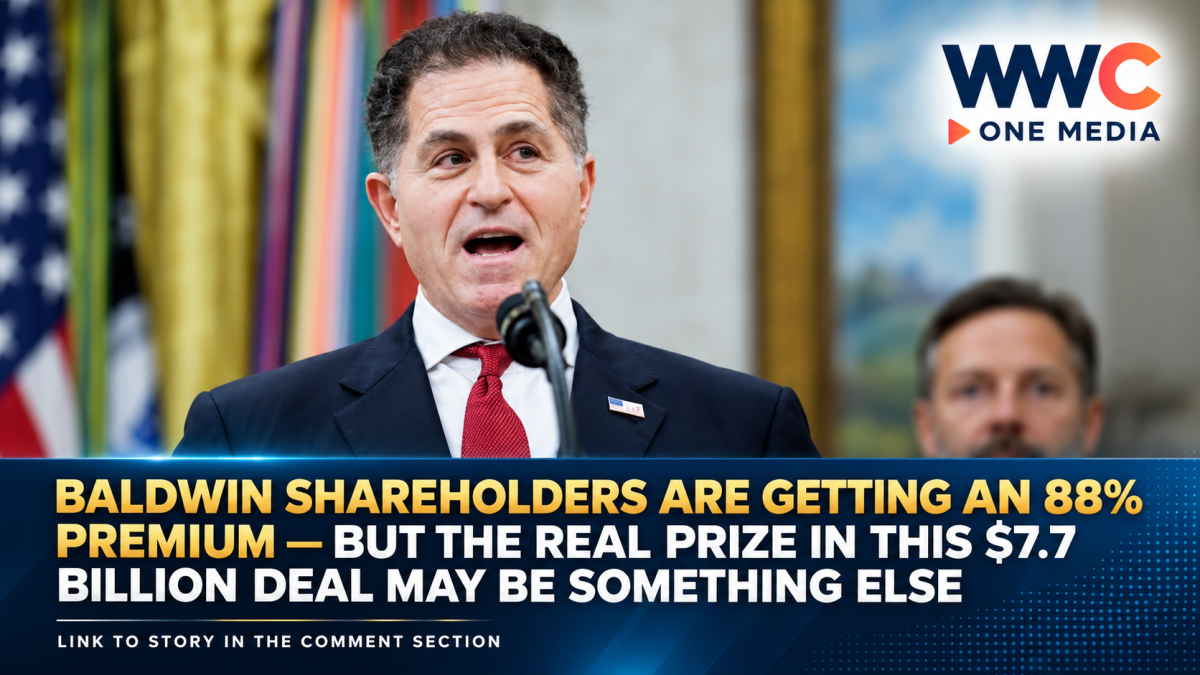
TAMPA, Florida — September 14, 2026 — Michael Dell is making another multibillion-dollar bet on what technology could do to a traditional industry — but this time, the target is not a computer company.
DFO Management, the family investment office that manages assets for Dell and his family, is joining technology-focused holding company Sequence Holdings in a deal to take The Baldwin Group private for an enterprise value of approximately $7.7 billion.
Baldwin shareholders will receive $32.50 per share in cash, representing an approximately 88% premium to Baldwin’s June 17 closing price, the last unaffected trading day before reports surfaced that the company was exploring a possible sale.
But behind the eye-catching premium lies a potentially bigger story.
The buyers are not simply acquiring an insurance brokerage for its existing cash flow.
They are betting that artificial intelligence can reshape how insurance brokers analyze risk, serve clients, automate internal processes and ultimately compete.
And Baldwin has already started that transformation.
THE $7.7 BILLION NUMBER INCLUDES MORE THAN THE STOCK
The transaction gives Baldwin an estimated equity purchase price of about $4.6 billion, while approximately $3.1 billion of net debt will be assumed or refinanced, producing the roughly $7.7 billion total enterprise value.
That valuation works out to roughly 20 times Baldwin’s trailing 12-month adjusted EBITDA of about $396 million, according to the company.
Sequence and DFO will acquire a majority interest through a newly created acquisition vehicle. After the merger is completed, Baldwin will survive as a privately held subsidiary and its shares will no longer trade on Nasdaq.
Eligible Baldwin employees who already own equity will be allowed to roll over part of their holdings, leaving employees with what the company describes as a significant minority stake in the private business.
The transaction is not subject to a financing condition, an important detail because it reduces one potential source of uncertainty surrounding completion.
Baldwin’s board unanimously approved the transaction after receiving the unanimous recommendation of a special committee of independent directors.
The companies expect the deal to close during the first quarter of 2027, subject to Baldwin shareholder approval, regulatory clearances and customary closing requirements.
WHY PAY AN 88% PREMIUM?
That headline figure requires context.
The $32.50-a-share offer represents an 88% premium compared with Baldwin’s price on June 17 — before takeover speculation began affecting the stock.
By the Friday immediately preceding the deal announcement, however, Baldwin shares had already climbed to $29.65 as investors priced in the possibility of a transaction. That means the final offer was roughly 10% above the latest pre-announcement market price rather than 88%.
After the agreement was announced, Baldwin shares rose another 7.5% to $31.89, leaving them just below the agreed cash purchase price.
The enormous difference between the June price and the eventual offer illustrates how dramatically expectations surrounding the business changed once takeover interest became public.
It also reflects why insurance brokers have become attractive acquisition targets.
Unlike insurers themselves, brokers generally do not take the same underwriting risk. Instead, they generate commissions and fees by helping businesses and individuals arrange insurance and manage risk.
That can produce recurring revenue and strong cash generation — characteristics particularly attractive to investors seeking businesses that can support long-term technology investment.
Peter McMurtrie of West Monroe’s insurance practice told Reuters that the transaction sends a positive signal for the brokerage sector because insurance brokers combine recurring revenues and cash flow with considerable room for further consolidation in what remains a fragmented industry.
AI ISN’T AN AFTERTHOUGHT — BALDWIN WAS ALREADY BUILDING AROUND IT
Perhaps the most important context missing from the $7.7 billion headline is what Baldwin was doing before Michael Dell’s family office arrived.
In May 2026, Baldwin announced an expanded enterprise partnership with Anthropic, rolling out its Claude AI system across the company.
The insurer said Claude would be deployed among advisers, client-service teams and operational leaders to help analyze risk, synthesize client information, improve decision-making and automate complex workflows.
Baldwin said it had already been testing the technology in parts of the business and had seen improvements in productivity, workflow efficiency and the quality of client-facing insights.
Over time, the company said it wanted to move beyond simple AI assistance and toward more advanced agentic workflows capable of performing larger parts of an end-to-end business process.
That background makes the wording surrounding the takeover significant.
CEO Trevor Baldwin said the partnership with Sequence and DFO would give the company both long-duration capital and the ability to execute more rapidly on frontier AI.
In other words, the company is not suddenly adding an AI story to justify a buyout.
AI was already part of its strategy.
The acquisition could allow Baldwin to pursue it far more aggressively.
WHY GO PRIVATE TO INVEST IN AI?
Public companies live quarter to quarter in a way privately held firms often do not.
Large technology upgrades can demand substantial upfront spending while taking years to produce their full financial benefit.
That creates a difficult trade-off for publicly listed businesses: investment can depress margins in the short term, even when management believes it will create greater value later.
Reuters noted that private ownership can give management more freedom to absorb those near-term costs without facing the same quarterly earnings expectations and stock-price volatility.
That appears central to the Baldwin thesis.
DFO is presenting itself as a provider of patient capital, rather than a conventional private-equity fund operating under a fixed timeline to sell its investment.
Michael Dell said Baldwin had developed what he sees as a rare data and platform advantage over roughly 15 years, while DFO’s structure allows it to back management without working toward a predetermined fund exit.
Sequence brings a different component.
The New York-based holding company buys established service businesses and combines them with its technology platform, Atlas, with the goal of rebuilding workflows, products and operations around modern software and AI.
That combination explains why Baldwin may be particularly attractive.
DFO provides long-duration capital.
Sequence provides engineering expertise and a technology operating model.
Baldwin provides an existing insurance distribution platform, millions of clients and years of proprietary industry data.
AI is the layer that could connect all three.
BALDWIN ISN’T A DISTRESSED COMPANY LOOKING FOR A RESCUE
Another important part of the story is Baldwin’s recent financial performance.
The company reported second-quarter 2026 revenue of $492.9 million, up 30% from a year earlier.
Adjusted EBITDA rose 37% to $116.7 million, while adjusted free cash flow jumped to $46.4 million, according to Baldwin’s July earnings report.
Baldwin did report a GAAP net loss of $56 million for the quarter, but adjusted diluted earnings per share rose 14% to $0.48.
For the first six months of 2026, revenue reached approximately $1 billion, up 29% year over year.
That means Sequence and DFO are buying into a company already expanding quickly rather than attempting to engineer a turnaround from a collapsing base.
Baldwin says it represents more than three million clients in the United States and internationally across risk management, insurance and employee-benefits services.
MICHAEL DELL’S ROLE NEEDS ONE IMPORTANT CLARIFICATION
The involvement of one of the technology industry’s best-known billionaires makes for an obvious headline.
But the structure of the transaction matters.
Dell Technologies itself is not acquiring Baldwin.
DFO Management manages the investment assets of Michael Dell and his family. The organization traces its history to MSD Capital, which was established in 1998 and restructured as DFO Management at the end of 2022.
That distinction makes the Baldwin transaction a personal investment-office strategy rather than a corporate acquisition by Dell Technologies.
Still, Michael Dell’s history is relevant.
Dell famously helped take his namesake computer company private in a massive leveraged buyout in 2013 before Dell Technologies eventually returned to public markets.
The Baldwin transaction carries echoes of the same broad argument: that private ownership can provide management with greater freedom to make major long-term changes away from the relentless judgment of public equity markets.
This time, however, the technological upheaval at the center of the thesis is artificial intelligence.
INSURANCE DEALMAKING IS HEATING UP
Baldwin is also becoming private during a period of significant consolidation across the insurance brokerage industry.
Just two weeks earlier, Aon agreed to acquire USI Insurance Services for $17 billion, dramatically expanding its position in the U.S. middle-market insurance sector. Aon explicitly highlighted data, analytics and AI-enabled solutions as part of the strategic logic for that transaction.
That deal followed Aon’s 2024 acquisition of NFP and illustrates the broader race to build scale, proprietary data and technology across insurance distribution.
The Baldwin transaction takes a different route.
Instead of combining Baldwin with another publicly traded insurance giant, Sequence and DFO intend to pull it out of public markets and accelerate investment behind closed doors.
That could turn Baldwin into an important test case for whether the next generation of insurance brokerage competition will be decided not only by who has the largest distribution network, but by who can most effectively combine industry expertise, proprietary data and AI.
THE BIGGER BET IS ON HOW INSURANCE WORK GETS DONE
At first glance, this looks like another multibillion-dollar take-private deal.
At $32.50 per share, investors who owned Baldwin before takeover speculation emerged are being offered a substantial payday.
But the language from all three parties points toward something more ambitious.
Sequence wants to rebuild service businesses around modern technology.
DFO wants to supply patient capital without a conventional private-equity exit clock.
Baldwin wants to move faster on AI.
And the target company already has an enterprise relationship with one of the world’s leading AI developers.
That makes the $7.7 billion transaction more than a bet on insurance commissions.
It is a bet on whether AI can meaningfully change the economics of a labor-intensive professional-services business — automating routine work, giving advisers faster access to information, improving risk analysis and potentially allowing each employee to serve more clients.
If that strategy works, the biggest number associated with the Baldwin deal may ultimately not be the $7.7 billion purchase price.
It may be how much more valuable an old-fashioned insurance brokerage can become once its new owners rebuild the way the company works.
Leave a Reply