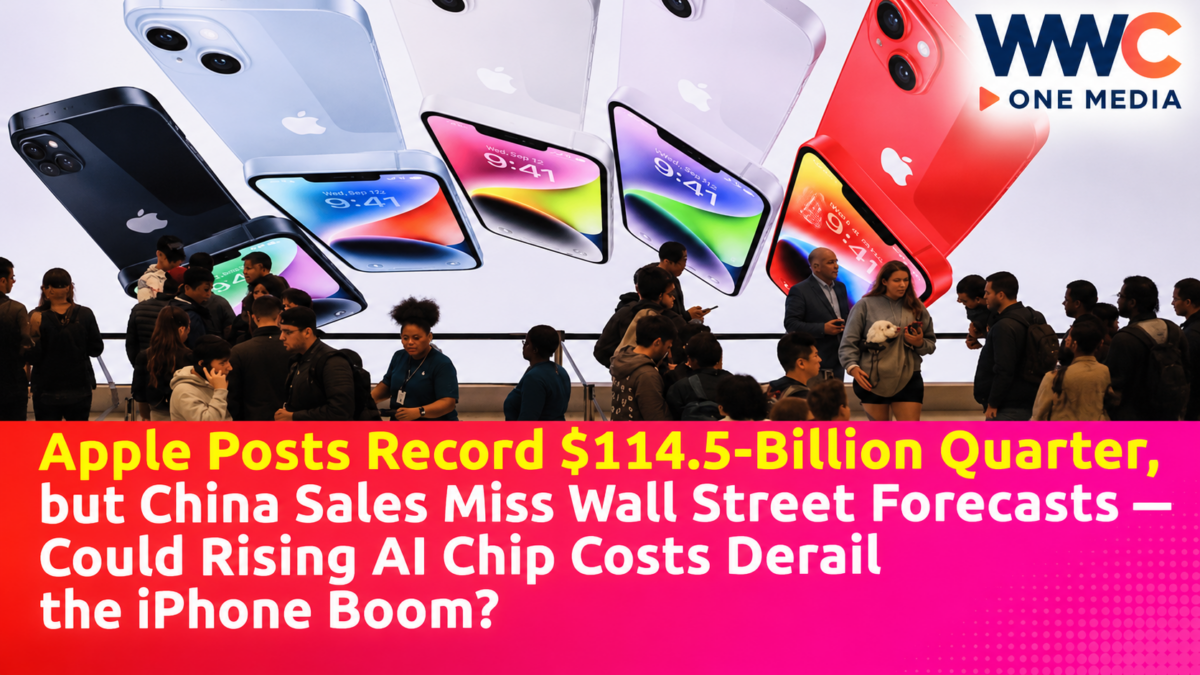
CUPERTINO, California / MANILA — November 3, 2026. Apple has delivered another record-breaking quarter, but disappointing sales relative to expectations in Greater China and warnings about rising manufacturing costs are raising questions about whether the technology giant can sustain its extraordinary growth.
The iPhone maker reported $114.48 billion in revenue for its fiscal fourth quarter ended September 26, 2026, up approximately 12% from the same period last year and ahead of Wall Street expectations.
But while its headline earnings exceeded forecasts, the results revealed a more complicated story.
Apple’s Greater China revenue reached $17.54 billion, rising approximately 21% year on year but falling short of the $18.58 billion expected by analysts in a Visible Alpha survey.
The company’s overall revenue growth also slowed from approximately 16% in the preceding quarter to 12% in the latest period.
Meanwhile, soaring memory-chip prices and additional artificial intelligence costs are expected to reduce profitability during the crucial holiday shopping season.
According to Bloomberg, Reuters and the Financial Times, the combination of weaker-than-expected performance in selected product categories and rising costs has prompted investors to reassess Apple’s outlook.
The results represent the first quarterly earnings report under chief executive John Ternus, who succeeded Tim Cook in September.
With Apple’s iPhone business still setting records but China expectations and profit margins coming under pressure, can its new leadership deliver another wave of growth — or are the enormous costs of the AI era beginning to catch up with the company?
Apple Beats Wall Street Forecasts With $114.48 Billion in Revenue
Apple reported quarterly revenue of $114.48 billion, exceeding the approximately $113.39 billion expected by analysts surveyed by LSEG.
The company generated net income of approximately $30.71 billion, up from $27.47 billion in the year-earlier period.
Diluted earnings per share reached $2.10, compared with approximately $1.99 expected by analysts.
The results represented a new September-quarter revenue record.
However, Apple’s earnings benefited partly from tariff refunds.
The company disclosed that these refunds increased quarterly earnings by approximately five cents per share and contributed roughly one percentage point to reported gross margin.
The financial performance was therefore strong, but investors must consider these temporary benefits when evaluating underlying profitability.
Apple also reported approximately $28 billion in quarterly operating cash flow.
For its full fiscal year, revenue reached approximately $478.8 billion, establishing another annual company record.
These figures demonstrate that Apple remains highly profitable despite intensifying competition and higher component costs.
Revenue Growth Slows From 16% to 12%
The headline revenue result conceals a meaningful slowdown.
Apple’s sales rose approximately 16% year on year in the June quarter.
That rate moderated to approximately 12% in the September quarter.
Revenue was still increasing, but at a slower pace.
This distinction matters because investors often value large technology companies based on expectations of future earnings growth.
A business can post record sales while still disappointing investors if its growth rate falls below expectations.
For Apple, the challenge is particularly important because its market capitalization has reached extraordinary levels.
WWC ONE MEDIA previously examined the company’s valuation in Apple Reclaims $5-Trillion Crown From Nvidia as AI Stocks Tumble — But Is Wall Street Turning Against the AI Boom?.
The report explored how Apple had overtaken Nvidia in market value during a broader technology-sector selloff.
High valuations can reflect investor confidence in a company’s long-term prospects.
But they also raise expectations.
Even a profitable business may experience stock-market volatility if investors believe its future growth will be weaker than previously anticipated.
China Sales Rise 21% but Still Miss Expectations
Greater China was one of Apple’s most closely watched markets.
The region, which includes mainland China, Hong Kong and Taiwan, generated approximately $17.54 billion in quarterly revenue.
That represented growth of roughly 21% from a year earlier.
It also confirmed a substantial recovery following earlier periods of weakness.
However, the result fell below the $18.58 billion expected by analysts surveyed by Visible Alpha.
The difference was approximately $1 billion.
Other analyst surveys used different forecasts, so the size of the reported miss varies by data provider.
The critical point is that Apple delivered strong growth in China but did not meet every market expectation.
That is different from reporting an actual decline.
China remains strategically important because it is one of the world’s largest smartphone markets and a major center of electronics manufacturing.
Apple faces competition from domestic brands such as Huawei, Xiaomi and Honor.
Those companies compete across premium smartphones, foldable devices, software ecosystems and AI-enabled features.
Apple must therefore maintain its appeal among Chinese consumers while navigating a highly competitive market.
Apple’s Foldable iPhone Faces Fierce Competition in China
Apple’s first foldable smartphone, the iPhone Duo, represents one of its most significant new product launches.
The device was unveiled in September and began reaching customers in October.
Its starting price of approximately $1,999 places it firmly in the premium smartphone market.
WWC ONE MEDIA previously examined the challenge in Apple’s Foldable iPhone Faces Big Questions in China Despite Landmark Launch.
The report highlighted competition from Huawei and other Chinese manufacturers that had already established positions in foldable devices.
Apple’s entry could change consumer expectations and competitive dynamics.
But a successful launch does not automatically guarantee long-term market-share gains.
Apple must demonstrate product reliability, adequate supply and compelling value at a premium price.
Importantly, the iPhone Duo began shipping after Apple’s September reporting quarter ended.
Its launch sales therefore were not included in the $114.48-billion quarterly revenue result.
The product’s commercial impact will become clearer in subsequent financial reports.
iPhone Revenue Climbs 17% to $57.58 Billion
Apple’s core iPhone business remained a major source of strength.
Quarterly iPhone revenue reached approximately $57.58 billion, compared with $49.03 billion a year earlier.
That represented growth of roughly 17%.
The figure also exceeded analysts’ expectation of approximately $56.54 billion.
The latest quarter benefited from the early availability of the iPhone 18 Pro lineup.
Demand for premium devices helped support revenue.
Apple also increased prices on selected smartphone and laptop models, which helped offset some rising component costs.
However, revenue growth should not be confused with an identical increase in unit sales.
Revenue can rise because consumers purchase more expensive configurations, prices increase, or the mix of products changes.
Apple does not routinely disclose comprehensive iPhone unit shipments in its quarterly earnings report.
Without that data, the 17% revenue increase should not be described as proof that iPhone unit shipments rose 17%.
For investors, the next important question is whether premium demand can remain resilient as consumers face higher prices.
The $2,000 iPhone Duo Sells Out but Faces Supply Problems
Apple’s foldable iPhone has generated significant early demand.
Reuters reported that the company encountered supply constraints and strong consumer interest following the device’s launch.
Some delivery estimates stretched into 2027.
WWC ONE MEDIA previously covered the situation in Apple’s $2,000 iPhone Duo Sells Out as Global Demand Explodes and Deliveries Slip to 2027 — But Is the Foldable iPhone Hiding a Major Flaw?.
The device has also attracted attention over reports of display defects affecting a small number of units.
Apple has said it is replacing affected devices.
Chief executive John Ternus acknowledged that supply remains constrained and that the company cannot yet predict when production will fully meet demand.
For Apple, the situation presents both an opportunity and a risk.
Strong demand could support higher revenue in future quarters.
But limited supply may prevent the company from fulfilling orders as quickly as customers expect.
Product-quality concerns may also require additional customer support and replacement expenses.
The next earnings period should provide a clearer indication of how much the foldable device contributes to Apple’s financial performance.
Memory-Chip Costs Threaten Apple’s Holiday Profits
One of the most serious challenges facing Apple is the rising cost of memory chips.
AI infrastructure investment has increased demand for advanced memory components used in data centers and high-performance computing systems.
Semiconductor manufacturers have increasingly prioritized higher-value products for AI servers.
That has contributed to tighter availability and higher prices for memory used in consumer electronics.
Apple uses memory in iPhones, iPads, Macs and other devices.
Rising component costs can therefore affect profitability across several product categories.
The company reported a gross margin of 47.9% for the September quarter.
But management forecast a decline to approximately 45%–46% for the December quarter.
That is a substantial expected reduction in the proportion of revenue remaining after product and service costs.
Reuters reported that higher memory prices were among the main drivers of the weaker outlook.
Apple has attempted to mitigate the pressure through inventory management, procurement arrangements and selected price increases.
However, management expects memory costs to remain a challenge into the following year.
The AI Memory Shortage Is Affecting the Entire Electronics Industry
Apple is not alone in confronting semiconductor supply pressure.
Smaller smartphone and laptop manufacturers have also warned that memory shortages are forcing them to reconsider product designs, prices and inventory strategies.
WWC ONE MEDIA examined the problem in Small Phone and Laptop Makers Are Running Out of Memory Chips — But Paying More May No Longer Be Enough.
The report detailed how demand from AI data centers is influencing the allocation of global memory production.
For some manufacturers, the problem involves both higher prices and difficulty securing enough components.
Apple’s scale may give it advantages in negotiating supply agreements.
But even a company with substantial purchasing power cannot completely avoid marketwide cost pressure.
The shortage illustrates an unusual consequence of the AI boom.
Investment in advanced computing infrastructure can strengthen one part of the technology industry while increasing costs for another.
For smartphone buyers, those pressures could eventually influence pricing, storage configurations and product availability.
However, higher memory costs do not establish that Apple will increase prices on every device.
Apple’s Holiday-Quarter Margin Warning Unsettles Investors
Apple’s outlook for the December quarter was a major focus of investor attention.
The company projected revenue growth of approximately 7%–10%.
That indicates management still expects sales to increase during the important holiday period.
However, the projected gross margin of 45%–46% was below the 47.9% recorded in the September quarter.
Services revenue growth was also forecast at approximately 8%–9%, below some analyst expectations.
These figures created concerns about the company’s ability to maintain profitability while financing new products and AI capabilities.
The warning helps explain why Apple’s shares weakened in after-hours trading despite beating quarterly revenue and earnings estimates.
A strong earnings result can still disappoint investors when forward guidance suggests additional pressure.
The market’s reaction therefore reflects expectations about future performance, not only the quarter already completed.
Services Reach a Record but Growth Expectations Moderate
Apple’s Services division generated approximately $31.57 billion in quarterly revenue.
The business includes activities such as the App Store, subscriptions, advertising, cloud services and other digital offerings.
Services are important because they produce recurring revenue from Apple’s large installed base of active devices.
The division also generally earns substantially higher gross margins than hardware.
That makes Services an important contributor to Apple’s overall profitability.
However, management expects Services revenue growth to moderate during the December quarter.
The forecast of 8%–9% was below some analysts’ projections.
For investors, the question is whether this represents a temporary slowdown or a more durable change in the division’s growth.
Apple’s ability to expand Services matters because it helps diversify the business beyond annual device upgrades.
But future growth will depend on consumer spending, product adoption, competition and the company’s ability to introduce additional valuable services.
New CEO John Ternus Faces His First Major Earnings Test
The results mark Apple’s first earnings report under John Ternus, who succeeded Tim Cook in September 2026.
The transition represents a major leadership change for a company that has spent years expanding its hardware, software and services ecosystem.
Ternus now faces the challenge of guiding Apple through another technological transition.
The company is developing AI-enabled experiences, expanding its premium-device portfolio and reorganizing product launches.
But it must also deal with rising component costs, supply constraints and growing competition.
Investors will be watching how the new chief executive balances innovation with financial discipline.
The challenge is not simply producing popular devices.
It is ensuring that product growth produces sustainable earnings and cash flow.
Ternus must also demonstrate that Apple’s AI strategy can strengthen its ecosystem without imposing disproportionate infrastructure costs.
Apple’s AI Strategy Looks Different From Its Big Tech Rivals
Some of the largest American technology companies are spending enormous amounts on data centers, computing processors and AI infrastructure.
Apple has taken a somewhat different approach.
Rather than matching the largest cloud companies’ infrastructure spending, it has emphasized integrating AI capabilities into its devices and services.
It also relies on technology partnerships and cloud infrastructure to support certain functions.
WWC ONE MEDIA examined the broader industry spending debate in Big Tech’s $750-Billion AI Gamble Shakes Wall Street as Core Businesses Slow — But Will the Spending Ever Pay Off?.
The report highlighted investors’ concerns about the cost of AI infrastructure and whether spending will generate adequate financial returns.
Apple’s approach may limit some categories of capital spending.
However, it does not eliminate AI-related expenses.
The company is investing in software development, computing capacity and the infrastructure supporting its upgraded Siri assistant.
Its earnings guidance indicates that these costs are becoming more important.
The challenge will be demonstrating that AI features improve customer loyalty, device upgrades and services revenue enough to justify the investment.
Siri’s Expansion Could Create Another Cost Challenge
Apple has been expanding Siri’s AI capabilities.
The company says its redesigned assistant is processing approximately 2.5 billion requests daily.
That level of activity demonstrates the enormous scale at which Apple must provide reliable computing services.
However, processing AI requests can involve server costs, energy use and ongoing infrastructure expenses.
The financial impact depends on the architecture used, the proportion of processing performed on devices and the efficiency of cloud systems.
Apple must therefore balance feature quality, speed, privacy and operating expenses.
AI functionality may strengthen the value of Apple devices.
But additional features are not automatically profitable simply because consumers use them frequently.
The financial benefits may emerge indirectly through device sales, subscriptions and customer retention.
For investors, the question is whether these benefits will outweigh the additional costs.
What the Results Mean for Philippine Consumers
Apple’s global earnings also have implications for Filipino customers and technology retailers.
The Philippines is part of Apple’s broader Asia-Pacific commercial ecosystem.
Demand for premium smartphones, tablets and laptops can be influenced by product pricing, financing options and household purchasing power.
Higher global memory costs could eventually influence electronics prices.
However, the latest earnings release does not establish a specific price increase for Apple products in the Philippines.
Local retail prices depend on currency movements, taxes, distribution arrangements and company pricing decisions.
For Filipino consumers considering the latest iPhone models, the relevant factors include official local pricing, warranty coverage and availability.
The iPhone Duo’s supply constraints may also affect delivery schedules in individual markets.
But global shortages should not be used to claim that every Philippine retailer is out of stock.
Separate local inventory information would be needed to support that conclusion.
What Investors Should Watch Next
Apple’s next financial results will provide more evidence about whether its growth momentum can recover.
Several factors deserve attention.
First is demand for the iPhone 18 lineup and the new foldable Duo.
Second is the performance of Greater China, where annual growth was strong but the September-quarter result missed one widely cited analyst forecast.
Third is the cost of memory components.
Higher semiconductor prices may continue reducing gross margins if Apple cannot offset them through purchasing arrangements, efficiency or product pricing.
Fourth is the growth of Services.
Recurring digital revenue remains an important source of profitability.
Finally, investors will examine whether the company’s AI initiatives generate measurable commercial benefits.
Apple’s large cash generation and established customer base provide significant financial resources.
But even the world’s largest technology companies must manage costs and expectations carefully.
The Bigger Question: Can Apple Sustain Its Record-Breaking Growth?
Apple’s November 2 earnings report presents a story of strength mixed with rising uncertainty.
Quarterly revenue reached a record $114.48 billion.
Net income exceeded $30 billion.
iPhone revenue climbed 17%.
And the company completed its strongest fiscal year on record.
Yet the results also revealed challenges.
Revenue growth slowed from the preceding quarter.
China sales fell below one major analyst forecast despite rising year on year.
iPad and wearable-device revenue disappointed.
And rising memory and AI-related costs are expected to reduce profitability during the holiday quarter.
New CEO John Ternus is now responsible for navigating these pressures while expanding Apple’s product lineup and technological capabilities.
The company’s financial strength remains substantial.
But record sales alone may not be enough to satisfy investors expecting another era of exceptional growth.
As Apple records $114.5 billion in quarterly revenue but warns of shrinking margins and disappointing China sales relative to expectations, can its premium iPhones, foldable devices and artificial intelligence strategy deliver another breakthrough — or could rising costs and intensifying competition threaten the technology giant’s next growth chapter?