
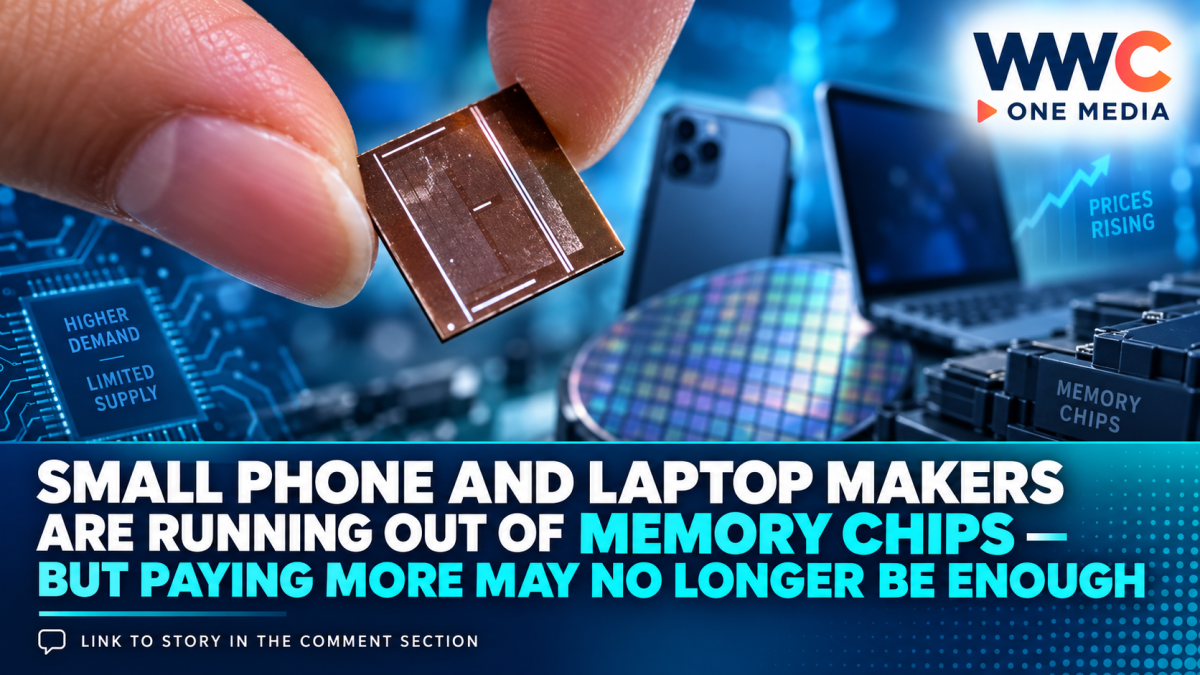
The global memory-chip crunch is forcing smaller smartphone and laptop manufacturers into survival mode, with some redesigning devices, locking in components months ahead, checking chips for counterfeits and passing higher costs to buyers as artificial intelligence infrastructure consumes an increasingly large share of the world’s memory production.
And industry executives are warning that the pressure may not disappear anytime soon.
Independent device makers interviewed by Reuters say the biggest problem is no longer simply how much DRAM or storage costs.
It is whether they can secure enough chips at all.
Dutch repairable-smartphone maker Fairphone, Finnish handset company Jolla and U.S. modular-laptop maker Framework are among the smaller manufacturers adapting their products and supply chains to a shortage they expect could continue through 2027 and beyond.
For consumers, the consequences could eventually appear in several places at once: higher prices, less memory and storage, fewer affordable devices and longer replacement cycles.
AI changed the memory market
The shortage is rooted in a dramatic shift inside the semiconductor industry.
Memory manufacturers are increasingly directing production toward components used in AI servers, particularly high-bandwidth memory, or HBM, and high-capacity server DRAM.
Those chips are essential to powerful AI accelerators and data-center systems being deployed by technology giants around the world.
That shift leaves less manufacturing capacity available for the conventional DRAM and NAND flash used in smartphones, laptops and other consumer electronics.
IDC described the situation as more than a normal semiconductor boom-and-bust cycle, saying the industry may be undergoing a strategic reallocation of wafer capacity from consumer devices toward higher-margin AI infrastructure.
Samsung Electronics, SK Hynix and Micron—the three major global DRAM manufacturers—have all been directing substantial resources toward AI-related memory products.
The economics help explain why.
AI servers can require vastly more memory than an ordinary PC or smartphone, while HBM and enterprise-grade memory can command significantly better margins.
That creates a powerful incentive for manufacturers to prioritize the data-center boom.
But every production line directed toward AI memory is capacity that cannot simultaneously be used to supply smartphones or consumer PCs.
The problem is becoming ‘allocation,’ not just price
For the largest electronics companies, higher component prices are painful but often manageable.
Companies with enormous purchasing volumes can sign long-term contracts, negotiate directly with suppliers and reserve capacity far in advance.
Smaller manufacturers have far less leverage.
Fairphone CEO Raymond van Eck summarized the problem bluntly: without an allocation from suppliers, a device maker may not have enough memory to build its products regardless of what it is willing to pay.
That is forcing smaller companies to rethink how products are engineered.
Jolla created two motherboard configurations so it could use either combined memory-and-storage packages or separate components depending on what was available.
Framework deliberately designed its laptops with replaceable memory, allowing customers in some cases to install RAM salvaged from older computers instead of purchasing new modules at elevated prices.
Framework also places non-cancellable orders far in advance despite uncertainty over the final price, delivery schedule and available quantity.
Those are not ordinary procurement decisions.
They are signs of an industry preparing for prolonged scarcity.
There is another danger: fake or recycled chips
When components become scarce and expensive, unofficial supply channels become more tempting.
That creates another problem for smaller manufacturers: verifying that the chips they buy are actually what sellers claim.
Jolla says it stress-tests samples from every incoming shipment to ensure components sold as new have not actually been refurbished and resold.
The concern highlights a less visible side effect of semiconductor shortages.
As legitimate supply becomes harder to secure, manufacturers may encounter more brokers, secondary-market suppliers and questionable inventory.
Companies therefore face two risks simultaneously: paying too much for memory—or paying too much for memory that does not meet specification.
Memory can dominate the cost of a phone
The financial pressure is particularly severe for cheaper devices.
Fairphone estimates that memory can represent almost 60% of the bill of materials for some smartphones priced around US$400 under current conditions.
IDC separately estimated that memory normally represents roughly 15% to 20% of the bill of materials for a mid-range smartphone and around 10% to 15% for premium devices, meaning sharp increases in memory prices can quickly destroy the already-thin margins of affordable models.
That leaves manufacturers with a limited menu of options:
raise retail prices, reduce memory specifications, absorb the additional cost, redesign the device—or stop selling certain low-margin products entirely.
Different companies are already choosing different strategies.
Framework changes prices relatively quickly when component costs rise.
Jolla introduced a paid memory upgrade.
Fairphone, as of Reuters’ September 16 report, had not raised prices.
But if the shortage persists, keeping retail prices unchanged becomes increasingly difficult.
Budget smartphones could take the biggest hit
The wider smartphone market is already feeling the effects.
Counterpoint Research forecast global smartphone shipments to decline 13.9% in 2026 to approximately 1.08 billion units, which would represent the steepest annual decline in its records.
The firm identified the memory supply crisis as the primary driver, with lower-priced devices facing particularly severe pressure.
Counterpoint said production of some older, low-cost memory types has fallen sharply as suppliers prioritize more profitable technologies, putting the sub-US$150 smartphone segment under especially intense strain.
That matters because budget smartphones dominate many emerging markets.
Consumers who previously benefited from more RAM, larger storage capacities and increasingly powerful processors at falling prices may instead face the reverse trend: higher prices for devices with fewer upgrades.
IDC similarly warned that the long-running tendency for flagship specifications to migrate into cheaper smartphones is being disrupted by memory costs.
Laptop makers are under pressure too
The squeeze is not limited to phones.
TrendForce said persistent increases in DRAM and SSD prices continue to push up notebook-manufacturing costs even as CPU availability improves.
It forecasts global notebook shipments to decline 9.4% in 2026.
More strikingly, TrendForce estimated that CPUs, DRAM and SSDs together represented around 68% of the bill of materials of a representative mainstream notebook in the third quarter of 2026, compared with approximately 45% in the first quarter of 2025.
Manufacturers have been using older inventory and advance purchases to delay the impact on consumers.
But those buffers eventually run out.
When they do, brands may have little choice but to raise prices, accept lower profit margins or reduce specifications.
The price surge has slowed—but the shortage has not
There is at least one piece of slightly better news.
The rate at which memory prices are increasing has slowed sharply from the extraordinary jumps recorded earlier this year.
TrendForce expects conventional DRAM contract prices to rise around 13% to 18% this quarter, compared with increases approaching 100% during the first quarter.
But slower price inflation does not mean the underlying shortage has disappeared.
It only means the market is no longer deteriorating at the same explosive pace.
Jolla CEO Sami Pienimäki told Reuters he does not expect supply conditions to truly normalize until around 2028.
And some of the world’s biggest memory manufacturers are even more cautious.
SK Hynix says 2027 could be the worst year yet
SK Hynix CEO Kwak Noh-jung warned in July that 2027 could become the worst year in the memory industry’s history from a supply perspective.
He said customer demand is continuing to rise faster than the company can expand production and predicted demand could remain above SK Hynix’s supply capacity even beyond 2030.
UBS has also projected that the global DRAM market could remain undersupplied until at least the second quarter of 2028.
TrendForce’s outlook points in a similar direction.
It expects AI to remain the major driver of memory demand in 2027, with strong HBM consumption and continued AI-server deployment keeping DRAM supply tight.
The research firm expects NAND flash conditions to become somewhat easier during the second half of 2027, but says that would provide only limited relief for smartphones because mobile DRAM would remain expensive and constrained.
Why building more factories will not fix the problem overnight
Samsung, SK Hynix, Micron and other manufacturers are investing heavily in new capacity.
But semiconductor factories take years and billions of dollars to build, equip and qualify.
SK Hynix and Samsung are involved in a massive South Korean plan to expand memory production, while SK Hynix is also investing in facilities including advanced packaging capacity in the United States.
Micron has similarly announced major long-term investment plans tied to growing AI memory demand.
Those projects could eventually ease the shortage.
But smartphones and laptops being designed today need memory now—not several years from now.
That timing mismatch explains why manufacturers are preparing for another difficult year even as suppliers announce enormous new investments.
AI’s success is becoming consumer electronics’ problem
The memory shortage reveals one of the less obvious consequences of the global AI boom.
Artificial intelligence is not just driving demand for Nvidia GPUs or massive data centers.
It is competing with ordinary electronics for some of the same semiconductor manufacturing resources.
IDC estimates that DRAM and NAND supply growth in 2026 will remain below historical levels at approximately 16% and 17% respectively, even as AI-related memory demand continues to accelerate.
That competition creates a hierarchy.
Big cloud operators and premium electronics manufacturers can often secure long-term supply.
Smaller brands, especially those selling affordable hardware, are pushed toward the back of the line.
And that could ultimately reshape which devices consumers are able to buy.
What consumers should watch next
The most visible sign of the shortage may not be empty shelves.
Instead, buyers could begin seeing phones and laptops that cost more while offering less memory than they might have expected only a few years ago.
Manufacturers may also keep older configurations alive longer, delay memory upgrades, use modular designs or increasingly rely on secondary components where quality can be verified.
Premium brands with purchasing power will likely have more room to absorb the disruption.
Smaller manufacturers will have to improvise.
And unless AI-related memory demand cools sharply or new semiconductor capacity arrives faster than expected, that divide could widen.
For years, consumers became accustomed to getting more RAM, more storage and faster hardware for roughly the same money.
The AI boom may now be putting that era on hold—and smaller phone and laptop makers are discovering that the biggest challenge is no longer finding cheap memory, but finding memory at all.
Leave a Reply