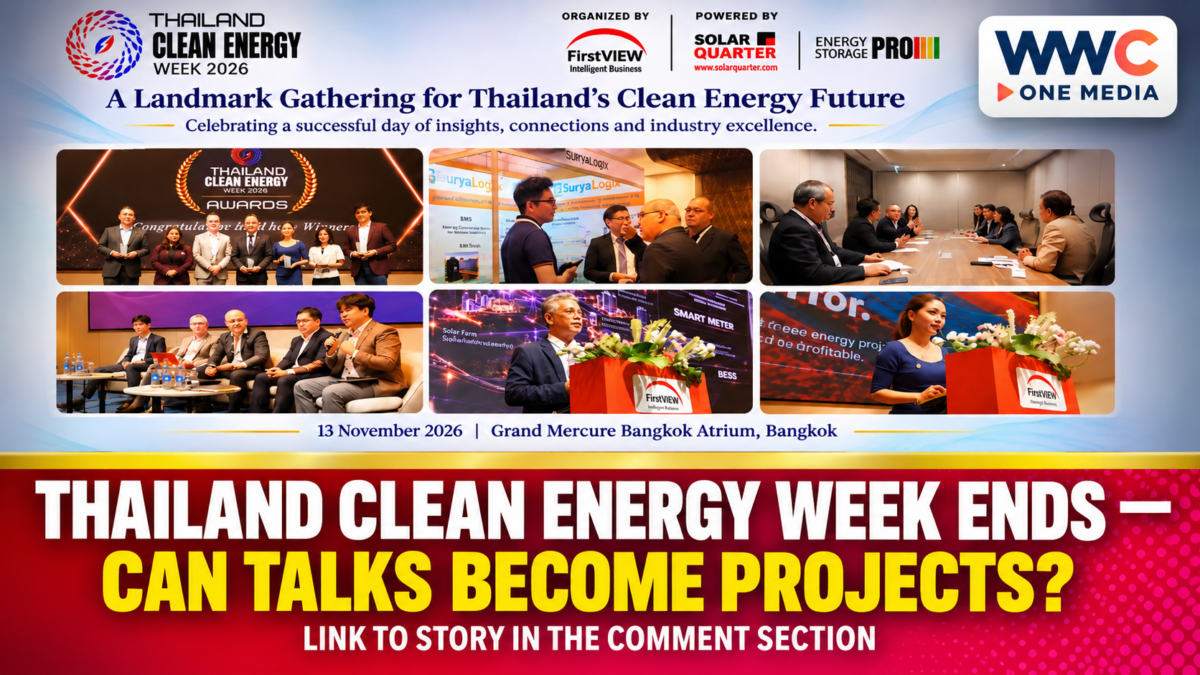
BANGKOK, Thailand — Thailand Clean Energy Week 2026 took place on Nov. 13, bringing energy-sector stakeholders together to examine renewable power, battery storage, electricity networks and investment opportunities. The Bangkok gathering came as Southeast Asian governments faced mounting pressure to turn clean-energy ambitions into functioning infrastructure.
The event provided a forum for discussions about technologies and policies shaping Thailand’s electricity sector. But the larger economic question is whether regional dialogue can help overcome the financing, regulatory and technical obstacles that often separate proposed renewable-energy projects from actual electricity generation.
For businesses, investors and households, that distinction matters more than the number of conferences held or commitments discussed.
Thailand Clean Energy Week Highlights the Implementation Challenge
Thailand Clean Energy Week 2026 built on the earlier Solar Week Thailand format while widening its focus to include battery energy storage systems, smart grids, electric mobility, industrial decarbonisation and green finance.
The Future Energy Storage & System Integration Alliance (FESSIA), an event-supporting organisation, confirmed the Nov. 13 gathering and identified renewable-energy integration among its main subjects.
Its event programme included a discussion on scaling utility-scale renewable generation and storage to strengthen Thailand’s energy security. FESSIA also identified its chief strategy officer, Mark Hutchinson, as a participant in that session.
These subjects point to an important shift in the clean-energy conversation.
Installing additional solar panels is only one part of the transition. Electricity systems must also accommodate variable renewable output, maintain reliable service and provide sufficient network capacity to support new power plants.
What this could mean: Industry discussions may help identify practical obstacles and potential commercial partnerships, but their economic value depends on what participants do after the event.
The available event-partner record does not establish that the conference itself resulted in a completed investment agreement, an awarded power contract or newly commissioned generating capacity.
Battery Storage and Grid Reliability Take Centre Stage
One of the central challenges facing renewable-energy expansion is the difference between installed generating capacity and electricity available when consumers need it.
Solar plants generate power when sunlight is available. Their output changes with weather conditions and the time of day.
Battery energy storage systems can absorb electricity during periods of generation and release stored power later, depending on their technical configuration and operating requirements.
However, batteries do not create additional primary energy. They must be charged, and their usefulness depends on storage duration, capacity, efficiency and grid conditions.
For Thailand, combining renewable generation with storage raises questions about transmission connections, project financing and the rules governing electricity purchases.
Similar issues are visible in the Philippines.
WWC ONE MEDIA previously examined Philippine energy projects entering the grid-study process, illustrating why proposed power capacity must undergo technical assessment before it can become operational.
The broader lesson is that adding renewable capacity requires coordinated investment in generation, storage and electricity networks.
Without those supporting systems, announcements about future power supply may move faster than actual electricity deliveries.
ASEAN’s Renewable Energy Targets Raise the Stakes
Thailand’s energy transition is part of a wider regional effort.
ASEAN energy ministers endorsed the ASEAN Plan of Action for Energy Cooperation 2026–2030 in October 2025, establishing a framework for regional energy collaboration.
The plan includes collective aspirational targets for 2030:
- Renewable energy supplying 30% of total primary energy.
- Renewable sources representing 45% of installed power capacity.
- A 40% reduction in energy intensity against the 2005 baseline.
These are regional objectives rather than binding project-delivery commitments by individual conference participants.
The Ninth ASEAN Energy Outlook, launched in October 2026, adds another measure of the challenge.
It estimates that reaching the regional renewable-capacity target would require approximately 26 gigawatts of additional renewable capacity annually through 2030, around four times the historical deployment pace examined in the report.
That finding helps explain why discussions about financing, network development and operational reliability are increasingly important.
Clean-energy expansion is not simply a question of technology availability. It requires coordination among policymakers, electricity companies, lenders, developers and customers.
Why Corporate Electricity Buyers Matter
Businesses seeking renewable electricity face a different calculation from households installing solar panels.
Industrial users must evaluate energy consumption, operating schedules, contract duration and the reliability of their electricity supply.
A rooftop solar installation may reduce daytime grid purchases, but the financial outcome depends on equipment costs, electricity tariffs, consumption patterns and applicable regulations.
WWC ONE MEDIA has separately examined Thailand’s planned rooftop solar support programme, providing context for how government policy can influence household adoption.
The existence of a support proposal, however, should not be confused with confirmation that every announced measure has been implemented or that consumers have received financial assistance.
For larger businesses, renewable electricity procurement may involve direct supply contracts, self-generation or other arrangements permitted by local market rules.
Why it matters: Predictable regulations and commercially workable contracts could make renewable-energy investment more attractive. But lower electricity costs cannot be guaranteed simply because a company adopts solar technology.
The Philippines Faces a Similar Regional Test
For Philippine energy companies, Thailand’s discussions reflect challenges already emerging across Southeast Asia.
Renewable-energy projects need financing, access to suitable sites, transmission capacity and technical approvals before they can supply customers.
Small island electricity systems face additional difficulties because they may depend on isolated networks and fuel deliveries.
WWC ONE MEDIA previously examined regional cooperation on island solar power and battery storage, highlighting why proposed partnerships require detailed implementation plans.
The ASEAN energy framework provides opportunities for cooperation, including renewable-energy development, electricity connectivity and stronger regional planning.
Yet cooperation does not automatically produce commercially viable projects.
Investors still need to understand construction costs, revenue arrangements, operating risks and potential delays before committing capital.
For Philippine firms studying other ASEAN markets, Thailand may offer useful lessons in how power-sector rules affect investment decisions.
What Happens Next
Thailand Clean Energy Week 2026 has concluded, but the business questions raised by its agenda remain unresolved.
The next meaningful indicators will be identifiable project announcements, financing agreements, regulatory decisions, grid-connection arrangements and commissioned power capacity.
Conference discussions may create opportunities for future cooperation. They should not be counted as new investment or electricity supply until subsequent records establish those outcomes.
For Thailand and its ASEAN neighbours, the real measure of progress will be whether renewable energy becomes easier to finance, connect and operate while electricity remains dependable.
The challenge is no longer simply building enthusiasm for clean power. It is converting long-term ambitions into practical electricity infrastructure.