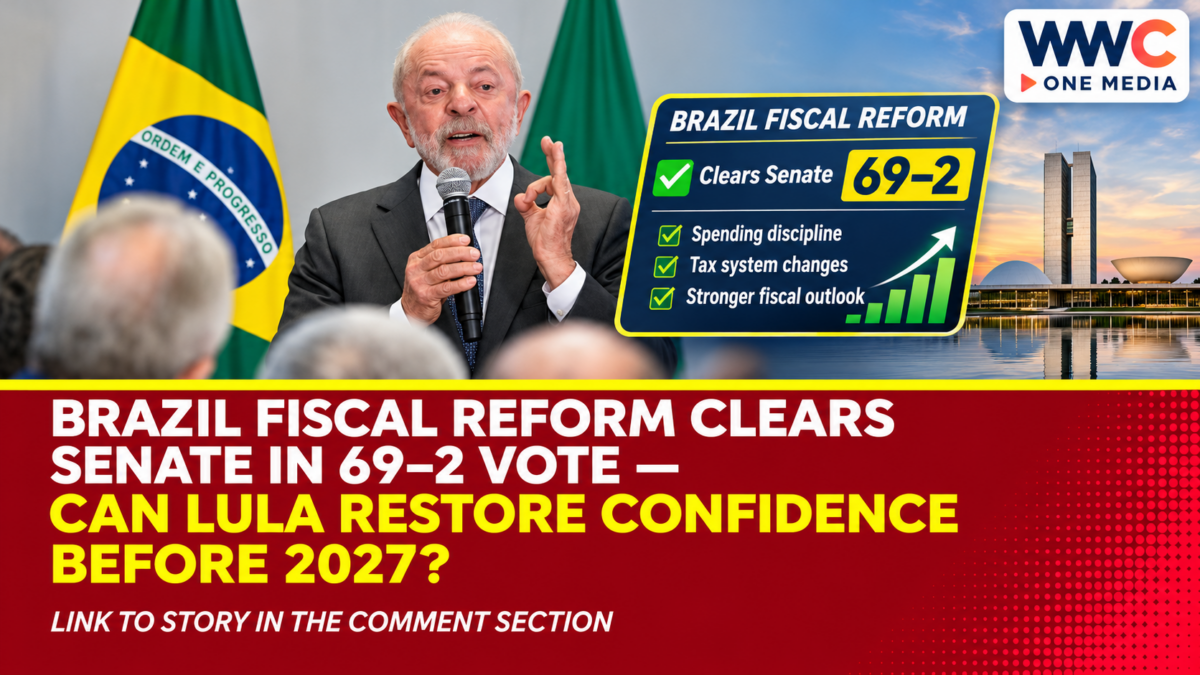
BRASÍLIA, Brazil — Brazil’s Senate completed approval of a fiscal adjustment bill on Nov. 18, 2026, giving President Luiz Inácio Lula da Silva’s government a legislative advance as it seeks greater control over public expenditure and tax concessions. The revised Complementary Bill PLP 299/2026 passed a supplementary vote by 69 votes to two and now heads to the Chamber of Deputies, where its provisions remain subject to further consideration.
The result is a significant vote, not a completed fiscal repair. Whether the measures improve the 2027 budget will depend on the final law, implementation and what the government actually collects or saves.
Brazil Fiscal Reform Advances but Is Not Yet Law
The Senate initially approved the bill’s main substitute text on Nov. 12 by 45 votes to 31. That version was prepared by Senator Eduardo Braga from a proposal introduced by Senator Jaques Wagner at the executive government’s request.
On Nov. 18, senators resolved outstanding challenges, considered another set of amendments and completed the supplementary round. The revised measure now requires action in the Chamber of Deputies; Senate approval alone does not amend Brazil’s fiscal framework.
The difference matters to anyone reading an announced government saving as money already secured. A projected fiscal benefit is an estimate conditional on legislation and execution, not a cash inflow at the time of a parliamentary vote.
WWC previously examined the administration’s original proposed fiscal rescue package. The updated Senate text deserves its own scrutiny because the initial discussion of possible savings does not necessarily describe every provision retained after negotiation.
Spending Controls and Tax Benefits Form the Core
The approved Senate approach adjusts the federal sustainable fiscal framework established by Complementary Law 200 of 2023. It would give the executive additional ways to withhold budgeted expenditure in pursuit of its fiscal target.
The earlier Senate-approved substitute would restrict spending growth above inflation to 2% in years when additional restraint applies, rather than the framework’s existing 2.5% upper limit. The restriction would apply to that year, without automatically resetting the calculation base for later years.
On the revenue side, the proposal addresses tax concessions, including exemptions and special regimes, and permits tighter restrictions on certain tax-credit offsets. The Senate’s explanation identified exceptions for selected incentives, including parts of the information technology and semiconductor industries and specified vehicle purchases for people with disabilities.
These details are economically different from a universal tax increase. Limiting a concession can increase receipts from some taxpayers while leaving other programmes untouched. The final text and subsequent regulations will determine which transactions are affected.
How Much Could the 2027 Budget Gain?
A Senate legislative analysis prepared before the final vote recorded an executive estimate of R$43 billion to R$54 billion in improvement to the 2027 primary balance. It also described a separate R$100 billion estimated increase in room under Brazil’s constitutional borrowing restriction known as the golden rule.
The two measures should not be added together. One concerns the primary budget balance, which excludes interest payments; the other relates to the borrowing framework and financing room. Neither is a verified final saving from the amended bill.
The preliminary analysis broke out mechanisms such as greater expenditure restraint, restrictions on tax-credit compensation and reduced tax expenditure. These figures are planning estimates, and the amendments accepted during the final November session may affect their application.
Analysis: Credible fiscal adjustment depends less on a large headline estimate than on whether measurable savings and collections materialise. Budget forecasts must eventually be reconciled with published execution reports.
Senate Compromises Show the Political Trade-Off
On Nov. 18, senators considered 15 supplementary amendments. The rapporteur accepted two in full and one in part, alongside drafting adjustments.
One accepted change shortened the proposed period for Congress to regulate public-sector pay ceilings from 120 days to 60 days after publication of the eventual law. Another would require the executive to explain its fiscal performance publicly if the prior year’s central-government primary result fell below 0.5% of gross domestic product.
The Senate also debated provisions concerning the timing of certain payments and the government’s power to restrict the use of recognised tax credits. Such debates show that the cost and design of fiscal restraint remain politically contested.
A vote in favour of an overall package does not demonstrate unanimous support for every policy choice. Nor does the result establish that fiscal spending cuts will have identical consequences for every public service.
Why Debt and Interest Rates Still Matter
Reducing primary deficits can moderate a government’s need to borrow, but it does not instantly eliminate outstanding debt or interest obligations. Financing costs, growth and inflation also influence the longer-term trajectory of public finances.
WWC has discussed Brazil’s interest-rate dilemma following Lula’s reelection, which provides context for why budget credibility matters to monetary policy. Fiscal legislation by itself does not direct the central bank to cut its policy rate.
The operating environment matters for banks and borrowers as well. WWC’s report on Banco do Brasil’s agricultural lending pressures examined credit risks affecting one important financial institution. Those corporate exposures should not be confused with a quantified effect of this Senate bill.
What this could mean: If implemented, stronger budget controls may improve perceptions of fiscal discipline. But the size and persistence of any economic benefit will depend on future fiscal data, not the Senate vote alone.
What Happens Next
The Chamber of Deputies must examine PLP 299/2026, and further amendments could require additional legislative steps before presidential action. Until a final law takes effect, its projected savings and modified rules remain proposals.
Investors and taxpayers should monitor the version the lower house considers, the publication of any enacted law and the government’s subsequent 2027 budget execution reports. Those records will show whether the political compromise produces measurable fiscal adjustment.
The main achievement so far is legislative: the Senate moved the package forward. The harder test is whether Brazil can translate that vote into sustained budget improvement without treating forecasts as accomplished results.
Frequently Asked Questions
Did Brazil’s Senate approve Lula’s fiscal reform?
Yes. The Senate completed its vote on Nov. 18, 2026, approving the revised proposal by 69 votes to two in a supplementary round. It still needs consideration in the Chamber of Deputies.
Is Brazil’s fiscal adjustment already law?
No. The Senate-approved measure is a bill, and further legislative and formal steps are required before its provisions take effect.
How much could Brazil save in 2027?
A pre-final-vote Senate analysis cited an estimated R$43 billion–R$54 billion improvement in the primary balance. It is not a verified outcome or necessarily the final fiscal impact after amendments.
What would the bill change?
The proposals involve tighter options for spending restraint, adjustments to tax benefits and tax-credit compensation, and rules affecting the fiscal framework and public-sector remuneration.
Will Senate approval lower Brazilian interest rates?
Not automatically. Interest-rate decisions depend on monetary policy, inflation and economic conditions, even when government fiscal policy changes.