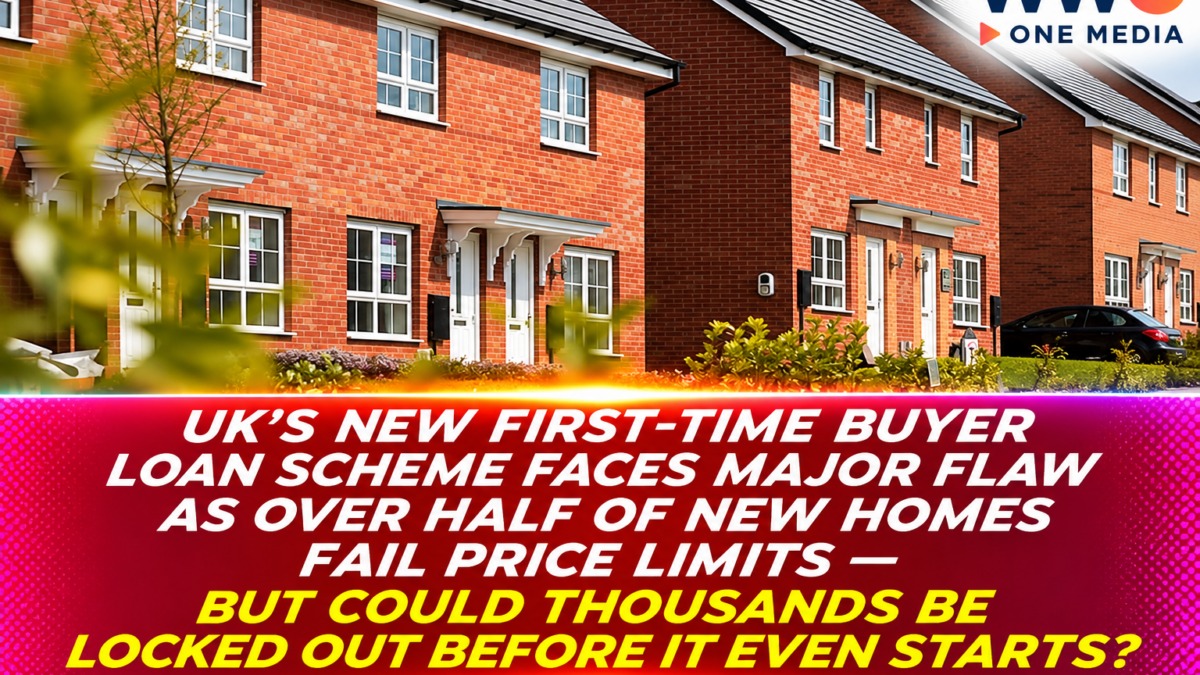
LONDON, UNITED KINGDOM — November 10, 2026 — Britain’s ambitious plan to help aspiring homeowners purchase property with deposits as low as 2.5% is facing a serious affordability problem before its launch, as new research reveals that many newly built houses are already too expensive to qualify for government assistance.
The Labour government’s Your First Home scheme was designed to provide a lifeline to households struggling to save for their first property.
But the policy’s strict local price limits could prevent thousands of eligible buyers from purchasing the homes they actually need.
According to research highlighted by Bloomberg and independently reported by British newspapers, only 47% of newly built homes sold in England during 2025 would have qualified under the scheme’s proposed price caps.
That means approximately 53% would have been excluded based on property prices alone.
A separate analysis by property website Zoopla suggests the situation could be particularly difficult for families seeking larger homes.
In southeast England, approximately 70% of newly built three-bedroom homes could exceed the relevant price limits.
The findings have created fresh concern among housing developers, property experts and first-time buyers who had hoped the program would finally bring homeownership within reach.
The central problem is that government support may reduce the amount buyers need to borrow, but it cannot help them purchase a property that is excluded from the scheme altogether.
Britain’s 2.5% Deposit Promise Meets an Expensive Housing Market
Prime Minister Andy Burnham announced Your First Home in September 2026 as part of efforts to address Britain’s worsening housing affordability crisis.
The program was confirmed in the October Budget, with applications expected to open in February 2027 and the first government equity loans scheduled for April.
The scheme is restricted to qualifying first-time buyers purchasing newly built homes in England from participating developers.
Under its main provisions, buyers can use a minimum deposit of 2.5% of the purchase price and a government equity loan equivalent to 20%.
The remaining 77.5% can be financed through a repayment mortgage.
For example, a buyer purchasing an eligible £300,000 property could finance the transaction through:
- Personal deposit: £7,500.
- Government equity loan: £60,000.
- Repayment mortgage: £232,500.
Without the government scheme, someone using a conventional 95% mortgage would generally need a £15,000 deposit and a £285,000 mortgage for the same property.
The arrangement could significantly reduce the initial savings required and lower mortgage repayments during the first five years.
However, the smaller deposit does not eliminate the need to qualify for a mortgage.
Lenders will continue evaluating income, affordability, credit history and repayment capacity.
The government loan must also eventually be repaid.
More Than Half of New Homes Could Be Excluded
Research by Connells Group found that only 47% of new-build homes sold across England in 2025 would have fallen below the relevant local price caps.
The analysis raises questions about whether the scheme can reach the number of prospective homeowners the government intends to support.
Eligibility varies considerably between regions.
In London, approximately 58% of new-build sales would have qualified under the proposed limits.
In the southwest and northeast, the eligible share was closer to 40%.
Even within the capital, the differences were substantial.
Some local authority areas had a much greater proportion of homes below the threshold than others.
This creates an uneven housing market in which an eligible first-time buyer may find relatively many qualifying properties in one district but almost none in another.
The program’s effectiveness will therefore depend not only on household income but also on where people want or need to live.
Three-Bedroom Homes Face a Particularly Severe Problem
For growing families, the affordability gap may be even wider.
Zoopla estimates that approximately 70% of newly built three-bedroom homes in southeast England would be priced above their relevant local caps.
This is significant because a first-time buyer does not necessarily mean a young person purchasing a small apartment.
Some first-time buyers are couples with children or households seeking enough space for future family needs.
The restrictions could force those households to choose smaller properties, consider different locations or delay buying altogether.
London faces similar challenges.
Zoopla found that only about 32% of newly built two-bedroom flats advertised in London were below the relevant limits.
By contrast, smaller one-bedroom properties were much more likely to qualify, particularly in outer London.
The mismatch raises a critical policy question.
Is the government’s program designed to help households purchase a suitable long-term home, or will it mainly encourage the purchase of smaller properties that fit the financing rules?
How Much Can a Home Cost Under the New UK Scheme?
Your First Home uses local property-price limits rather than one national ceiling.
The government says these caps are intended to reflect the typical cost of homes purchased by first-time buyers in each area.
Examples include:
- Inner London: up to £650,000.
- Outer London: up to £500,000.
- North Lincolnshire: approximately £215,000.
Other local authority areas have different thresholds.
But property prices can vary sharply within the same region.
An area with expensive newly built developments may offer very few qualifying choices.
Research by SAM Conveyancing, separately reported by The Independent, found that the local eligibility limits were below the average new-build price in 264 of 285 local authorities examined.
The company estimated that fewer than one-third of properties in its assessed sample would qualify.
That estimate differs from Connells Group’s 47% figure because the researchers used different datasets, periods and methods.
The results should not be treated as contradictory measurements of exactly the same property population.
Nevertheless, both studies point to the same concern: many new homes could be excluded by the limits.
Oxford and London Illustrate the Affordability Gap
Some of the most striking examples come from expensive housing markets.
According to SAM Conveyancing’s analysis, none of the 66 newly built homes sold in Oxford over its two-year study period fell below the area’s £415,000 cap.
The average price of those homes was approximately £777,867.
In Worthing, the research identified only one qualifying property among 90 sales.
The town’s £300,000 limit was substantially below its typical new-build price of approximately £409,472.
In some central London boroughs, fewer than 6% of assessed new-build sales met the relevant thresholds.
These findings illustrate how a household might qualify financially for assistance but still be unable to find an eligible property.
However, the government has challenged some interpretations of the research.
Officials argue that studies examining all new-build sales may include larger or more expensive homes that typical first-time buyers would not ordinarily purchase.
The government says the caps were designed specifically to focus support on modest starter properties.
That is an important distinction.
The scheme was not intended to subsidize every newly built home in England.
The policy question is whether the eligible supply is large enough to meet realistic demand from its intended buyers.
Income Limits Add Another Layer of Eligibility
The program also places restrictions on household income.
Under official government guidance, applicants generally must have annual household earnings no greater than:
£110,000 outside London, or £140,000 within London.
Buyers must also be first-time homeowners purchasing an eligible new-build property as their main residence.
They must obtain financing from a participating mortgage lender and meet the other applicable eligibility requirements.
The income limits are intended to ensure public money is directed toward households that need assistance.
But income eligibility alone does not establish affordability.
A family with earnings below the ceiling may still struggle with mortgage payments, living expenses or other debts.
Conversely, some households with substantial earnings below the limit may have different financial circumstances from lower-income applicants.
The affordability test remains important because a smaller initial deposit does not necessarily mean a home is inexpensive to own.
The Government Loan Is Interest-Free for Five Years — But Not Forever
One of the program’s biggest attractions is its initial interest-free period.
The government equity loan carries a 0% interest rate during the first five years.
Interest is then scheduled to increase.
Under the published arrangements:
- Years 1–5: 0%.
- Year 6: 1.5%.
- From Year 7: 3%.
The government provides an illustrative example involving a £300,000 home and a 30-year repayment mortgage with a 5% mortgage rate.
Under those assumptions, a buyer using Your First Home would pay approximately £1,248 per month during the first five years.
The example payment would rise to approximately £1,323 in year six and £1,398 from year seven, assuming no repayment of the equity loan and unchanged illustrative mortgage conditions.
The example excludes other homeownership expenses, including insurance, council tax, maintenance and certain service charges.
The actual financial impact will depend on each buyer’s mortgage terms and future interest rates.
Crucially, the government loan is an equity loan, not a cash grant.
The amount repayable is linked to the relevant equity share of the property’s value, subject to the scheme’s rules.
If the home’s value increases, the amount required to repay the equity loan may also rise.
That means buyers must understand both the immediate savings and the long-term obligations.
A £4.7 Billion Program Faces Questions Over Its Reach
The government has allocated £4.7 billion over five years to support Your First Home.
Officials hope the program will assist approximately 70,000 first-time buyers.
The funding allocation includes £700 million for 2027–2028 and £1 billion annually in subsequent years.
The government also plans to charge participating developers fees that can reach 4% of the sale price, depending on the applicable arrangements.
Those charges are intended to help fund the program.
But developers have raised concerns that participation could become less attractive when combined with existing construction costs and price limits.
Builders may find it difficult to offer homes below the caps while also paying participation fees and maintaining commercially viable returns.
This is especially challenging in expensive locations where land, labor and construction materials already cost more.
A government loan designed to stimulate homebuilding could therefore have limited impact if builders struggle to produce qualifying properties profitably.
Britain’s Housebuilders Face a Difficult Market
The housing scheme arrives during a period of weakness in the UK property market.
According to Halifax data reported in November, average UK house prices fell 0.6% in October to approximately £296,285.
That represented the steepest monthly decline in more than three years.
Average values were also approximately 1.2% lower than a year earlier.
Mortgage financing has remained expensive, with some average fixed-rate products close to 6%.
Higher borrowing costs reduce the amount buyers can comfortably repay each month.
That can discourage property purchases even when prices begin falling.
Meanwhile, developers face elevated construction expenses, regulatory requirements and difficulties securing suitable land.
The combination has made it increasingly difficult to build homes that buyers can afford while preserving reasonable margins.
The new government scheme is intended to support both buyers and developers.
But analysts warn that boosting the availability of mortgage credit cannot solve every underlying problem in the housing market.
Could the Scheme Push House Prices Higher?
Some economists have questioned whether demand-focused housing subsidies could ultimately encourage higher property prices.
When government assistance allows buyers to borrow more, it can increase demand.
If the number of available homes does not expand sufficiently, sellers and developers may gain greater pricing power.
That could reduce the affordability benefits the program was intended to provide.
Reuters Breakingviews has argued that Britain’s housing problems are rooted partly in insufficient construction and planning restrictions rather than simply a lack of mortgage financing.
From this perspective, increasing home supply may be more effective over the long term than encouraging buyers to take on larger financial commitments.
However, supporters of Your First Home argue that improving demand for newly built properties could give developers greater confidence to begin construction.
If the policy stimulates additional building, it may help address supply shortages.
Both outcomes are possible.
The decisive factor will be whether the program produces a meaningful increase in suitable housing supply rather than only changing how existing demand is financed.
The Philippines Faces a Different Version of the Same Housing Challenge
Britain’s experience offers an interesting comparison for the Philippines, where housing affordability and access to financing remain major concerns.
The two countries have different property markets, regulations and income conditions.
However, both face the challenge of matching housing finance with properties that ordinary households can realistically purchase.
In the Philippines, the Pag-IBIG Fund has partnered with private developers to expand housing options and improve access to loans.
As WWC ONE MEDIA reported on Pag-IBIG’s partnership with SM Development Corporation and the availability of housing loans of up to ₱10 million for qualified borrowers, the amount a buyer may borrow depends on eligibility and repayment capacity.
A higher advertised loan limit does not automatically make a property affordable.
In another report, WWC ONE MEDIA examined the opening of a major Mindanao housing fair featuring over 20,000 properties and promotional financing arrangements.
These initiatives demonstrate how governments and developers try to narrow the gap between household purchasing power and property prices.
But financing assistance must be matched with suitable homes, realistic monthly payments and sustainable long-term debt obligations.
Singapore Shows Another Approach to First-Time Homeownership
Other Asian housing systems provide additional comparisons.
Singapore uses a large government-supported housing framework in which qualifying households can apply for subsidized public flats.
In November 2026, Singapore’s Housing and Development Board launched 7,964 Build-To-Order flats under revised income-eligibility rules.
As WWC ONE MEDIA reported on Singapore’s latest BTO launch and its higher income ceilings, the system combines eligibility requirements, housing supply and various assistance programs.
Singapore’s model differs significantly from Britain’s equity-loan approach.
It cannot be assumed that one system would work identically in the other country.
Nevertheless, the comparison highlights the importance of coordinating financial support with the actual availability of qualifying properties.
If governments expand borrowing assistance without ensuring that suitable homes exist, many aspiring buyers may still be unable to purchase.
Property Developers Could Face More Pressure
One of the risks facing Britain’s housing policy is that developers may respond by concentrating on smaller, lower-priced properties.
That could increase the supply of eligible starter homes.
But it may also limit choices for families requiring more space.
Alternatively, some builders may decide not to participate if the financial returns are unattractive.
The broader commercial challenge resembles issues experienced by developers elsewhere.
In the Philippines, rising residential inventory and cautious homebuyers have forced several major property companies to adjust their strategies.
As WWC ONE MEDIA examined in its reporting on approximately 9,000 cancelled Metro Manila condominium purchases and 82,900 unsold units, financing difficulties and mismatches between buyer demand and available housing can complicate development plans.
These Philippine figures concern a separate market and should not be interpreted as evidence of identical conditions in Britain.
But they reinforce a common business reality: building more properties does not guarantee successful sales if the homes do not match household affordability and preferences.
What First-Time UK Homebuyers Should Check Before Applying
Prospective buyers interested in Your First Home should focus on several practical conditions.
They need to confirm that the property is newly built and offered by a participating developer.
They must check the relevant local price cap and household income ceiling.
They also need to understand the total borrowing structure, including their mortgage and government equity loan.
The initial 2.5% deposit is only one part of the financial commitment.
Buyers may face additional expenses related to conveyancing, insurance, property maintenance, taxes and service charges.
They should also account for the equity loan’s interest charges after the initial five-year period.
Because the loan is linked to a share of the property’s value, future repayment costs may change with the market value of the home.
Applications are expected to open in February 2027, with the first loans scheduled for April.
The government has said further information about participating lenders and developers will be published before applications begin.
What Happens Next for Britain’s Housing Rescue?
The coming months will determine whether the government adjusts the scheme or proceeds with its existing limits.
Property developers will be assessing whether they can produce qualifying homes at commercially viable prices.
Mortgage lenders will need to prepare their systems and assess demand.
Housing researchers will continue examining how many properties fall below the local caps.
For the government, the key test will be whether the program helps eligible households purchase homes that meet their needs.
For builders, success will depend on whether stronger demand translates into profitable construction activity.
And for aspiring homeowners, the decisive question is whether they can find an eligible property in the location where they want to live.
A program that reduces deposit requirements may still deliver disappointing results if the number of suitable homes remains limited.
The Bigger Picture: Britain’s Housing Crisis Cannot Be Solved by Loans Alone
The Your First Home scheme offers an attractive proposition.
A deposit of just 2.5%, combined with a 20% government equity loan, could lower one of the biggest barriers facing first-time buyers.
But the latest research reveals a potentially serious weakness.
More than half of new-build homes sold in England in 2025 would have exceeded the proposed local price caps, according to Connells Group.
Other studies suggest even fewer properties would qualify in some expensive local markets.
For families seeking larger homes, the restrictions may be particularly severe.
Meanwhile, high mortgage rates, construction costs and weak housing-market confidence continue complicating the outlook.
The government maintains that its limits are designed to target assistance toward modest properties rather than subsidize expensive homes.
That objective is understandable.
But the policy’s success will depend on whether enough suitable homes are actually available.
Britain is preparing to spend £4.7 billion helping first-time buyers onto the property ladder. But if so many newly built homes are already too expensive to qualify, will the scheme finally make homeownership possible for thousands of families—or become another costly housing policy that leaves the most frustrated buyers still locked out?