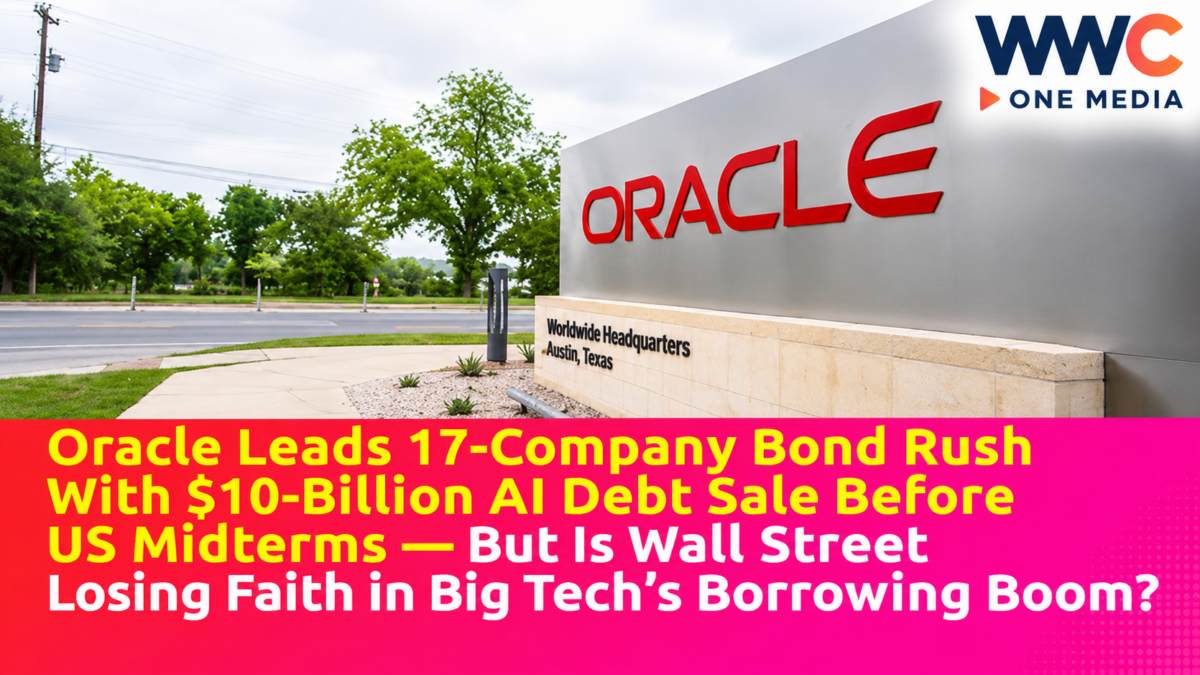
NEW YORK / MANILA — November 3, 2026. Corporate America is rushing to secure financing before a politically sensitive week, with Oracle Corporation leading 17 companies into the United States investment-grade bond market as investors prepare for the November 3 midterm elections and another potentially important round of economic data.
The November 2 wave marked the busiest day for new high-grade bond issuers since September, according to Bloomberg.
At the center of the activity is Oracle, which launched a $10-billion senior bond offering alongside a separate $10-billion common-stock offering as it continues an extraordinary expansion of artificial intelligence and cloud-computing infrastructure.
The fundraising underscores how aggressively major technology companies are seeking capital to build data centers, purchase computing equipment and meet the expected demand for AI services.
But investors are becoming increasingly selective.
Oracle’s shares fell sharply on Monday, while bond buyers demanded higher yields to compensate for risks associated with the company’s large borrowing commitments.
The latest financing activity also reflects a broader trend: American companies are moving quickly to take advantage of relatively favorable market conditions before election uncertainty and new economic data potentially increase volatility.
As Oracle and 16 other corporations rush to tap the bond market, the question is whether the wave signals confidence in America’s investment outlook — or growing financial pressure from an AI infrastructure boom that could become more expensive to sustain.
Oracle Leads 17 Companies Into the Bond Market
Bloomberg reported that 17 companies entered the US investment-grade bond market on November 2.
That represented the largest number of issuers appearing in a single day’s deal pipeline since September.
Companies reportedly marketing bonds included Oracle, Carrier Global, Otis Worldwide, Cheniere Energy, American Electric Power-related entities, Textron, Eastman Chemical and Hyatt Hotels.
The borrowers represent a broad range of industries.
They include cloud computing, manufacturing, energy, transportation-related equipment, chemicals and hospitality.
That diversity is important.
Although Oracle attracted the most attention because of its AI spending, the overall wave was not exclusively a technology financing event.
Some companies were seeking funding for general corporate activities, while others were taking advantage of a window in which borrowing conditions appeared attractive.
Bond-market participants had previously estimated that US investment-grade issuance could reach approximately $45 billion for the week.
However, that was a forecast for the broader weekly market, not the confirmed amount issued by the 17 companies on Monday.
The final borrowing totals depend on the pricing and completion of individual offerings.
Why Companies Rushed to Borrow Before the Midterm Elections
Timing is a major part of the story.
The United States holds its midterm elections on November 3, creating uncertainty about the future balance of power in Congress.
Investors are monitoring potential implications for taxation, government spending, regulation and broader economic policy.
The election is followed by additional scheduled economic releases that could influence expectations for interest rates.
Corporate borrowers often prefer to issue debt when financial markets are relatively stable.
A rise in volatility can make it harder to determine the interest rate investors will demand.
Companies may therefore accelerate planned bond offerings when they believe market conditions could become less predictable.
Bloomberg’s report indicates that the November 2 financing wave partly reflected that calculation.
However, the timing does not establish that corporate executives expect a particular election result.
The financing rush is better understood as an effort to manage uncertainty rather than a confirmed prediction of how Americans will vote.
Oracle Launches a $10-Billion Bond Offering
Oracle filed a preliminary prospectus supplement with the US Securities and Exchange Commission outlining its plan to issue $10 billion in senior unsecured notes.
The offering includes six series of debt.
One series consists of floating-rate notes maturing in 2029.
The other five series carry fixed rates, with maturities in 2029, 2031, 2033, 2037 and 2046.
The combination allows Oracle to borrow across different maturities and interest-rate structures.
Shorter-term borrowing may offer different pricing characteristics from longer-term bonds.
Longer maturities can extend repayment obligations into future decades.
The floating-rate notes are linked to the Secured Overnight Financing Rate, or SOFR, plus an additional spread.
That means their interest expense may change as the reference rate changes.
The preliminary prospectus initially left several pricing details to be finalized.
Therefore, the announced $10-billion offering should not be confused with a separately verified final allocation across all six tranches.
Oracle Also Plans to Sell $10 Billion in Shares
Alongside the bond offering, Oracle filed plans to raise $10 billion through a common-stock sale.
The company described the transactions as separate offerings.
Completion of one is not dependent on completion of the other.
That distinction is crucial for understanding Oracle’s financing strategy.
Bonds create debt obligations.
The company generally must pay interest and repay principal according to the agreed terms.
Common shares, by contrast, represent ownership.
They do not carry the same contractual principal repayment obligation.
However, issuing additional shares increases the number of shares outstanding and can dilute the ownership percentage of existing investors.
By combining debt and equity, Oracle is attempting to balance its funding needs against the financial consequences of additional borrowing.
If completed at their announced sizes, the two offerings would raise approximately $20 billion before applicable fees and expenses.
They would not represent $20 billion in new bonds.
Why Oracle Needs So Much Capital
Oracle is expanding its cloud infrastructure operations to serve large enterprise customers and companies developing advanced artificial intelligence models.
Its customers include technology businesses that require substantial computing capacity.
Modern AI data centers depend on specialized processors, networking equipment, cooling systems, electricity infrastructure and physical facilities.
Those investments can require billions of dollars before a project generates meaningful revenue.
Oracle has been aggressively building infrastructure to compete with larger cloud providers such as Amazon Web Services, Microsoft Azure and Google Cloud.
The company expects its capital spending to peak during its current and next fiscal years.
But the financial returns from that investment may arrive gradually.
That creates a gap between near-term spending and future cash generation.
The latest bond and equity offerings are intended to help Oracle manage that gap.
Oracle Already Has More Than $125 Billion in Borrowings
Reuters reported that Oracle had approximately $125.34 billion in notes payable and other borrowings as of August 31, 2026.
The figure is significant relative to the company’s fiscal 2026 revenue of approximately $67.36 billion.
Oracle’s borrowing levels have become a major focus for credit investors.
The company has committed substantial resources to its cloud expansion, while its revenue base remains smaller than those of several major competitors.
Borrowing can accelerate business growth when investments generate sufficient returns.
But it also creates contractual obligations that must be met regardless of short-term stock-market sentiment.
Higher debt can limit future financial flexibility.
The challenge becomes more serious when borrowing costs rise.
For Oracle, investors are increasingly evaluating not only the potential growth of its AI business but also the cost of funding that expansion.
Bond Investors Demand Higher Returns From Oracle
The Wall Street Journal reported that Oracle was offering investors unusually attractive yields to support its latest bond financing.
One example involved approximately $1.75 billion of five-year notes.
Initial pricing discussions indicated a spread of roughly 2.75 percentage points above comparable US Treasury yields.
That was wider than the yield spread on some of Oracle’s existing debt.
It also exceeded the approximately 2.3-percentage-point spread reported for comparable lower-rated corporate bonds.
The comparison matters because investors generally demand additional yield from companies they consider more exposed to financial uncertainty.
Oracle continues to hold investment-grade credit ratings.
However, its borrowing costs suggest some investors are approaching the company’s debt more cautiously.
A higher yield can help attract bond buyers.
But it also increases the company’s financing expense.
Over time, that cost can reduce the amount of cash available for other corporate purposes.
Oracle’s Credit Rating Is Close to Junk-Bond Territory
S&P Global Ratings downgraded Oracle to BBB- in July 2026.
BBB- remains an investment-grade rating.
But it is the lowest rating within S&P’s investment-grade category.
A further downgrade could push the company’s debt into speculative-grade territory.
That possibility matters because some institutional investors operate under rules limiting their exposure to below-investment-grade securities.
A downgrade can therefore affect the potential investor base and the yields required in future financings.
However, being rated BBB- does not mean Oracle has defaulted.
Nor does it establish that a downgrade is inevitable.
Oracle continues generating substantial revenue and has access to capital markets.
The question is whether future cloud-business growth and cash generation will strengthen its financial position quickly enough to support its investment plans.
Oracle Shares Fall as Investors Question the Financing
Oracle’s stock declined sharply on November 2 after the company announced its fundraising plans.
Reuters reported a fall of approximately 8.8%, while other market reports recorded a decline of roughly 9% during the session.
The reaction reflected several overlapping concerns.
Shareholders face potential dilution from the common-stock offering.
Bond investors are evaluating the company’s rising debt burden.
And the broader technology market is reassessing the financial returns from artificial intelligence infrastructure.
The company had previously indicated that it intended to limit additional capital-market fundraising through fiscal 2030.
Some investors therefore questioned why Oracle was moving to raise the full amount so soon.
However, announcing financing plans does not automatically establish financial distress.
Corporations may raise capital in advance to support development, reduce uncertainty or take advantage of available market liquidity.
The key issue is whether the money can be invested profitably.
Microsoft’s $25-Billion Bond Offering Shows the Broader Trend
Oracle’s financing activity follows a major debt issuance by Microsoft.
The company recently launched a $25-billion bond offering as large technology companies increased investment in AI-related infrastructure.
WWC ONE MEDIA examined the transaction in Microsoft Raises $25 Billion in Massive Bond Sale as AI Spending Explodes — But Is Big Tech’s Debt Gamble Getting Dangerous?.
The article explored why technology companies are increasingly using corporate debt to support large capital-investment programs.
However, Microsoft and Oracle have different financial profiles.
Microsoft benefits from a larger revenue base and substantial recurring cash generation.
Oracle is undertaking its expansion with greater leverage relative to its current business scale.
The distinction helps explain why bond investors may demand different yields from the two companies.
Both can access financing markets.
But the cost and risk of that financing can vary considerably.
Oracle’s New Mexico Data-Center Financing Adds to Concerns
Oracle’s capital requirements extend beyond conventional bond issuance.
Large data-center developments can also involve project financing, specialized lending structures and commitments to suppliers.
WWC ONE MEDIA previously examined a separate development in Oracle’s $18 Billion AI Data Center Debt Comes Under Pressure — And New Mexico’s Permitting Fight Is Getting Bigger.
The report discussed uncertainty surrounding financing associated with a large New Mexico data-center project.
That transaction is separate from Oracle’s November 2 corporate bond offering.
The amounts should not be added together without understanding the entities, financing structures and accounting treatment involved.
Nevertheless, the example illustrates how the AI infrastructure boom creates risks at several levels.
A cloud provider may borrow directly.
Project developers may seek financing for individual facilities.
Suppliers may extend credit or require advance payments.
The system depends on projects proceeding on schedule and attracting enough revenue to meet financing obligations.
Big Tech’s AI Spending Is Approaching Extraordinary Levels
Oracle is not alone in confronting the cost of artificial intelligence infrastructure.
Technology companies including Amazon, Alphabet, Microsoft and Meta are committing enormous sums to computing facilities and equipment.
WWC ONE MEDIA explored the wider industry in Big Tech’s $750-Billion AI Gamble Shakes Wall Street as Core Businesses Slow — But Will the Spending Ever Pay Off?.
The report examined estimates suggesting combined capital expenditure among major technology companies could approach $750 billion in 2026.
These forecasts include spending beyond AI and may use different fiscal periods.
They should therefore be understood as broad investment estimates rather than an audited figure for AI alone.
Still, the trend is clear.
Building the infrastructure required for advanced artificial intelligence is becoming increasingly capital-intensive.
For bond markets, that may mean additional issuance from major technology borrowers.
For shareholders, it raises questions about when those investments will produce sufficient returns.
Oracle Expects Revenue Above $225 Billion by Fiscal 2030
Oracle has outlined ambitious long-term financial targets.
At a recent investor presentation, the company forecast annual revenue exceeding $225 billion in fiscal 2030.
That would represent more than three times its fiscal 2026 revenue.
The company also expects to achieve positive free cash flow during the second half of fiscal 2028.
Those projections form an important part of management’s case for continued infrastructure spending.
If customer demand develops as anticipated, the expansion could support significant revenue growth.
But forecasts are not guaranteed outcomes.
Oracle’s plans depend on executing large infrastructure projects, securing computing equipment and meeting customer requirements.
It must also manage financing costs and competition from other cloud providers.
The company has substantial commitments connected to major AI customers, including OpenAI.
Those relationships may generate revenue opportunities, but they also create exposure to the financial and operational circumstances of individual customers.
For lenders and shareholders, the central question is whether Oracle can turn its growing cloud business into sustainable cash flow.
Why the Bond Market Matters to the AI Boom
Artificial intelligence expansion is no longer simply a technology-industry story.
It is becoming a major issue for corporate finance.
When companies finance capital expenditure through bonds, future business returns must support interest payments and debt repayment.
That means credit markets increasingly influence the pace at which AI infrastructure can expand.
If borrowing costs remain manageable, companies may continue building new facilities.
If yields rise sharply, some projects could become more expensive or financially unattractive.
Financing conditions can therefore affect the industry’s growth even when the underlying technology continues improving.
A company may have strong demand for its services but still face delays if raising money becomes too costly.
The growing connection between AI investment and credit markets makes large bond offerings such as Oracle’s especially important.
The $2.1-Trillion Data-Center Forecast Raises the Stakes
Bank of America Global Research has forecast that worldwide data-center spending could reach approximately $2.1 trillion by 2028.
WWC ONE MEDIA examined that outlook in Bank of America Predicts $2.1-Trillion AI Data Center Explosion by 2028 — But Could a Global Power Shortage Bring the Entire Boom Crashing Down?.
The projected spending involves computing equipment, networking systems, buildings and supporting infrastructure.
However, it remains a forecast.
It is not money already invested or contractually guaranteed to be spent.
Electricity availability, construction delays, financing constraints and changing customer demand could affect the pace of development.
For Oracle, these factors are particularly relevant because its business strategy depends on building enough capacity to serve major cloud customers.
The projected market opportunity is substantial.
But so is the financial commitment required to pursue it.
The Midterm Elections Could Increase Financial-Market Uncertainty
The November 3 US midterm elections add another layer of uncertainty.
Investors are evaluating the possible effects of changes in congressional control on taxation, regulation, federal spending and economic policy.
The election could influence market expectations.
However, no particular result can be assumed before the votes are counted.
WWC ONE MEDIA previously examined rising political engagement in Record 48 Million Americans Vote Early in 2026 Midterms as Democrats Surge in Key Battlegrounds — But Could Election Day Change Everything?.
That article described an earlier early-voting snapshot and the uncertainty surrounding the election outcome.
For corporate borrowers, the immediate concern is financial-market volatility.
Large transactions can become more difficult to price if Treasury yields, stock prices or credit spreads move sharply.
By accessing the market before the election, companies may have hoped to reduce their exposure to that uncertainty.
But the decision to borrow early does not necessarily signal fear of a specific political result.
What Happens if Bond Yields Rise Further?
Corporate borrowing costs are influenced by both Treasury yields and the additional spread investors require for taking company-specific credit risk.
If Treasury yields rise, companies may face higher borrowing costs even when their credit ratings remain unchanged.
If investors become more concerned about a company’s financial condition, its credit spread can widen.
The two effects can combine.
For highly leveraged borrowers, higher interest expenses may reduce available cash flow.
Companies may then reconsider share buybacks, acquisitions, expansion plans or other investments.
However, rising bond yields do not automatically lead to a credit crisis.
Some businesses have sufficient earnings and cash reserves to absorb higher financing costs.
Others may lock in funding well ahead of repayment deadlines.
The important issue is the financial strength of each borrower.
Oracle’s situation illustrates why investors increasingly distinguish between technology companies with strong balance sheets and those relying more heavily on borrowed capital.
What This Means for Philippine Investors and Businesses
The US corporate bond market can influence financial conditions around the world.
Changes in Treasury yields affect international borrowing costs and investor preferences.
When major American companies offer higher yields, some global investors may find those securities more attractive relative to riskier assets.
That can influence capital flows into emerging markets, including the Philippines.
However, there is no direct basis to conclude that Oracle’s bond offering will cause an immediate decline in Philippine stocks or a specific movement in the peso.
Those outcomes depend on many factors, including monetary policy, domestic economic conditions and global risk sentiment.
For Philippine companies considering overseas financing, the broader lesson is that the timing and structure of borrowing matter.
Large corporations may seek capital when markets are receptive rather than waiting until money is urgently required.
Investors, meanwhile, must assess whether the potential returns from corporate bonds adequately compensate for credit and interest-rate risks.
What Investors Should Watch Next
Several developments will determine whether Oracle’s financing strategy succeeds.
First, investors will examine the final pricing and demand for its bonds.
The interest rates Oracle must pay will help indicate how the market assesses its financial risk.
Second, the share offering’s final terms will determine the degree of dilution for existing shareholders.
Third, Oracle must demonstrate progress in converting infrastructure investments into revenue and cash flow.
Its fiscal 2030 revenue forecast and projected improvement in free cash flow will face increasing scrutiny.
Fourth, the broader investment-grade market will be monitored for signs of changing credit appetite.
If companies continue accessing financing at reasonable spreads, the bond market may remain supportive of corporate expansion.
If borrowing costs rise sharply, more businesses could delay planned transactions.
Finally, the effects of the midterm elections and upcoming economic data may influence interest-rate expectations and investor confidence.
The Bigger Question: Is Wall Street Funding the AI Future or Taking on Too Much Debt?
Oracle’s $10-billion bond sale is part of a much larger financing story.
Seventeen companies entered the US investment-grade market on November 2, seeking to secure capital before a politically sensitive week.
For many borrowers, the objective was straightforward: raise money while financing conditions were relatively favorable.
For Oracle, the stakes are considerably greater.
The company is pursuing an ambitious cloud-computing expansion while carrying more than $125 billion in borrowings.
Its simultaneous $10-billion equity offering demonstrates the scale of the financial resources it believes will be required.
Investors remain divided.
Supporters see an opportunity to build the infrastructure supporting the next generation of artificial intelligence.
Critics worry that debt, dilution and rising operating costs could erode the financial benefits before they materialize.
Neither outcome is guaranteed.
But the bond market is becoming one of the most important arenas in which the future of the AI investment boom will be tested.
As Oracle leads 17 companies into a last-minute corporate bond rush before the US midterm elections, is Wall Street confidently financing the next era of technological growth — or could the enormous debt required to build artificial intelligence infrastructure become the industry’s next major financial weakness?