NEW YORK — October 31, 2026
Lululemon Athletica’s dramatic stock-market collapse is attracting renewed attention from technical analysts as a possible recovery pattern begins taking shape following years of disappointing share-price performance.
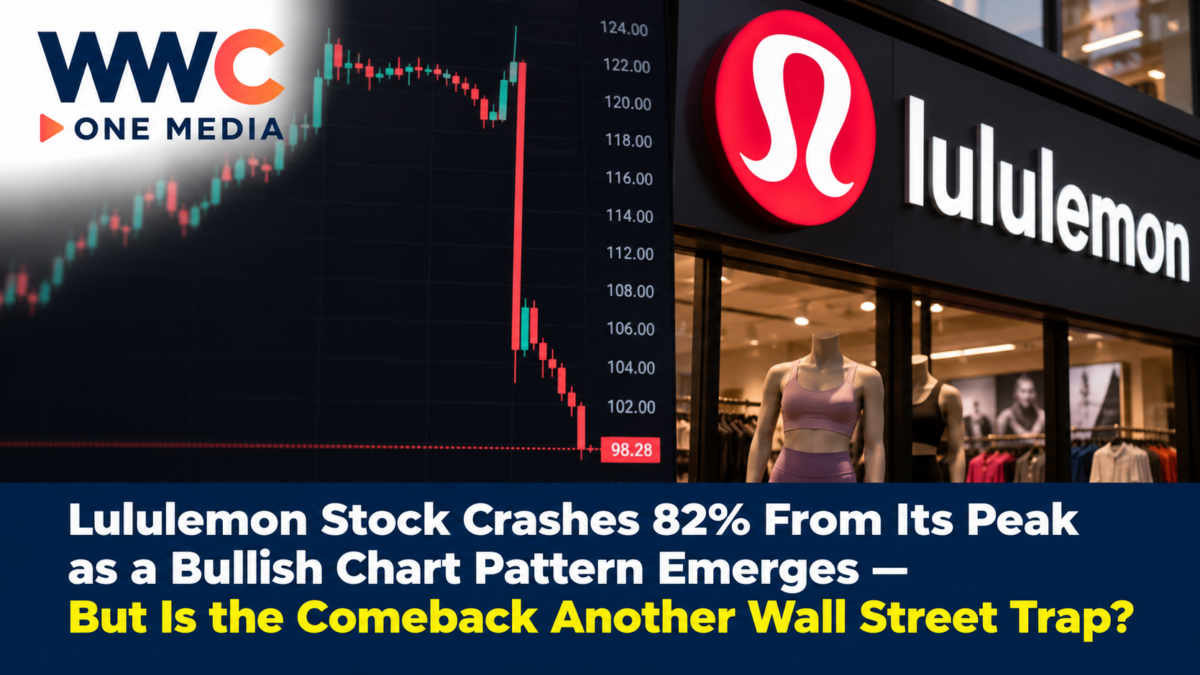
The athletic apparel company’s shares have fallen approximately 82% from their 2023 peak to their October 2026 low, erasing much of the market value once associated with the premium sportswear brand.
But a recent rebound has raised a question among traders: Could Lululemon finally be approaching a lasting bottom?
In an October 30 CNBC technical-analysis column, Frank Cappelleri, founder and president of CappThesis, examined a possible inverse head-and-shoulders pattern in Lululemon’s stock chart.
The formation can sometimes precede a bullish reversal after a prolonged decline.
However, Cappelleri’s analysis also highlighted a major warning.
Four of five previous bullish pattern breakouts during the past year failed to produce a sustained advance.
That history raises the possibility that the latest recovery attempt could prove temporary.
Meanwhile, Lululemon’s underlying business remains under pressure.
The company reported a 4% decline in fiscal second-quarter revenue, a 9% fall in comparable sales and a 12% comparable-sales decline in the Americas.
Its September earnings release also included another reduction in its full-year financial outlook.
For investors, the dilemma is striking: Lululemon shares have become dramatically cheaper than at their peak, but is the stock finally undervalued—or is Wall Street reacting to business problems that could take years to resolve?
Lululemon Stock Closes at $107.24 After a Turbulent Week
Lululemon shares ended Friday, October 30, at $107.24, down $2.58, or 2.35%, for the session.
The decline ended a four-day winning streak.
The stock had recently rebounded from an October low of $90.38, suggesting buyers were beginning to show renewed interest.
However, the recent improvement must be viewed in context.
Lululemon’s 52-week high was $225.98, placing its October 30 closing price more than 52% below that level.
The stock also remains dramatically below its all-time peak reached in 2023.
A recovery from a deeply depressed price can produce attractive short-term gains.
But such rebounds can occur within a longer-term downtrend without changing the overall direction of the market.
That distinction is central to Cappelleri’s assessment.
What Is an Inverse Head-and-Shoulders Pattern?
One of the possible bullish developments identified in CNBC’s analysis is an inverse head-and-shoulders formation.
This chart pattern typically consists of three troughs.
The central trough, or head, is lower than the two surrounding troughs, known as the shoulders.
Technical analysts often interpret the formation as a potential indication that selling pressure is weakening.
A line drawn between intervening price highs is commonly called the neckline.
A sustained move above that neckline can be viewed as a possible confirmation of a bullish reversal.
But the pattern is not a guarantee.
A stock may briefly move above resistance before falling again.
That is why analysts look for sustained price gains and supporting trading activity rather than relying on the shape of the chart alone.
In Lululemon’s case, the possible formation emerged after a sharp downward price gap in September.
The latest pattern remains tentative.
It should not be described as a confirmed long-term bottom.
Why Cappelleri Remains Cautious About a Bullish Breakout
The technical analyst’s concern is grounded in the stock’s history.
According to an independently accessible summary of his October 30 analysis, Cappelleri reviewed five previous bullish pattern-breakout attempts over the past year.
Four failed to produce a lasting upward move.
The remaining attempt generated only a modest advance before selling pressure returned.
This history suggests traders have repeatedly attempted to anticipate a recovery before the market established a durable change in direction.
Cappelleri also examined the stock’s 14-week relative strength index, or RSI.
The indicator fell below 30 in April 2024 and has largely remained between oversold territory and the midpoint of its range.
Such behavior can occur during persistent downtrends.
It does not mean the stock must continue declining.
It does suggest that investors should distinguish temporary rallies from sustained improvements in market momentum.
Technical Indicators Are Sending Mixed Signals
Other independently published technical indicators show why the current setup remains uncertain.
Some short-term trend measures have improved as Lululemon rebounds from its October low.
For example, the October 30 closing price of $107.24 stood above the approximately $103.05 50-day simple moving average reported by ChartMill.
But it remained below the approximately $133.79 200-day simple moving average.
That difference suggests short-term conditions have improved without fully reversing the longer-term weakness.
The same technical data showed an RSI near 59, indicating that the stock was no longer in deeply oversold territory on that particular daily measure.
Different data providers may calculate indicators using different intervals and timeframes.
A daily RSI reading is also not interchangeable with the 14-week RSI discussed by Cappelleri.
These measures are most useful when their assumptions and limitations are understood.
The $90 Level Could Become a Major Test
Lululemon’s October low of $90.38 is an important reference point for traders evaluating the recovery.
If the stock falls toward that level, investors may examine whether buying interest emerges again.
A sustained move below the previous low could weaken the argument that a durable bottom has formed.
On the upside, technicians are monitoring areas of resistance that may prevent a rally from continuing.
ChartMill identified a resistance area around $109.82, with additional technical levels around $124 and $132.
These are analytical reference points, not guaranteed trading outcomes.
Prices can move through them rapidly, particularly after earnings announcements, executive changes or broader market shocks.
Investors should also avoid treating a technical level as an objective estimate of a company’s intrinsic value.
The chart describes past trading behavior.
It does not independently establish how much Lululemon’s future profits are worth.
Lululemon’s Revenue Decline Explains the Stock’s Weakness
The company’s business performance offers important context for the share-price collapse.
Lululemon’s fiscal second-quarter revenue fell approximately 4% to $2.42 billion.
The quarter ended August 2, 2026.
Comparable sales declined 9% overall.
In the Americas, comparable sales fell 12%.
These figures were disclosed in the company’s September 3 earnings release and filed with the US Securities and Exchange Commission.
The decline indicates that the company is struggling to maintain sales momentum within established operations.
This is an important distinction from a company whose share price declines only because of temporary changes in investor sentiment.
Lululemon is confronting measurable operating challenges.
Those challenges will need to improve before investors can confidently argue that the business itself has entered a lasting recovery.
The Americas Business Is Lululemon’s Biggest Problem
The Americas remain particularly important to the company’s financial performance.
During the second quarter, revenue in the region declined 8%.
Comparable sales fell 12%.
The results suggest that customers are becoming less responsive to Lululemon’s existing product offerings.
Competition has intensified across the athleisure and performance-apparel markets.
Brands such as Alo Yoga, Vuori, Nike and other sportswear companies are competing for consumers seeking clothing for exercise and everyday use.
Lululemon must also respond to changing fashion preferences, pricing sensitivity and expectations for new products.
A well-known brand can retain substantial customer loyalty while losing market share.
That appears to be one of the company’s central challenges.
International Growth Has Not Fully Offset Weakness at Home
Lululemon’s international operations have delivered a different performance.
Second-quarter international revenue increased approximately 4% on a reported basis.
However, comparable sales outside the Americas declined 3%.
This distinction is important.
A company can increase regional revenue through new stores, currency movements or other factors even when sales at comparable established locations weaken.
International expansion may provide opportunities for Lululemon to reach new customers.
But the company must also maintain healthy demand within existing stores.
Expansion alone cannot guarantee higher profitability.
New stores require investment in property, employees, inventory and marketing.
The long-term objective must be generating sufficient returns from those investments.
Nike Faces Similar Challenges in Global Sportswear
Lululemon is not the only major sportswear company attempting a turnaround.
Nike has also experienced weakness in important markets, particularly China.
WWC ONE MEDIA recently examined Nike’s efforts in Nike Designs Its First Running Shoe Exclusively for India — But Can a ₹3,795 Sneaker Help Fix Its Global Sales Problem?.
Nike’s new Vegam Run shoe represents an effort to develop products specifically for Indian consumers rather than relying exclusively on globally standardized offerings.
The development illustrates the growing importance of product relevance and localized consumer demand.
For Lululemon, a similar question applies.
Can the company create enough innovative and desirable apparel to persuade customers to return?
The answer may matter more than any short-term chart pattern.
Leadership Changes Create a Possible Turning Point
Lululemon is also undergoing a leadership transition.
The company appointed Heidi O’Neill as chief executive officer, effective in September 2026.
O’Neill previously held senior leadership roles at Nike and brings experience in global retail, brand development and consumer products.
The company’s October 7 announcement introduced a refreshed leadership structure intended to support its next stage of growth.
Management has emphasized stronger product innovation, marketing and operational discipline.
These changes could create opportunities to address problems affecting the Americas business.
But executive appointments do not automatically translate into stronger sales.
A successful turnaround will require measurable progress in product demand, comparable sales, profitability and customer engagement.
For investors, the next several earnings reports will provide important evidence of whether the leadership transition is delivering results.
Nike’s Restructuring Shows How Difficult Sportswear Recoveries Can Be
Nike’s wider transformation offers another comparison.
WWC ONE MEDIA examined the company’s long-term investment strategy in Nike Bets Big on India With New Bengaluru Campus as China Sales Plunge 26% — But Its Global Comeback Faces a Bigger Challenge.
Nike is reorganizing operations, improving product development and seeking new growth opportunities.
Its recovery plan involves substantial operational changes rather than relying on a single successful product launch.
Lululemon faces a different business situation, but the broader lesson is relevant.
Established consumer brands may need considerable time to restore growth when their products lose momentum.
Investors attempting to buy near the bottom of a turnaround must therefore consider how long the process could take.
Lululemon Cuts Its Full-Year Outlook Again
The company’s revised fiscal 2026 guidance highlights the seriousness of its difficulties.
In September, Lululemon lowered its full-year revenue outlook to $10.35 billion–$10.50 billion.
Management said that represented a projected decline of approximately 5% to 7%.
The company also reduced its expected diluted earnings per share to $9.48–$9.73.
These figures are forecasts, not completed full-year results.
They suggest that management expects difficult conditions to continue through the remainder of the fiscal year.
For investors, that is a significant obstacle to a bullish investment thesis.
A stock can rebound before earnings recover, but sustained appreciation is easier to justify when the company’s outlook begins improving.
Tariff Refunds Complicate the Profit Picture
Another important detail in Lululemon’s financial statements involves tariff refunds.
During the second quarter, the company recognized approximately $134.5 million in refunds associated with duties imposed under the International Emergency Economic Powers Act.
It also received approximately $4.1 million in related interest.
The combined effect increased second-quarter diluted earnings per share by approximately $0.86 after tax.
Reported diluted earnings per share were $2.92, compared with $3.10 a year earlier.
The tariff-related benefit is important because it helped support the company’s reported margin and earnings figures.
Without examining that benefit, investors could overestimate the strength of underlying profitability.
A sustainable recovery would need to rely on stronger sales, improved product margins and better operating performance—not simply temporary or exceptional financial benefits.
Fashion Brand Recoveries Can Take Years
Lululemon’s challenges resemble those facing other globally recognized consumer brands.
WWC ONE MEDIA recently covered a major luxury-fashion downturn in Gucci Sales Plunge 6% as Kering Shares Crash Over 10% in Paris — But Is the Luxury Fashion Giant Facing an Even Bigger Crisis?.
Gucci and Lululemon operate in different market segments.
But both demonstrate the difficulty of maintaining consumer enthusiasm when fashion preferences change.
An established brand may retain global recognition while experiencing weaker sales.
Leadership changes, product innovation and marketing adjustments can support recovery.
However, rebuilding customer demand often takes longer than stock-market traders anticipate.
That is one reason investors should be cautious about equating a short-term rebound with a completed business turnaround.
Wall Street Has Already Punished Other Sportswear Stocks
Nike’s recent market performance demonstrates how aggressively investors can react to disappointing corporate forecasts.
WWC ONE MEDIA examined the situation in Tesla, Broadcom Surge While Nike and AI Storage Stocks Sink in a Wild Wall Street Session.
That report described Nike’s share-price decline following concerns over its turnaround and revenue outlook.
The comparison is relevant because investors are becoming more demanding of companies that promise future recovery.
They want evidence of improving operations rather than repeated assurances that growth will return.
For Lululemon, that means the next decisive development may come from financial results rather than technical indicators.
Does Lululemon’s Lower Valuation Make It Attractive?
At its October 30 closing price, Lululemon traded at roughly nine times reported trailing earnings, according to StockAnalysis.
That represents a substantially lower valuation than investors assigned the company during its strongest growth years.
A lower price-to-earnings ratio may attract investors searching for undervalued stocks.
However, valuation ratios must be interpreted carefully.
If earnings decline in future periods, a stock that appears inexpensive based on past profits may become less attractive.
Investors must also consider the possibility of further downward revisions to financial forecasts.
The company remains profitable and reported approximately $1.4 billion in cash at the end of its second fiscal quarter.
But its sales decline and weaker guidance show that a financial recovery cannot be assumed.
For investors, the key question is whether current share prices already reflect the risks ahead.
What Would Confirm a Genuine Stock-Market Recovery?
There is no single indicator that can prove a stock has permanently reached its lowest price.
But several developments would strengthen the recovery argument.
One would be sustained price gains above important resistance areas.
Another would be improvement in the longer-term trend, rather than isolated short-term rallies.
Strong trading participation could provide additional confirmation.
More importantly, the company’s financial results would need to show progress.
Investors may look for an improvement in comparable sales, stabilization of revenue forecasts and evidence that new products are attracting customers.
Stronger margins without large temporary benefits would also be encouraging.
These developments would provide a more complete recovery case than a chart pattern alone.
Could the Latest Rally Be Another Bull Trap?
A bull trap occurs when a stock appears to break out of a declining pattern but fails to sustain the move.
Investors who buy during the initial rally may suffer losses if selling pressure resumes.
Lululemon’s recent history makes this possibility particularly relevant.
Cappelleri’s examination of previous bullish formations found that most failed to produce durable gains.
That does not mean the current pattern must fail.
But it suggests that traders should avoid assuming the stock has reached a definitive bottom.
The technical picture remains mixed.
Short-term momentum has improved.
The longer-term trend remains damaged.
And the company’s underlying sales performance is still weak.
The Bottom Line
Lululemon shares have fallen approximately 82% from their 2023 peak to the October 2026 low, raising questions about whether a major stock-market bottom is forming.
Technical analyst Frank Cappelleri identified a possible inverse head-and-shoulders pattern in an October 30 CNBC analysis.
But previous bullish breakout attempts have mostly failed, and a lasting trend reversal has not been established.
Lululemon closed October 30 at $107.24, well above its recent $90.38 low but far below its 52-week high.
Its latest quarterly financial results showed declining revenue, weaker comparable sales and another reduction in management’s full-year outlook.
New leadership and product initiatives may eventually help restore growth.
But the company’s financial recovery remains unproven.
As Lululemon’s battered stock begins flashing early signs of a possible reversal, one question could decide whether the rebound becomes a major opportunity or another painful disappointment: Is Wall Street finally seeing the beginning of a lasting turnaround—or is this merely another rally before the next wave of selling?