NAIROBI, KENYA / MANILA, PHILIPPINES — November 7, 2026 | WWC ONE MEDIA | Global Business, African Markets, Retail and Investment
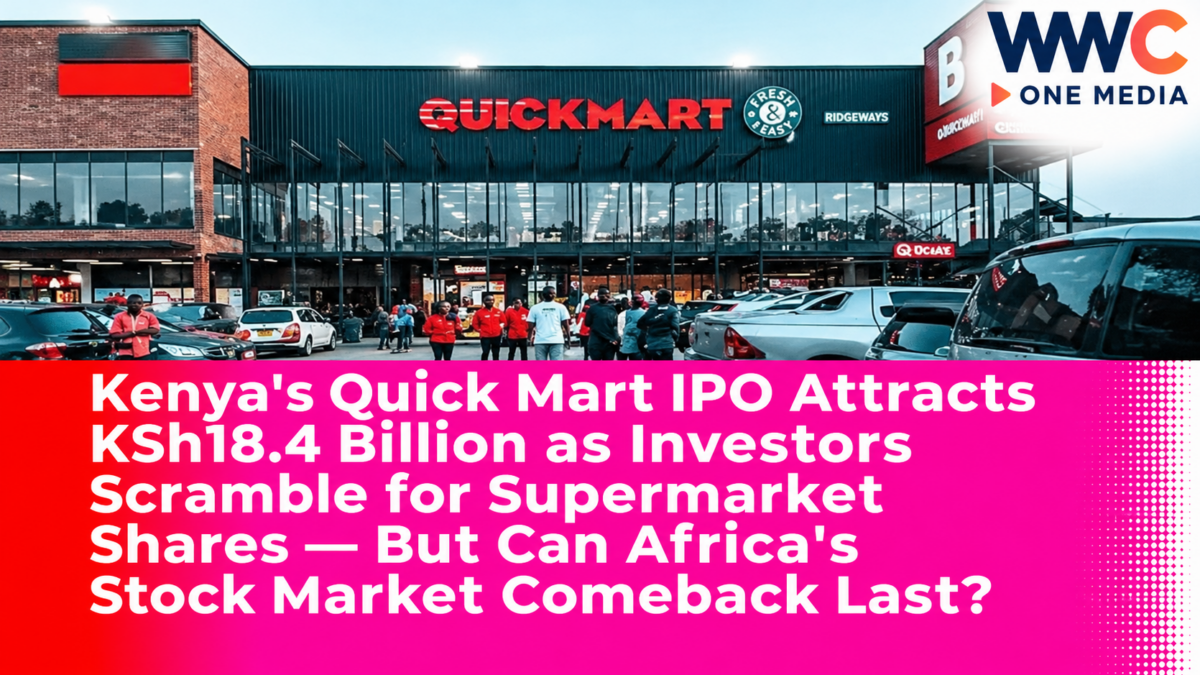
Kenya’s stock market is showing fresh signs of life after supermarket giant Quick Mart attracted KSh18.41 billion in investor applications for a KSh15-billion initial public offering, exceeding the available shares by 22.7% and signaling renewed appetite for one of East Africa’s most promising consumer markets.
The results, announced November 6, mark a significant milestone for Kenya’s second-largest supermarket chain as it prepares to become a publicly traded company on the Nairobi Securities Exchange.
But behind the impressive fundraising figures is an important twist.
Quick Mart itself will not receive the KSh15 billion from the offering.
Instead, the proceeds belong to existing shareholders selling half their ownership in the business.
That includes interests held through Sokoni Retail Kenya Limited, the investment vehicle associated with Quick Mart’s founders and private equity firm Adenia Partners.
The transaction is therefore both a stock market debut and a major opportunity for existing investors to realize the value of their holdings.
According to Bloomberg, the strong demand also signals a possible recovery in Kenya’s equity capital markets after years of limited new listings.
The offering follows the earlier listing of state-owned Kenya Pipeline Company, making Quick Mart only the second major Kenyan initial public offering of 2026.
Foreign investors showed particularly strong demand, requesting almost three times the shares initially reserved for their category.
Yet oversubscription is only the beginning of the story.
Can Quick Mart convert the enthusiasm surrounding its public debut into sustained shareholder returns—or will the first days of trading reveal that investors have become too optimistic about Kenya’s retail boom?
Quick Mart IPO Draws KSh18.41 Billion in Bids
Quick Mart confirmed that investors submitted 18,492 applications for a total of 2,454,598,686 shares.
The company had offered two billion existing ordinary shares at KSh7.50 each.
That created an offer value of KSh15 billion.
Applications exceeded the available shares by approximately 454.6 million, representing an oversubscription of 22.7%.
The total subscription level reached 122.7%.
In its November 6 announcement, Quick Mart said the offering attracted investors from Kenya, neighboring East African countries and international markets.
The response is noteworthy because the Nairobi Securities Exchange has experienced long periods with relatively few initial public offerings.
For Kenya’s financial sector, a successful supermarket listing could encourage other privately held businesses to consider public markets.
However, applications are not the same as final trading performance.
The opening price and subsequent share performance will depend on supply and demand when trading begins.
Foreign Investors Request Nearly Three Times Their Share Allocation
One of the strongest signals came from overseas investors.
Foreign applicants requested approximately 476.8 million shares, compared with an initially reserved allocation of 160 million shares.
That represented subscription demand of about 298%.
In value terms, overseas applications amounted to approximately KSh3.58 billion against an initial allocation worth KSh1.2 billion.
The company ultimately allocated about 236 million shares to foreign investors.
That was more than their original allocation but represented only approximately 49.5% of the shares they requested.
The strong demand suggests that international investors are increasingly interested in Kenya’s consumer economy.
But not every investor category experienced identical demand.
Four cornerstone investors applied for nearly their entire reserved allocation, while local institutions and retail applicants also participated substantially.
The difference matters because headline oversubscription can conceal important variations between investor groups.
Kenyan Retail Investors Receive Full Eligible Allocation
Quick Mart’s allocation results contained another important development.
Eligible retail investors from Kenya and the East African Community received all the shares they applied for.
Kenyan and regional institutional investors also received their full allocations.
This may initially appear surprising because the overall IPO was oversubscribed.
The explanation lies in the allocation rules.
The published results included applications submitted by five founder shareholders for approximately 118.7 million shares.
Those founder applications did not receive allocations.
Once the excluded applications are accounted for, eligible retail demand was below the number of shares ultimately available for allocation.
The final result therefore allowed qualifying retail participants to receive their full applications.
Foreign investors, by contrast, received approximately half their requested shares.
The allocation demonstrates that strong overall demand does not necessarily mean every investor must receive a reduced allocation.
The outcome depends on investor categories, eligibility requirements and the issuer’s published allocation policy.
Why Quick Mart Won’t Receive the KSh15 Billion
The most important detail for investors is the structure of the IPO.
Quick Mart is not issuing new shares to raise additional corporate capital.
Instead, existing shareholder Sokoni Retail Kenya Limited is selling two billion ordinary shares.
The offering represents 50% of Quick Mart’s four billion issued shares.
Because all the offered shares already exist, the transaction is classified as an offer for sale.
The proceeds go to the selling shareholder rather than to the supermarket company itself.
At the KSh7.50 offer price, Quick Mart’s total issued share capital is valued at approximately KSh30 billion.
That is an implied equity valuation based on the IPO price, not a guarantee of the company’s market value after listing.
The distinction between primary and secondary offerings is essential.
A primary offering creates new shares, with the company receiving proceeds that can be used for business purposes.
A secondary offering allows existing investors to sell shares they already own.
For Quick Mart, the listing introduces new public shareholders and creates a market for the company’s stock without directly adding KSh15 billion to its balance sheet.
The company says its organic expansion will be supported primarily through internally generated cash flow.
Private Equity Firm Adenia Partners Gets a Major Exit Opportunity
The IPO provides an important example of how private equity investment can be converted into publicly traded ownership.
Adenia Partners, a Mauritius-based investment firm focused on African businesses, is among the major investors behind Sokoni Retail Kenya Limited.
The investment vehicle also includes interests associated with the Kinuthia family and other shareholders.
Selling half of the company’s shares creates a potential route for existing owners to realize part of their investment.
Private equity firms typically seek to improve the value of businesses over time and eventually sell some or all of their ownership.
Exit routes can include sales to other companies, transfers to financial investors or public stock market listings.
In Kenya, public offerings have historically been a less frequently used exit route.
Quick Mart’s transaction could therefore become a significant precedent for other private equity-backed African businesses.
But success cannot be measured solely by oversubscription.
Investors will also assess how the stock performs after listing and whether Quick Mart can sustain earnings growth.
Who Will Own Quick Mart After the IPO?
Quick Mart’s disclosed allocation gives a clearer picture of the supermarket chain’s ownership structure after the listing.
| Shareholder category | Ownership after IPO |
|---|---|
| Sokoni Retail Kenya Limited | 50.0% |
| Cornerstone investors | 21.6% |
| Kenyan and East African institutional investors | 17.5% |
| Foreign investors | 5.9% |
| Kenyan and East African retail investors | 5.0% |
| Total | 100% |
Sokoni will remain the largest shareholder.
That means the listing broadens ownership but does not eliminate the influence of existing investors.
For minority shareholders, corporate governance will be an important issue.
They will need to evaluate how management allocates capital, how dividends are determined and how the company’s controlling shareholders approach long-term growth.
A public listing can improve financial transparency because the company becomes subject to applicable exchange and regulatory disclosure requirements.
But it does not automatically eliminate conflicts between controlling and minority shareholders.
World Bank and UK-Backed Investors Join the Offering
Quick Mart’s IPO attracted several prominent institutional investors.
They include the International Finance Corporation, the World Bank Group’s private-sector investment arm.
Another participant is MOBILIST, a program backed by the United Kingdom’s Foreign, Commonwealth and Development Office.
The other cornerstone investors include RWC Asset Management and 337 Frontier.
Cornerstone investors typically commit substantial capital to an offering before it closes.
Their participation can help demonstrate institutional interest and provide confidence to other potential investors.
Quick Mart had previously announced cornerstone commitments of up to approximately $55 million.
Those commitments included an IFC component that was initially conditional on board approval.
The final allocation announcement shows that the cornerstone investor group received approximately 864.2 million shares.
Together, they will own 21.6% of Quick Mart after listing.
However, the existence of major institutional investors does not guarantee positive returns for smaller shareholders.
Investment decisions still depend on price, valuation, financial performance and risk.
Quick Mart Has Grown Into One of Kenya’s Largest Retailers
Quick Mart operates 72 stores across 16 Kenyan counties.
It is the country’s second-largest supermarket chain, behind Naivas, based on store count and turnover, according to Business Daily Africa.
The business has expanded through a combination of store development, acquisitions and integration.
One important milestone came through its combination with Tumaini Supermarkets.
That transaction helped create a larger retail network and strengthen its market position.
Quick Mart now competes in a sector where customers are highly sensitive to prices, convenience, product availability and store location.
The company’s success will depend on maintaining efficient supply chains while expanding its geographic presence.
Competition remains significant.
Local retailers, multinational operators and informal neighborhood shops all compete for Kenyan household spending.
Even a company with a large store network must manage inventory carefully and keep operating costs under control.
Quick Mart Revenue Reaches KSh50.4 Billion
Quick Mart’s financial performance provides a more detailed picture of the business behind the IPO.
For the financial year ended December 2025, the retailer reported approximately KSh50.43 billion in revenue, an increase of 9.3% year over year.
Profit after tax rose approximately 33% to KSh1.51 billion.
Those figures indicate that the retailer was able to grow earnings faster than revenue during the period.
That can reflect improvements in operating efficiency, cost management or business mix.
However, supermarket retailing is generally a relatively low-margin industry.
Using the reported figures, Quick Mart’s net profit margin was approximately 3%.
That means the company retained roughly three shillings of net profit for every 100 shillings of revenue.
Even modest changes in costs, competition or consumer spending could therefore influence profitability.
Investors should evaluate earnings quality, working capital requirements and cash generation rather than focusing only on the number of stores.
Dividend Expectations Could Attract Income Investors
Quick Mart has also outlined an ambitious dividend policy.
According to its offering disclosures and financial reporting, the company expects to distribute a substantial proportion of earnings to shareholders.
A reported forecast anticipates KSh2 billion in dividends for 2026, equivalent to KSh0.50 per share.
At the KSh7.50 offer price, that would imply a dividend yield of approximately 6.7%.
But the figure is a forecast.
It is not a dividend that has already been guaranteed or paid.
Actual distributions depend on profitability, available cash, board decisions and applicable legal requirements.
Investors should also examine whether dividends can be sustained while the company continues opening new stores.
Paying out too much cash may reduce the amount available for future investment.
The balance between dividends and growth will become especially important now that Quick Mart has a broader public shareholder base.
Kenya’s Stock Market Is Showing Signs of Recovery
Quick Mart’s IPO arrives during a stronger year for Kenyan equities.
Bloomberg reported that the country’s benchmark stock index had gained approximately 28% in US dollar terms during 2026, placing it among the better-performing markets globally.
That improvement has helped create a more favorable environment for new listings.
Rising stock prices can encourage investors to take additional risk.
They may also make business owners more willing to offer shares to the public.
But market gains can reverse.
Currency movements, interest rates, economic growth and foreign investment flows all influence returns.
The current rally therefore supports the possibility of a capital-markets recovery without proving that the trend will continue indefinitely.
Quick Mart’s listing will provide an early test of investor appetite beyond the initial subscription period.
Kenya Pipeline Company Helped Reopen the IPO Market
Quick Mart follows the earlier public offering of Kenya Pipeline Company.
The government-led transaction involved the sale of a significant stake in the national oil transportation business.
It marked a major development for Kenya’s equity market after years of limited listing activity.
The two offerings are different.
Kenya Pipeline operates energy infrastructure, while Quick Mart is a consumer retail business.
But together, they demonstrate that Kenya’s stock exchange can attract investors across different sectors.
A broader range of publicly traded companies may help diversify investment opportunities.
For domestic pension funds and other institutions, additional listings can create new options for allocating capital.
For businesses, the ability to list shares provides another route for owners to realize value or access future financing.
However, attracting new listings also requires confidence in governance, liquidity and market regulation.
A Different IPO Story From Hong Kong
Kenya’s positive subscription results contrast with difficulties in some other equity markets.
As WWC ONE MEDIA reported on Hong Kong’s unusually high rate of abandoned IPOs, companies attempting to list in major financial centers have encountered fluctuating investor demand and difficult market conditions.
Those developments show that a well-known stock exchange does not automatically guarantee a successful public offering.
Valuation and market timing remain important.
Quick Mart’s IPO benefited from strong investor appetite for an established consumer business.
But the Kenyan offering differs significantly from technology companies seeking large amounts of fresh development capital.
Quick Mart’s proceeds flow to selling shareholders, and its investment appeal depends on an operating supermarket network rather than an unproven technology platform.
The comparison highlights the varied motivations behind public listings.
Could Kenya’s Success Inspire More Emerging-Market IPOs?
Other developing economies are also exploring ways to deepen their capital markets.
Vietnamese technology company VNG, for example, has considered renewed efforts to access American investors.
As WWC ONE MEDIA examined in its coverage of VNG’s possible US listing comeback, companies in emerging markets often seek public listings to increase visibility, provide liquidity for existing shareholders and potentially access additional capital.
The Kenyan and Vietnamese cases involve different sectors and listing strategies.
But they illustrate a common challenge.
Companies need to convince investors that their financial performance and long-term prospects justify the proposed valuation.
Quick Mart’s oversubscription suggests that investors were willing to buy the shares at KSh7.50.
It does not prove they would be equally enthusiastic at a substantially higher price.
That is why the November 12 trading debut will be important.
What the IPO Means for Philippine Investors
The successful Kenyan offering also offers lessons for the Philippines.
Both countries have growing consumer markets and stock exchanges seeking to attract attractive publicly traded businesses.
The Philippine market has experienced significant interest in major consumer and financial technology listings.
As WWC ONE MEDIA reported on the landmark public offering of GCash parent Mynt, large domestic businesses can attract international investors when their commercial prospects and valuations appear compelling.
GCash and Quick Mart are different businesses.
GCash operates a financial technology platform, while Quick Mart sells everyday consumer goods.
Their offerings also differ in structure.
Nevertheless, both illustrate the importance of domestic growth stories in attracting institutional capital.
For Philippine investors, Quick Mart’s IPO is also a reminder to distinguish between newly issued shares and existing shares sold by shareholders.
A heavily subscribed secondary offering may benefit selling owners without providing additional capital to the listed company.
That difference is essential when evaluating how an IPO could affect future business expansion.
Why Retail Investor Access Matters
Public offerings can provide opportunities for ordinary investors to own shares in established companies.
In the Philippines, digital investment channels have begun making stock-market participation more accessible.
As WWC ONE MEDIA explained in its coverage of Mynt’s retail IPO subscriptions through GStocks PH, easier access to investing can expand participation beyond traditional high-net-worth clients.
Quick Mart’s inclusion of Kenyan and regional retail investors reflects a similar interest in broadening public ownership.
However, access does not eliminate investment risk.
A company’s strong brand recognition does not guarantee rising share prices.
Retail investors still need to consider valuation, earnings, dividend sustainability and market liquidity.
Those principles apply whether the investment involves a supermarket in Kenya or a technology company in the Philippines.
Three Risks Investors Should Watch After Listing
Despite strong IPO demand, Quick Mart faces important challenges.
First, competition could pressure profit margins.
Supermarkets operate in a highly competitive environment. Price reductions, inventory losses, wages, rent and distribution costs can all affect profitability.
Second, expansion requires capital.
New stores can generate revenue but may also require substantial investment in property, equipment, technology and inventory.
Third, strong IPO demand does not guarantee a positive trading debut.
Some investors may sell quickly after listing.
If selling pressure exceeds demand, the share price could fall below the offer price.
Investors must therefore distinguish initial enthusiasm from the company’s long-term commercial performance.
What Happens Before the November 12 Trading Debut?
Quick Mart’s IPO results were announced on November 6.
The next important milestones involve payment, settlement and the start of public trading.
Qualified institutional investors face a November 10 payment deadline under the announced timetable.
Shares are expected to be credited to investors’ central depository accounts on November 11.
Refund processing for unallocated applications is also scheduled to begin that day.
Trading is expected to commence on the Nairobi Securities Exchange on Thursday, November 12, 2026.
Until trading starts, the IPO price remains the reference point for the offering.
The first-day market price will depend on buyers and sellers.
That makes the opening sessions an important test of whether demand remains strong after the allocation process.
The Bigger Question: Can Kenya Turn One Successful IPO Into a Lasting Market Revival?
Quick Mart’s public offering is an important development for Kenya’s financial markets.
The company attracted KSh18.41 billion in applications for KSh15 billion worth of shares.
Foreign investors submitted bids approaching three times their originally reserved allocation.
Major international institutions participated.
And the supermarket chain is preparing to become publicly traded after expanding to 72 stores across 16 counties.
These achievements suggest meaningful interest in established Kenyan businesses.
But the IPO’s structure also reveals that the transaction is primarily a shareholder exit rather than a new capital injection into the company.
Its success should therefore be measured by more than subscription numbers.
Investors will want to see sustained profitability, responsible expansion, effective governance and reliable shareholder returns.
The Nairobi Securities Exchange will also need to attract additional companies if the current improvement is to become a durable recovery.
For now, Quick Mart has demonstrated that international and regional investors are willing to commit substantial money to a major Kenyan consumer business.
The next test begins when the shares start trading.
And as the Nairobi Securities Exchange prepares for one of its most closely watched retail listings in years, the question is whether Quick Mart’s blockbuster IPO will mark the beginning of a new African investment boom—or whether investors will discover that strong demand before listing is much easier to achieve than lasting gains afterward.