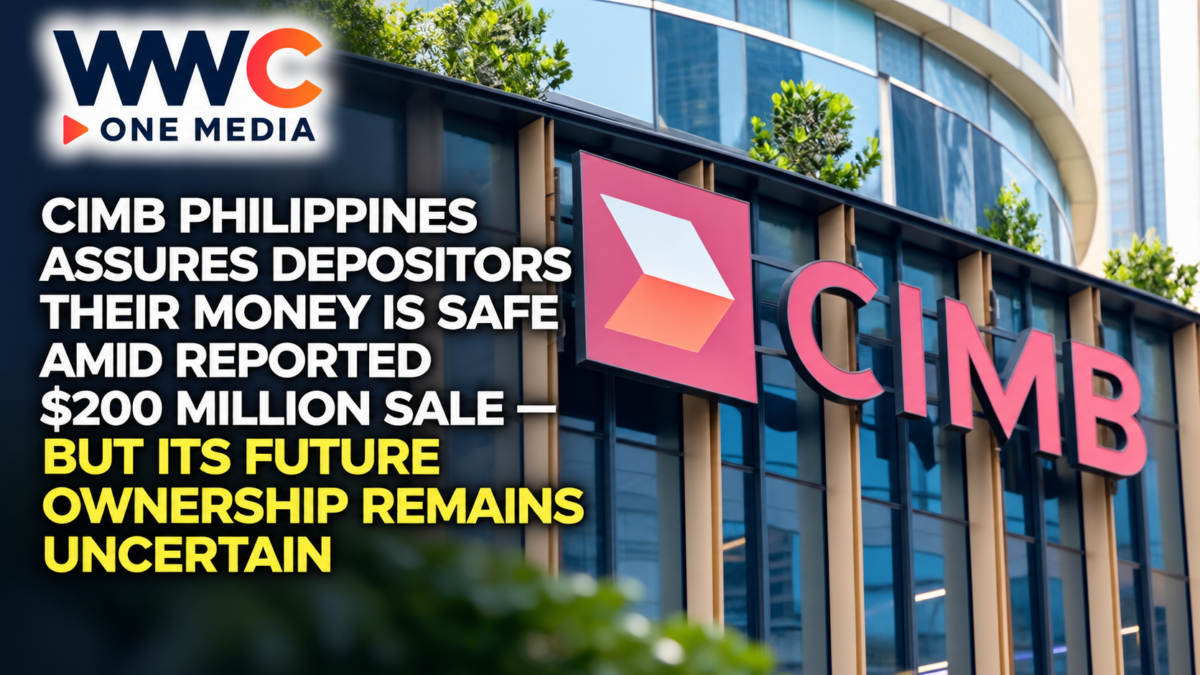
MANILA, Philippines — October 10, 2026 — CIMB Bank Philippines has moved to calm concerns among millions of customers after reports emerged that its Malaysian parent company is considering selling its Philippine banking business in a deal potentially worth as much as $200 million.
The digital-focused lender said it continues operating normally and that customer funds remain safe and secure, seeking to reassure depositors worried about what a possible ownership change could mean for their savings, loans and everyday banking transactions.
The statement followed an October 6 Bloomberg report that CIMB Group Holdings Bhd. had engaged a financial adviser and approached prospective buyers to assess interest in its Philippine operations.
But while CIMB Philippines emphasized business continuity and the safety of customer deposits, it did not explicitly confirm or deny whether its parent company is negotiating a sale.
The distinction leaves one major question unanswered.
Will CIMB Group retain its Philippine banking business, or will millions of customers eventually find themselves banking under a new owner?
CIMB Philippines Breaks Its Silence on Sale Reports
In a statement published through its official Facebook page, CIMB Bank Philippines acknowledged reports and speculation surrounding a possible sale of the business.
The bank said it would not respond to unsubstantiated news reports but emphasized that its operations were continuing as usual.
It also reassured customers that their funds remained safe and secure.
The message was designed to address concerns among depositors who rely on the bank for savings, transfers and other financial services.
However, the statement did not identify a prospective buyer, confirm a transaction or provide a timetable for any potential ownership change.
It also did not announce any suspension of banking operations, account closures or restrictions on customer withdrawals because of the reported sale.
The bank’s position remains one of operational continuity while ownership speculation continues.
Bloomberg Reports a Potential $200 Million Transaction
The uncertainty began after Bloomberg reported on October 6 that Malaysia’s CIMB Group Holdings was considering divesting its Philippine business.
According to people familiar with the discussions, CIMB has been working with a financial adviser and contacting potential buyers to determine whether there is sufficient interest in a transaction.
The business could be valued at as much as $200 million, the report said.
However, the valuation is an estimate associated with a possible transaction, not a confirmed purchase price.
The discussions remain at an early stage.
CIMB Group could still decide to retain the business rather than sell it.
No buyer has been officially named, no binding transaction has been publicly announced and no deal completion date has been established.
That means it would be inaccurate to report that CIMB Bank Philippines has already been sold.
Why Malaysia’s CIMB Group May Be Reviewing Its Philippine Business
The reported review comes as CIMB Group evaluates where to allocate its capital across regional markets.
Bloomberg linked the possible Philippine divestment to the Malaysian banking group’s effort to simplify its operations and concentrate resources on larger growth opportunities.
CIMB has banking and financial-services operations across several Southeast Asian markets and beyond.
For an international banking group, maintaining a presence in multiple countries can create opportunities for expansion and diversification.
But it also requires capital, regulatory compliance, technology investment and management resources.
A parent company may decide to sell a business if it believes those resources could generate stronger returns elsewhere.
Such a decision would not, by itself, establish that the subsidiary is insolvent or unable to serve customers.
A potential sale can reflect a strategic portfolio decision rather than an emergency response to financial distress.
Nevertheless, depositors and employees will want clearer information about the group’s long-term commitment to the Philippine market.
CIMB Has Served Filipino Customers Since 2018
CIMB entered the Philippines in December 2018, expanding its presence across the ASEAN region.
Its Philippine business built its identity around a branchless, mobile-first banking model.
Customers can open accounts and conduct many transactions using the bank’s mobile application.
The lender has also relied on partnerships to provide access to cash-in, withdrawal and other financial services.
By September 2025, CIMB reported approximately 10 million customers.
That figure shows the scale of its presence in the Philippine consumer banking market.
However, the customer count is a historical figure, not a verified October 2026 tally of actively transacting customers.
Nor does the total necessarily mean that all 10 million customers hold significant deposit balances.
The figure should be understood as a reported measure of the bank’s customer reach.
CIMB Philippines Operates Under a Commercial Banking License
Although CIMB Philippines uses a digital-focused business model, it operates under a commercial banking license issued by the Bangko Sentral ng Pilipinas.
This is an important distinction because not every bank operating primarily through an application holds the BSP’s separate digital-bank license.
CIMB previously said it would continue developing digital banking services under its existing commercial banking license rather than apply for a new digital-bank license.
Its legal and regulatory obligations therefore remain those applicable to its licensed operations.
A reported ownership review does not automatically terminate the bank’s license.
Any actual change in ownership or control would have to comply with applicable Philippine banking laws and regulatory requirements.
The available reports do not establish that the BSP has approved a sale or received a completed acquisition agreement.
Are CIMB Philippines Deposits Still Safe?
For many customers, the most important question is whether their money remains accessible.
CIMB Bank Philippines says its operations continue normally and its customers’ funds remain secure.
The bank has not announced a shutdown as a result of the sale speculation.
It is important to distinguish a possible ownership change from a bank closure.
If a shareholder sells its ownership stake in a bank, the bank may continue operating under the same legal entity, subject to the terms of the transaction and regulatory approvals.
A sale does not automatically mean depositors lose their money.
It also does not necessarily require customers to close accounts or withdraw funds.
However, the precise effects of any future transaction would depend on its structure.
Customers should rely on official notifications rather than assume that their banking arrangements will either remain permanently unchanged or be terminated.
PDIC Insurance Provides an Additional Layer of Protection
Depositors also have protection through the Philippine Deposit Insurance Corporation.
Effective March 15, 2025, the PDIC increased the maximum deposit insurance coverage from ₱500,000 to ₱1 million per depositor, per bank.
The protection applies to eligible deposits in PDIC-member banks.
For example, a depositor with one eligible savings account containing ₱600,000 would generally fall within the ₱1 million maximum coverage, subject to the rules governing insured deposits.
If a depositor has multiple accounts under the same name at the same bank, the balances are generally combined for purposes of the coverage limit.
The limit is not ₱1 million for every individual account.
This distinction matters for customers holding larger balances.
PDIC insurance is designed to protect eligible depositors in the event of a bank closure ordered by the relevant authority.
It does not mean that a possible acquisition automatically triggers an insurance payout.
A normal change in ownership is different from an insured bank failure.
A Possible Sale Does Not Mean CIMB Is Closing
Some customers may confuse an ownership sale with a decision to leave the banking market entirely.
But several different outcomes remain possible.
CIMB Group could retain its Philippine operations.
It could sell an ownership stake to another investor.
It could pursue a broader change in control, subject to applicable approvals.
Or the reported discussions could end without a transaction.
Each outcome would have different implications for customers, employees and business partners.
At present, no finalized transaction structure has been publicly confirmed.
The appropriate interpretation is that a potential sale has been reported, while the bank continues operating normally.
Claims that CIMB customer accounts are about to disappear or that deposits will automatically be frozen are not supported by the reporting reviewed.
What Would Happen to Customers if a Sale Proceeds?
If CIMB Group eventually agrees to sell its Philippine business, customers will need clear information about how the transaction affects their accounts.
Important questions would include whether the existing bank continues operating under its current name, whether banking applications and services will change, and whether account terms will be revised.
Customers with time deposits may also want to know whether existing contractual interest rates and maturity dates will remain in effect.
Borrowers would need information about servicing arrangements and payment channels.
However, a loan does not simply disappear because a bank changes owners.
Likewise, a deposit does not automatically become inaccessible because of a shareholder transaction.
The legal and operational effects depend on how the agreement is structured and what regulators approve.
Until a formal announcement is made, specific changes to CIMB’s accounts, products and services would be speculation.
What Happens to Existing Loans and Credit Obligations?
CIMB Philippines is not only a deposit-taking institution.
It also serves customers who use its lending products.
A potential ownership change would therefore raise questions about outstanding loans and repayment obligations.
In general, borrowers remain responsible for valid loan agreements even when a lender’s ownership changes.
Payment schedules and contractual terms do not automatically disappear because of acquisition discussions.
Any authorized changes to servicing arrangements should be communicated through official bank channels.
Customers should be cautious of claims that a rumored bank sale cancels existing debts.
They should also be alert to fraudulent messages asking them to send payments to unfamiliar accounts because of an alleged ownership transition.
Such claims should be verified directly with the bank.
Competition in Philippine Digital Banking Is Intensifying
CIMB operates in an increasingly competitive Philippine financial-services market.
Traditional banks have expanded their digital applications and online products.
At the same time, digital-focused institutions and financial technology companies are competing for customers through convenient onboarding, savings products, payment features and integration with other services.
That competition creates benefits for consumers, but it can also put pressure on banking margins and customer-acquisition costs.
Banks must spend on technology, cybersecurity, regulatory compliance and customer support while attempting to build profitable operations.
For an international parent company, the decision to retain or sell a business may depend partly on how it expects that investment to perform over time.
CIMB Group’s reported strategic review illustrates the competitive pressures involved in building a large digital-focused banking business.
However, the company has not publicly established that any particular Philippine operational weakness is the reason for the possible sale.
CIMB Group Has Been Reallocating Capital
The reported divestment also fits into CIMB Group’s broader review of its business portfolio.
Bloomberg reported that the Malaysian lender generated approximately 1.94 billion ringgit in second-quarter 2026 net income.
The group has spoken about reallocating resources away from operations that do not meet its return objectives.
It also announced plans involving the sale of an automotive-financing portfolio in Thailand earlier in 2026.
These developments suggest an emphasis on capital efficiency and concentration in markets the group regards as strategically important.
But strategic reviews do not guarantee that every business considered for divestment will be sold.
Companies may test market interest before deciding whether proposed valuations justify a transaction.
The reported $200 million price tag may therefore influence whether CIMB chooses to proceed.
Why Customer Confidence Matters During a Potential Bank Sale
Banking depends heavily on trust.
Customers expect institutions to safeguard funds, process transactions and provide reliable access to services.
Uncertainty about ownership can generate concern even when day-to-day operations remain unchanged.
This is particularly relevant to mobile-first banks because customers may rely on online announcements rather than physical branches for information.
CIMB’s public statement appears intended to reduce uncertainty before rumors create broader confusion.
For depositors, a bank’s official communications should carry more weight than social-media speculation.
For bank management, timely and specific information can help maintain confidence.
If a sale eventually proceeds, customers will expect clear explanations about the buyer, regulatory approvals and any operational changes.
What CIMB Depositors Should Do Now
Customers do not need to assume that the reported sale requires immediate action.
The bank says normal operations continue.
Depositors can review account balances, maintain access to official banking channels and keep records of their transactions.
They should understand the PDIC’s ₱1 million coverage limit and how it applies to their combined eligible deposits at the bank.
Customers should also monitor official CIMB and BSP announcements for any confirmed developments.
Unverified social-media posts should not be treated as instructions to withdraw money, transfer funds or share personal information.
Anyone receiving messages about an alleged acquisition should avoid disclosing passwords, one-time PINs or authentication details.
The key is to separate verified information from speculation.
At this stage, the reported sale is not a completed transaction.
Could a New Owner Strengthen CIMB Philippines?
A change in ownership is not necessarily negative for customers.
A well-capitalized buyer could potentially invest in technology, expand products or improve operational scale.
An acquisition could also create opportunities for partnerships or greater integration with other financial services.
However, those are possible outcomes, not confirmed benefits.
A different buyer might pursue a different business strategy, with consequences for products, branding and operating costs.
Without an identified purchaser and a formal agreement, it is impossible to determine what the proposed sale would mean for the bank’s long-term competitiveness.
The transaction’s value for customers would depend on the eventual buyer, business plan and regulatory safeguards.
The Bigger Picture: The Future of Digital Banking in the Philippines
The CIMB speculation highlights a broader issue facing Southeast Asia’s banking industry.
Digital technology has transformed how customers open accounts, transfer money and access financial products.
But building a widely used banking application is not the same as operating a consistently profitable financial institution.
Banks need sufficient capital, reliable funding, effective risk management and sustainable income.
They also need to maintain customer trust while investing in cybersecurity and compliance.
International banking groups must decide which markets deserve additional resources.
Some may expand through acquisitions.
Others may partner with local institutions or sell businesses that no longer align with their strategic priorities.
The possible CIMB transaction is one example of how regional banks are reassessing their business portfolios.
For Philippine customers, the most important issue remains continuity of safe, reliable and appropriately regulated financial services.
THE BOTTOM LINE
CIMB Bank Philippines has reassured customers that their money remains safe and its services are operating normally following reports of a potential $200 million sale.
Bloomberg reported on October 6 that Malaysian parent CIMB Group Holdings was exploring a divestment and gauging buyer interest through a financial adviser.
But no buyer, final purchase agreement or completion date has been publicly confirmed.
The bank has neither confirmed nor explicitly denied the reported sale discussions.
CIMB entered the Philippines in December 2018 and reported approximately 10 million customers as of September 2025.
Eligible deposits are protected under the Philippine Deposit Insurance Corporation’s maximum coverage of ₱1 million per depositor, per bank.
The biggest question is not whether CIMB Philippines is shutting down — there is no verified announcement of such a closure — but whether its Malaysian parent will ultimately sell the business and what any ownership change would mean for its customers.
For now, CIMB says it is business as usual. But with a reported $200 million deal under consideration, the future ownership of one of the Philippines’ prominent digital-focused banks remains uncertain.