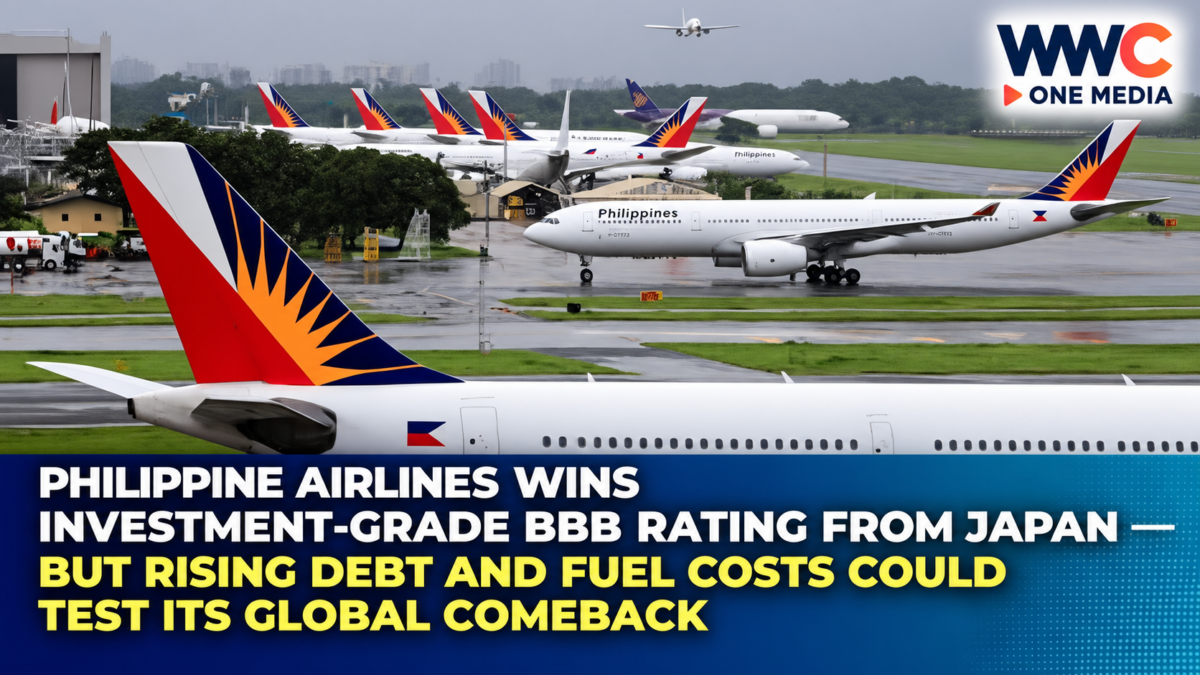
MANILA, Philippines — Philippine Airlines (PAL) has secured a major vote of confidence from Japan Credit Rating Agency (JCR), receiving a BBB investment-grade credit rating with a stable outlook nearly five years after emerging from a pandemic-era financial restructuring.
The rating, assigned on October 7, 2026, recognizes the flag carrier’s stronger market position, improved cost efficiency, solid international network and efforts to maintain financial discipline.
For the Lucio Tan-led airline, the development represents another milestone in a recovery that has seen PAL rebuild operations, strengthen its financial position and prepare for major international expansion.
But the investment-grade recognition comes with a significant warning.
PAL’s financial performance is facing renewed pressure from soaring aviation fuel costs, rising debt levels and an ambitious fleet modernization program that will require substantial financing.
The airline is also preparing to join the oneworld alliance, a move expected to strengthen its international competitiveness.
The biggest question now is whether Philippine Airlines can turn its stronger global reputation into sustainable profits without allowing expensive aircraft investments and volatile fuel prices to weaken its recovery.
Japan Credit Rating Agency Gives PAL Investment-Grade Status
Japan Credit Rating Agency assigned Philippine Airlines a BBB foreign-currency long-term issuer rating with a stable outlook.
The rating falls within JCR’s investment-grade category, indicating that the agency considers PAL to have an adequate capacity to meet its financial obligations.
JCR cited several factors supporting its assessment, including the airline’s established domestic and international market positions, efficient operations, improved financial management and available liquidity.
The agency also recognized PAL’s efforts to strengthen profitability through better aircraft utilization, premium passenger services and disciplined cost controls.
However, the stable outlook does not mean that PAL’s credit position is free from risks.
JCR emphasized that the airline industry remains vulnerable to unexpected changes in travel demand, fuel prices and broader financial conditions.
The agency said PAL’s ability to maintain a sound financial balance while undertaking major aircraft investments would remain an important factor in future rating assessments.
PAL’s North America Business Generates 35% of Revenue
One of PAL’s biggest competitive advantages is its strong position in the Philippines–North America aviation market.
According to JCR, flights connecting the Philippines with North America account for approximately 35% of PAL’s total revenue.
The airline holds the largest share of passenger traffic in the transpacific market between the Philippines and North America.
This position is supported by sustained travel demand among overseas Filipinos, families visiting relatives, tourists and business travelers.
PAL has strengthened its long-haul operations with Airbus A350-1000 aircraft serving destinations including New York, Toronto and San Francisco.
The airline is also scheduled to launch a Manila–Chicago route in November 2026, expanding its reach into the United States.
For PAL, these routes are particularly important because long-haul services and premium passengers can generate significant revenue.
However, they also expose the airline to fuel-price fluctuations, aircraft operating expenses and changes in international travel demand.
Maintaining profitability across these routes will be critical as PAL expands.
Philippine Airlines Maintains Strong Domestic Market Position
In the Philippine domestic aviation market, PAL held a 29% market share in 2025, ranking second behind Cebu Pacific.
JCR noted that Cebu Pacific controlled more than half of the domestic passenger market, reflecting the strong competitive position of low-cost carriers.
Despite intense competition, PAL continues to benefit from its status as the country’s only full-service domestic airline.
Its services appeal to travelers seeking premium cabins, corporate travel arrangements and connections to international flights.
Domestic operations account for slightly more than 20% of PAL’s total revenue and remain an important contributor to profitability.
However, airport slot constraints at Ninoy Aquino International Airport continue to limit opportunities for expansion.
The challenge for PAL is to preserve its higher-value customer base while competing against carriers offering lower fares.
PAL’s 2021 Bankruptcy Restructuring Becomes a Turning Point
The latest credit rating represents a major turnaround from the severe financial difficulties PAL experienced during the COVID-19 pandemic.
In September 2021, Philippine Airlines filed for Chapter 11 bankruptcy protection in the United States as international travel restrictions devastated airline revenue.
With support from its major shareholder, PAL completed its restructuring by the end of December 2021.
The process allowed the airline to reorganize financial obligations, reduce costs and establish a more sustainable operating structure.
PAL subsequently returned less efficient leased aircraft, reviewed maintenance arrangements and strengthened its focus on profitable routes.
The airline also increased the availability of higher-yield cabin products and expanded frequencies on selected long-haul services.
These measures helped restore the company’s earnings capacity as international travel recovered.
Nearly five years later, the investment-grade recognition from JCR demonstrates how far the airline has progressed since its restructuring.
But the recovery remains exposed to changing market conditions.
PAL Holdings Reports ₱183.8 Billion Revenue in 2025
PAL Holdings, the parent company of Philippine Airlines, reported ₱183.8 billion in revenue and ₱10.1 billion in net income for 2025.
Both figures improved from the previous year, reflecting stronger passenger demand and the airline group’s continued recovery.
Revenue also increased during the first half of 2026.
According to JCR, PAL Holdings generated ₱103.8 billion in revenue during the six-month period, representing an 11.2% increase from the previous year.
However, higher revenue did not translate into stronger bottom-line performance.
The group reported a net loss attributable to parent shareholders of approximately ₱1.8 billion.
The deterioration reflected a sharp increase in aviation fuel expenses linked to geopolitical tensions in the Middle East.
The figures illustrate an important financial challenge for airlines: growing passenger demand and higher revenue do not automatically guarantee profitability when operating costs increase rapidly.
Fuel Expenses Jump 48.2% as Middle East Conflict Hits Airlines
One of the most serious risks facing Philippine Airlines is the rising cost of aviation fuel.
JCR reported that PAL’s fuel expenses increased 48.2% year over year during the first half of 2026.
The higher costs contributed to weaker earnings despite continued revenue growth.
PAL’s EBITDA margin declined to 15.5% from 23% in the comparable period of 2025.
Although JCR still considered the margin solid, the decline highlights the financial impact of higher energy prices.
Fuel is one of the largest operating expenses for airlines, making international carriers particularly vulnerable to sudden price increases.
Long-haul services can be especially sensitive because they require substantial fuel consumption and careful management of aircraft capacity.
Airlines may attempt to recover higher costs through ticket pricing, fuel surcharges or operational adjustments.
However, their ability to pass additional expenses to passengers depends on competition and travel demand.
For PAL, maintaining profitability will require continued cost discipline as global energy markets remain uncertain.
Rising Debt Becomes a Major Warning for PAL
While JCR recognized improvements in PAL’s financial management, its report also highlighted a deterioration in several important debt indicators.
PAL Holdings’ interest-bearing debt-to-EBITDA ratio increased from approximately 2.7 times at the end of 2025 to 4.2 times on a trailing 12-month basis at the end of June 2026.
Its debt-to-equity ratio also increased from 2.2 times to 3.0 times.
Meanwhile, the interest coverage ratio declined from 2.85 times to slightly above 1.0 time.
These figures suggest that the company’s financial flexibility has weakened as fuel costs rise and additional aircraft-related debt is incurred.
A higher debt-to-EBITDA ratio indicates greater indebtedness relative to earnings.
A lower interest coverage ratio suggests less earnings capacity available to cover financing costs.
JCR attributed the deterioration to both weaker earnings and increased borrowing associated with aircraft deliveries.
The agency emphasized the importance of restoring profitability and carefully managing future financing requirements.
PAL Plans Major Airbus and Boeing Fleet Expansion
Philippine Airlines is pursuing an ambitious aircraft modernization strategy intended to improve operating efficiency, expand international services and strengthen passenger experience.
The airline’s fleet had an average age of approximately 11 years, according to JCR.
Of the nine Airbus A350-1000 aircraft ordered in 2023, two had been delivered by the end of June 2026.
The remaining seven are scheduled for delivery by 2028.
In July 2026, PAL signed a memorandum of understanding with Airbus for nine additional A350-1000 aircraft, with purchase rights for another five.
Deliveries under the additional Airbus arrangement are planned between 2034 and 2036.
PAL also signed a memorandum of understanding with Boeing for 15 Boeing 787-10 Dreamliner aircraft, with the opportunity to acquire five additional jets.
The carrier also has outstanding orders for Airbus A321neo aircraft.
These investments could improve fuel efficiency, support network growth and allow PAL to offer more competitive long-haul services.
However, aircraft acquisitions require substantial capital.
Financing costs, delivery schedules and the ability to fill additional seats profitably will be important in determining whether the expansion strengthens the airline’s financial position.
Oneworld Alliance Could Transform PAL’s Global Reach
Another major development is PAL’s planned membership in the oneworld alliance.
The airline received an invitation to join the global airline network in June 2026.
Once admitted, PAL is expected to become the alliance’s 16th member airline.
The partnership could connect PAL passengers to a network approaching 1,000 destinations across approximately 170 countries and territories.
Membership is also expected to provide opportunities for improved connecting itineraries, reciprocal frequent-flyer benefits and access to partner airline lounges.
For Filipino travelers, the arrangement could make international journeys more convenient by expanding travel connections through alliance partners.
For PAL, participation could strengthen its ability to attract premium travelers and corporate customers.
The airline has also expanded partnerships with Qantas Airways and Qatar Airways while maintaining established arrangements with airlines such as All Nippon Airways.
JCR considers the planned alliance membership a positive factor for PAL’s international competitiveness.
However, the full commercial benefits will depend on the completion of the membership process and the actual integration of passenger services.
Fitch and Moody’s See PAL Differently
PAL’s investment-grade recognition from JCR is particularly significant because other international rating agencies have assigned the airline lower ratings.
In June 2026, Fitch Ratings gave PAL a first-time BB long-term issuer default rating with a stable outlook.
A BB rating is below investment grade on Fitch’s scale.
Fitch nevertheless recognized PAL’s strong market position, diversified route network, adequate liquidity and disciplined approach to fleet expansion.
Earlier in 2026, Moody’s Ratings assigned PAL a Ba2 corporate family rating, also below investment grade.
Moody’s cited improvements in the airline’s financial profile while recognizing continuing industry risks.
The difference between these assessments does not mean one agency’s rating automatically replaces another.
Credit ratings reflect each agency’s methodologies, assumptions and evaluation of financial risk.
The important development is that JCR now places Philippine Airlines within its investment-grade category, providing an additional assessment of the company’s creditworthiness.
Could Investment Grade Help PAL Raise More Capital?
Investment-grade status can strengthen a company’s standing among lenders and institutional investors.
Some financial institutions and investment funds have policies that place limits on the types of credit risk they can accept.
A favorable rating may therefore support financing discussions and potentially broaden access to certain sources of capital.
For Philippine Airlines, this could be important as it prepares to fund new aircraft and other long-term investments.
However, receiving an investment-grade rating from JCR does not automatically guarantee lower interest rates or access to every investment-grade bond market.
Financing terms will still depend on prevailing interest rates, the structure of any borrowing, investor demand, credit assessments from other agencies and the airline’s financial position.
PAL has not announced a specific reduction in borrowing costs directly attributable to the October 7 rating.
The commercial benefits of the recognition will become clearer as the airline pursues future financing transactions.
The Bigger Challenge: Can PAL Expand Without Weakening Its Balance Sheet?
The new rating arrives at a crucial moment for Philippine Airlines.
The company is seeking to strengthen its presence in North America, modernize aircraft, improve passenger services and expand international partnerships.
These initiatives could create opportunities for stronger revenue and improved long-term competitiveness.
But they also require careful capital management.
Higher fuel prices have already reduced profitability, while aircraft deliveries have contributed to rising debt.
JCR specifically identified PAL’s ability to adjust aircraft investment schedules and diversify financing sources as important safeguards against adverse market conditions.
The airline must therefore balance growth opportunities against financial discipline.
Expanding too aggressively could strain cash flow and increase borrowing requirements.
Moving too cautiously, meanwhile, could limit opportunities to capture growing international travel demand.
The challenge will be finding a sustainable balance.
THE BOTTOM LINE
Philippine Airlines has secured a BBB investment-grade credit rating with a stable outlook from Japan Credit Rating Agency, marking an important milestone in its recovery from the financial disruption of the COVID-19 pandemic.
The recognition reflects PAL’s established domestic and international networks, cost-efficiency initiatives, improved financial management and efforts to strengthen its operations.
But the airline’s recovery is not without challenges.
Rising fuel costs, weaker first-half earnings, increased debt and major aircraft investment commitments create risks that management must carefully control.
PAL’s planned oneworld membership and expanding fleet could strengthen its international position, but the long-term benefits will depend on whether new investments translate into profitable growth.
For Philippine Airlines, winning an investment-grade rating is a significant achievement — but keeping that financial confidence while funding its next chapter of expansion may be an even greater challenge.