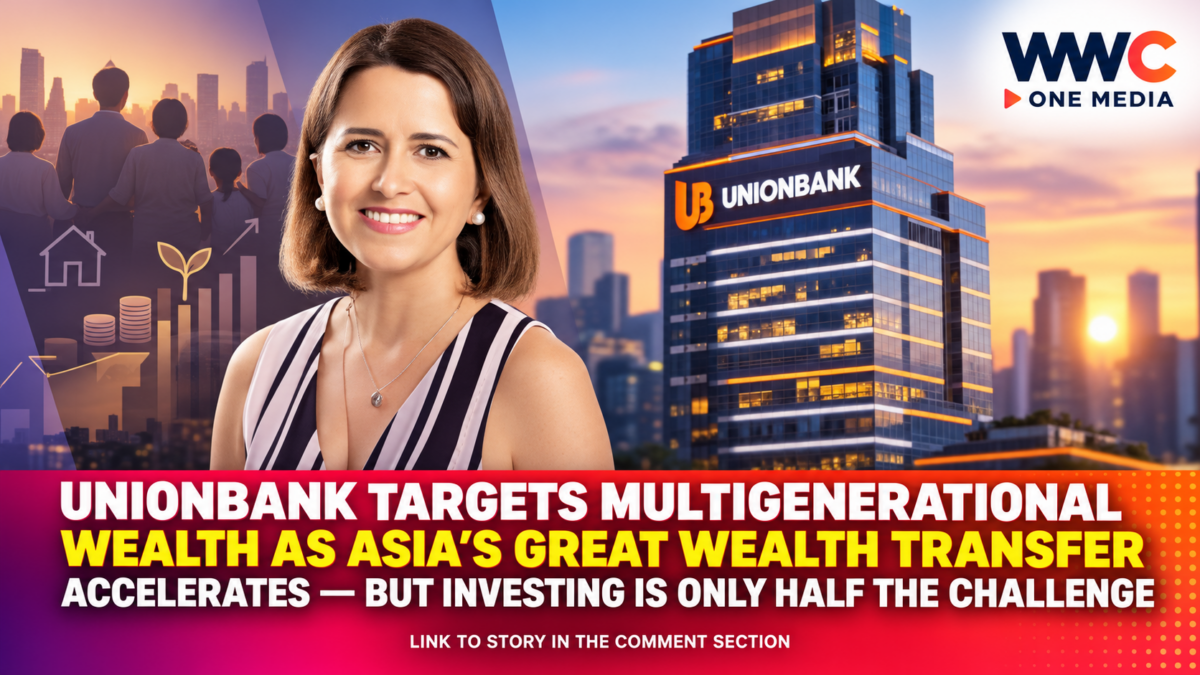
MANILA, Philippines — UnionBank of the Philippines is expanding its wealth-management strategy beyond simply choosing winning investments, arguing that preserving family fortunes across generations will increasingly depend on diversification, insurance, succession planning and whether heirs are actually prepared to manage what they inherit.
Through its “Next in Wealth: Unlocked” market-outlook series held in Cebu and Metro Manila in September, UnionBank Wealth brought together specialists from firms including Lombard Odier, BlackRock, Fidelity International and ATRAM Group to discuss how affluent Filipino families should navigate market volatility while preparing wealth to last beyond a single generation.
The message was straightforward:
Making money is only the first challenge.
Keeping it—and successfully transferring it—is much harder.
That distinction is becoming increasingly important as Asia enters what financial institutions have described as one of the largest intergenerational wealth transfers in history.
Asia is entering a massive wealth-transfer era
UnionBank itself has previously estimated that around 70,000 high-net-worth individuals across Asia-Pacific could transfer approximately $2.5 trillion to their heirs over a decade.
The bank highlighted that trend in its annual report as one of the forces reshaping private banking and wealth management.
Other financial institutions have made similarly large estimates.
Sun Life, citing broader regional research, said Asia could see around $5.8 trillion in intergenerational wealth transfers by 2030, underscoring why banks and insurers are increasingly building products around estate and succession planning rather than investment returns alone.
For financial institutions, that transfer represents an enormous opportunity.
For wealthy families, however, it creates a difficult question:
Will the next generation preserve the wealth—or lose it?
UnionBank says diversification remains the foundation
The investment side of UnionBank’s message focused heavily on diversification.
Experts participating in the bank’s market sessions argued that durable portfolios should not depend excessively on one asset class, one geography or a single source of returns.
Investors were encouraged to combine income-producing assets with long-term growth opportunities and resist the temptation to constantly reposition portfolios based on short-term market movements.
That advice is particularly relevant in 2026.
Financial markets have been navigating geopolitical risks, changing interest-rate expectations, energy-price volatility and rapid shifts in technology-related valuations.
UnionBank itself acknowledged market volatility earlier this year when reporting that geopolitical developments had affected trading performance.
For wealthy families, concentrated portfolios can magnify those risks.
A fortune built primarily around one family company, one property portfolio or one domestic market may appear strong until that particular asset encounters a downturn.
Diversification therefore becomes not simply an investment tactic but a wealth-preservation tool.
UnionBank is also putting healthcare protection inside the wealth conversation
One notable part of UnionBank’s approach is its decision to treat healthcare and insurance as components of wealth management rather than separate financial products.
Experts from Insular Life participated in the series to discuss local and international healthcare coverage and how unexpected medical costs can disrupt family finances.
The logic is especially relevant for families attempting to preserve capital over decades.
Large medical bills, long-term care requirements or unexpected disability can force investors to liquidate assets at unfavorable times.
That means a portfolio may be well diversified and still be vulnerable if the family has insufficient protection against major health-related expenses.
UnionBank President and CEO Ana Aboitiz Delgado said enduring wealth requires connecting investments with family responsibilities, protection needs and the legacy clients hope to leave behind.
The bank is already earning more from wealth management
UnionBank’s focus on wealthy clients is not merely educational.
It is increasingly important to the bank’s financial performance.
In the first quarter of 2026, UnionBank reported ₱3.8 billion in net income, up 167% year on year, while total customers rose to 18.9 million.
The bank specifically said higher digital transaction volumes and increased contributions from wealth management and bancassurance were helping drive fee income.
That makes wealth management strategically important because fee-based businesses can provide revenue without requiring banks to rely exclusively on lending.
UnionBank’s wealth arm had already recorded approximately 10% growth in assets under management in 2024, according to BusinessWorld.
Its 2025 annual report later said assets managed by its wealth businesses increased 15% year on year, while bancassurance net revenue surged 60% to ₱1 billion.
The numbers show why Philippine banks are competing increasingly aggressively for affluent customers.
The ATRAM deal also strengthened UnionBank’s investment platform
UnionBank’s wealth-management expansion received another boost when the bank combined its trust operations with the ATRAM Group.
The transaction strengthened its investment-product platform and improved its ranking among Philippine asset managers.
UnionBank said the combination lifted its assets-under-management ranking from 10th to fourth in the country and gave wealthy clients access to a broader range of private debt, bond and long-term portfolio strategies.
That expansion means UnionBank is increasingly competing not just with traditional banks but with standalone asset managers, insurers and private-banking platforms.
Affluent Filipinos now have more choices for where to keep and manage money.
The competitive question is therefore shifting from who offers the highest return to who can manage the entire financial life of a family.
But succession may be harder than investing
This is where UnionBank’s strategy becomes more interesting.
The bank is also relaunching its Private NextGen Academy in partnership with the Asian Institute of Management.
The program is intended to prepare younger family members for responsibilities involving leadership, wealth stewardship and legacy planning.
That acknowledges a problem wealth managers often cannot solve with financial products.
A family may have excellent investments.
It may own valuable companies and property.
Its estate documents may be complete.
But if heirs are unprepared to manage businesses, capital and family relationships, the wealth can still deteriorate.
PwC recently described succession as one of the biggest tests any family enterprise faces, warning that poorly planned transitions can disrupt ownership, strategy, leadership and relationships within the family.
That makes education of the next generation a form of risk management.
The succession problem is particularly relevant in the Philippines
Family-controlled businesses remain deeply embedded in the Philippine economy.
PwC Philippines has noted that more than half of Philippine publicly listed companies are backed by family offices, showing how family capital continues to influence major industries.
Yet succession preparation often lags behind the importance of these enterprises.
In PwC’s 2024 Philippine CEO Survey, nearly half of respondents said they expected changes in senior leadership within three to five years.
But only 25% said they had comprehensive succession plans covering all senior executives, while just 52% had communicated those plans to future leaders.
That gap can become even more complicated in privately held family businesses, where ownership, management and personal relationships frequently overlap.
Who becomes chief executive?
Who receives voting control?
Who receives property?
What happens when one heir wants to sell while another wants to continue operating the company?
Those decisions can determine whether a business survives another generation.
Family governance is becoming part of wealth preservation
PwC Philippines has previously recommended tools such as a family constitution to help define how family businesses and assets will be governed.
Such documents can clarify:
family values;
ownership principles;
qualifications for leadership;
decision-making rules;
succession procedures;
and mechanisms for resolving disputes.
These structures matter because transferring wealth is different from transferring the ability to manage it.
One generation may have spent 30 or 40 years building a company.
The next may inherit ownership overnight.
Without preparation, that sudden transition can create disagreements between heirs, professional managers and other stakeholders.
UnionBank’s decision to train younger family members therefore reflects a wider shift in private banking.
The heir is becoming a client before the inheritance even occurs.
Estate planning also has tax consequences
Succession planning carries practical tax and legal implications in the Philippines.
Property and other assets cannot always simply be handed from one generation to another without documentation, valuation and tax consequences.
The country’s estate-tax system has undergone major changes over the years, including the estate-tax amnesty that expired in June 2025.
The Bureau of Internal Revenue confirmed that the amnesty generally applied a 6% rate to the net taxable estate while waiving applicable penalties, surcharges and interest for qualified estates.
For current estates, applicable tax rules depend on the date of death and other circumstances, which is why wealthy families generally require professional legal and tax advice rather than relying solely on investment planning.
PwC has repeatedly urged families to treat estate and succession preparation as an ongoing process rather than something to address only after the death or incapacity of a family leader.
The “third-generation curse” remains a concern
Family-business discussions frequently reference the idea that wealth often deteriorates by the third generation.
It is not a mathematical law.
But it reflects a recognizable problem.
The founder may possess deep operational knowledge and personal discipline because the fortune was built from scratch.
The second generation may grow the enterprise.
By the third generation, ownership is often divided among more family members whose interests and skills can differ dramatically.
PwC Philippines has discussed this challenge in the local context, noting that by the third generation some family members may pursue their own ventures and professional management may become increasingly necessary.
This is precisely why wealth preservation involves more than choosing stocks and bonds.
Family governance, professional management and education can become equally important.
The younger generation also wants different things
The next generation of wealthy families may not invest exactly like their parents.
UnionBank has previously said younger Asian wealth holders tend to have stronger interest in areas such as:
sustainable investing;
digital financial services;
global diversification;
and alternative investments.
That generational shift can create opportunities—but also conflict.
Founders who built wealth through one business may prefer concentrated ownership and conservative investments.
Younger heirs may want technology companies, foreign markets, private equity or sustainable assets.
A successful wealth-transfer strategy therefore has to balance continuity with change.
Preserving family wealth does not necessarily mean preserving every investment exactly as it is.
UnionBank is also using digital tools to keep wealthy families inside its ecosystem
The bank showcased services such as UnionBank Global Transfer and PayDirect during the wealth series.
These services are intended to simplify financial transactions and cross-border money management.
The digital component is significant because younger affluent customers expect private banking to work differently from the traditional model built around branch meetings and paper documents.
UnionBank has spent years positioning technology as one of its competitive advantages.
Its customer base reached 18.9 million in the first quarter of 2026, providing a large pool from which the bank can identify customers whose financial needs evolve from basic banking toward investments, insurance and eventually private wealth management.
That creates a potential lifetime customer journey.
A digital banking customer today can become a wealth client tomorrow.
And eventually, that client’s children can become customers as well.
But diversification does not eliminate investment risk
UnionBank’s wealth message also requires an important caveat.
Diversification can reduce concentration risk.
It cannot guarantee profits or eliminate losses.
Global equities can decline.
Bond prices can fall.
Currencies move.
Private-market investments can become illiquid.
Real estate can lose value.
Even portfolios constructed by sophisticated wealth managers remain exposed to market risk.
That means wealthy investors should distinguish between wealth preservation strategies and promises of guaranteed preservation.
There are no guarantees that a family fortune will indefinitely maintain its real value.
The goal is to improve resilience—not eliminate uncertainty.
Preparing heirs may be the most important investment
The most interesting part of UnionBank’s strategy may therefore have little to do with financial markets.
Its relaunch of the NextGen Academy acknowledges that the person inheriting an asset can ultimately matter as much as the asset itself.
A ₱1-billion portfolio can be diversified.
A family company can hire professional managers.
Property can be insured.
But the next generation still has to make decisions.
That requires financial literacy, governance skills and an understanding of the responsibilities that come with ownership.
PwC’s latest global family-business research reinforces that point.
Its 2025 survey found 78% of family businesses considered safeguarding the business a top long-term goal, while 77% prioritized preserving the family’s legacy.
Those priorities increasingly overlap with wealth management.
The real battle is keeping the family—and the fortune—together
UnionBank’s “Next in Wealth” campaign may sound like another investment-outlook series.
But it highlights a major transformation in private banking.
Banks are no longer competing solely to manage portfolios.
They want to manage entire family financial ecosystems—investments, insurance, daily banking, succession, cross-border transfers and eventually the next generation of clients.
That strategy is commercially powerful.
If a bank develops a relationship with the children of wealthy customers before an inheritance occurs, it has a better chance of keeping those assets after the wealth changes hands.
For families, however, the stakes are much more personal.
The challenge is not simply earning the next percentage point of investment return.
It is making sure decades of accumulated wealth survive market shocks, health crises, family disagreements and generational change.
And as Asia’s massive wealth transfer accelerates, the families that succeed may not necessarily be those with the biggest portfolios.
They may be the ones that prepare their heirs before the fortune ever changes hands.