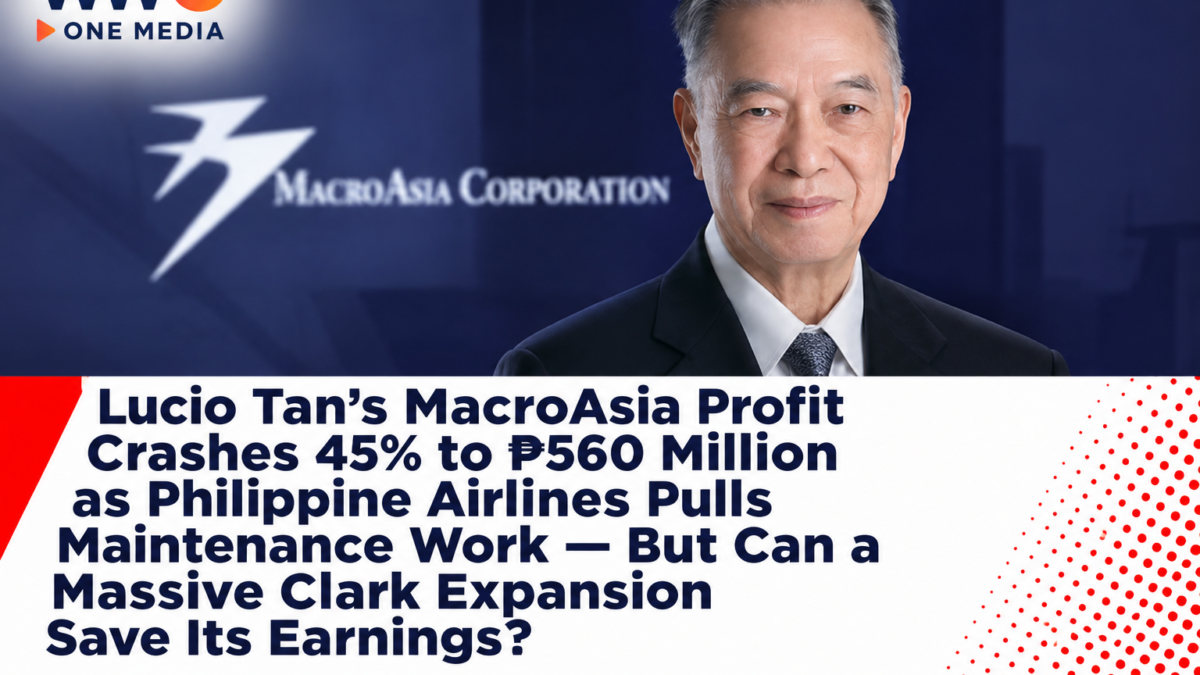
MANILA, PHILIPPINES — November 11, 2026 | WWC ONE MEDIA | Philippine Business, Aviation, Corporate Earnings and Infrastructure
Lucio Tan-led MacroAsia Corporation has reported a sharp decline in profits after Philippine Airlines (PAL) shifted more aircraft maintenance work in-house, forcing a major restructuring at Lufthansa Technik Philippines and adding pressure to the aviation services company’s bottom line.
MacroAsia’s net income attributable to parent-company shareholders plunged 45.2% to ₱560.4 million during the first nine months of 2026, down from approximately ₱1.02 billion a year earlier.
The decline came despite a 4.7% increase in consolidated revenue to ₱7.76 billion, highlighting the growing pressure from rising operating expenses, lower earnings from associated companies and changes in the aircraft maintenance business.
The financial deterioration became particularly severe during the third quarter.
Consolidated net income fell approximately 68% to ₱123.1 million from ₱384.3 million a year earlier, while quarterly revenue slipped 3.9% to ₱2.49 billion.
According to InsiderPH, Context.ph and Bilyonaryo Business, MacroAsia’s aviation maintenance affiliate has been grappling with higher lease charges and restructuring expenses after PAL began handling more routine maintenance internally.
But MacroAsia is not abandoning its aviation ambitions.
The company is supporting a major aircraft maintenance expansion in Clark, investing in a larger food production facility in Muntinlupa and developing additional water infrastructure projects.
With its core businesses continuing to generate higher revenues, can MacroAsia turn its expansion investments into stronger profits—or will rising costs and the loss of PAL maintenance work continue dragging down earnings?
MacroAsia’s Nine-Month Profit Falls 45.2% Despite Higher Revenue
MacroAsia’s latest financial performance reveals a widening gap between revenue growth and profitability.
The company’s January–September 2026 results showed:
- Revenue increased 4.7% to ₱7.76 billion from approximately ₱7.41 billion.
- Net income attributable to parent shareholders declined 45.2% to ₱560.4 million.
- Total consolidated net income decreased 42.3% to ₱669.6 million.
- Direct costs climbed 8.6% to ₱6.36 billion.
- Gross profit declined approximately 10% to ₱1.40 billion.
- Operating expenses increased 9.5% to ₱1.28 billion.
- Share of earnings from associated companies fell 29.8% to ₱680.9 million.
Basic earnings per share also dropped from ₱0.54 to ₱0.30.
The results show that MacroAsia’s businesses continued attracting demand, but the additional revenue was not sufficient to offset rising expenses and weaker contributions from affiliates.
Its gross profit margin fell from approximately 21% to 18%.
That three-percentage-point decline is especially significant for a company operating businesses where labor, food ingredients, equipment and airport-related costs can influence profitability.
MacroAsia’s problem is therefore not simply falling sales.
It is the amount of profit the company retains after paying the costs of delivering its services.
Philippine Airlines’ Maintenance Shift Hits Lufthansa Technik Philippines
One of the most important factors behind the earnings decline was the restructuring of Lufthansa Technik Philippines, or LTP.
MacroAsia owns 49% of the aircraft maintenance joint venture, which is associated with Germany’s Lufthansa Technik Group.
LTP provides maintenance, repair and overhaul services for commercial aircraft.
However, one of its longstanding customers, Philippine Airlines, has decided to handle more routine aircraft maintenance work internally.
That change affected LTP’s line-maintenance business.
Line maintenance includes the inspections, technical checks and servicing carried out to keep aircraft operating safely between scheduled flights.
Unlike major aircraft overhauls, these activities typically involve shorter maintenance windows.
Following the change in PAL’s maintenance arrangements, LTP discontinued its line-maintenance operations in August 2026.
The decision resulted in restructuring expenses and a smaller business contribution.
However, an important distinction must be made.
Lufthansa Technik Philippines has not shut down its entire aircraft maintenance business.
The joint venture continues operating its heavier maintenance and overhaul activities in Manila and is pursuing a substantial expansion in Clark.
The closure affects its line-maintenance operations rather than every service it provides.
Higher NAIA Lease Costs Add Long-Term Pressure
The restructuring at LTP created immediate costs, but the company is also confronting a problem that could last longer.
Higher lease charges at its facilities near Ninoy Aquino International Airport have increased operating expenses.
MacroAsia described some restructuring and input costs as transitory.
However, the increased rental expenses associated with revised lease arrangements may continue beyond the initial restructuring period.
That distinction matters for investors.
Temporary restructuring expenses can disappear once a business completes its transition.
Recurring lease expenses must be paid as long as the relevant agreements remain in effect.
If the company cannot offset those expenses through higher productivity, pricing adjustments or additional business, its profit margins could remain under pressure.
Together with weaker earnings from Japan Airport Service Co., the problems at LTP contributed to a roughly 30% decline in MacroAsia’s share of earnings from associates.
The decrease reduced the benefits of stronger sales in the company’s directly operated businesses.
MacroAsia’s Third-Quarter Profit Plunges 68%
The third-quarter results underline the seriousness of the profitability challenge.
From July through September 2026, MacroAsia reported consolidated net income of approximately ₱123.1 million.
That compared with ₱384.3 million during the same quarter in 2025.
Revenue declined to approximately ₱2.49 billion from ₱2.59 billion.
The company also reported weaker gross profit and reduced contributions from associated businesses.
The decline was not driven by a single expense alone.
Rather, higher operating costs, weaker affiliate earnings and the restructuring of aviation maintenance operations affected results simultaneously.
This combination is more difficult to manage than a temporary decrease in customer demand.
A company may be able to increase sales while continuing to face weaker profits if expenses rise faster than revenue.
MacroAsia now needs to demonstrate that its operating businesses can achieve better efficiency and restore margins.
Food Services Become MacroAsia’s Biggest Growth Engine
Despite the disappointing earnings, MacroAsia’s food services business continued expanding.
Revenue from food services increased approximately 9% to ₱3.87 billion during the first nine months.
The segment accounted for roughly half of consolidated revenue.
Meal production volume rose approximately 19% to 23.33 million meals.
The expansion was supported partly by demand from customers outside the aviation industry.
This diversification is important because airline catering depends on flight schedules, passenger numbers and airline operating conditions.
Demand from non-airline customers can provide another revenue source and reduce dependence on aviation activity.
However, higher production volume does not automatically guarantee higher profits.
Food costs, labor, utilities, transportation and facility expenses remain important.
MacroAsia must therefore manage the cost of producing additional meals while maintaining food safety and service standards.
The strong growth in meal volumes suggests that demand remains present.
The challenge is converting that demand into improved profitability.
₱1.2 Billion Muntinlupa Commissary Expansion Could Boost Production
MacroAsia is investing approximately ₱1.2 billion to expand its food production facility in Muntinlupa.
The project is expected to be completed during the first quarter of 2027.
Once operational, the enlarged commissary is designed to produce up to 90,000 meals daily.
That would provide additional capacity to serve airline and non-airline customers.
For MacroAsia, the investment could support future revenue growth and operational efficiencies.
A larger facility may allow the company to spread certain fixed costs across higher production volumes.
But the financial benefits will depend on actual customer orders, utilization, production expenses and execution.
A 90,000-meal daily production capacity is a facility target, not a confirmed number of meals already being sold.
The capital investment will also need to generate enough incremental profit to justify its cost.
With earnings currently under pressure, the success of the commissary expansion will become an important indicator of management’s ability to strengthen the company’s core businesses.
Ground Handling Revenue Rises Even as Flight Activity Declines
MacroAsia’s airport ground handling and aviation services segment also recorded revenue growth.
The business generated approximately ₱3.28 billion during the first nine months, an increase of around 5%.
The improvement came even though the number of flights handled declined approximately 5%.
Ground handling includes essential airport services such as baggage processing, aircraft turnaround assistance and other passenger and ramp operations, depending on the contracts involved.
The contrasting figures suggest that revenue per activity unit, service mix or contractual pricing may have changed.
However, the company has not provided enough detail in the accessible reporting to attribute the full increase to any single factor.
Higher revenue alongside lower flight volume does not necessarily mean the business became more profitable.
Labor, airport charges and equipment expenses may also have increased.
Still, the performance demonstrates that MacroAsia retained a substantial revenue base in aviation services despite changes affecting associated maintenance operations.
Lufthansa Technik Bets on Clark With Massive New Maintenance Complex
MacroAsia’s biggest long-term aviation opportunity may lie in Clark, Pampanga.
In August 2026, Lufthansa Technik Philippines broke ground on a new aircraft maintenance complex covering approximately 157,000 square meters.
The facility is expected to begin operations in 2028.
It is designed to support major inspections, repairs and overhauls of large passenger aircraft.
The development is also expected to create approximately 1,200 skilled jobs.
These could include opportunities for aircraft mechanics, engineers, technicians and other aviation specialists.
The expansion is intended to increase LTP’s overall capacity rather than replace its existing Manila maintenance facilities.
That distinction is important.
The company is shifting away from one category of maintenance activity while expanding its capabilities in more extensive aircraft repair and overhaul work.
The long-term opportunity depends on securing aircraft maintenance contracts, maintaining high operational standards and ensuring that the expanded facility achieves adequate utilization.
However, the Clark project is not expected to begin operating until 2028.
It cannot be assumed to offset all of MacroAsia’s 2026 earnings decline immediately.
Clark’s Aviation Expansion Is Creating New Business Opportunities
LTP’s investment is part of a wider expansion of aviation and logistics infrastructure in Central Luzon.
Clark has attracted investment from airlines, cargo operators, airport service providers and logistics companies seeking alternatives to congested facilities in Metro Manila.
In related coverage, WWC ONE MEDIA examined UPS and Delbros Group’s more than $80 million investment in a major Clark air cargo hub, designed to handle up to 46,000 parcels daily.
That cargo facility is separate from Lufthansa Technik Philippines’ maintenance expansion.
However, both projects demonstrate increasing investment in Clark’s aviation-related infrastructure.
A growing aviation cluster can support specialized employment, supplier development and new technical services.
For maintenance providers, proximity to a major airport and supporting infrastructure may help attract additional airline customers.
But expansion alone does not guarantee commercial success.
Each project must generate sufficient operating activity and revenue to justify its investment.
MacroAsia’s Water Business Continues Growing
Beyond aviation, MacroAsia is developing its water services operations.
Revenue from the segment increased approximately 6% to ₱569.7 million during the first nine months of 2026.
The business also reported a 13% increase in billed water volume.
The growth reflects higher demand and a larger customer base.
Water operations provide MacroAsia with an additional source of revenue that is not directly dependent on passenger air travel.
The company is also pursuing major water infrastructure investments.
These include a surface-water facility in Pototan, Iloilo, designed to supply 50 million liters daily.
The project has a reported investment value of approximately ₱2 billion.
Another development involves a seawater desalination facility in Punta Engaño, Cebu, designed for a capacity of approximately 20 million liters daily.
The Cebu project is targeted to begin commercial operations by the end of 2026.
However, the expected commissioning dates and planned production capacities remain subject to actual project completion and operational readiness.
The facilities could expand MacroAsia’s long-term revenue base.
But they will also require effective project execution and cost management before investors can evaluate their financial returns.
Lucio Tan’s Aviation Businesses Face Rising Costs
MacroAsia’s difficult financial period coincides with broader pressure on the aviation industry.
Philippine Airlines, another major business associated with Lucio Tan, has also experienced rising operating costs.
PAL reported a ₱9.74-billion net loss during the first nine months of 2026 as fuel expenses surged nearly 50%.
In related reporting, WWC ONE MEDIA examined PAL’s ₱63.5-billion financial buffer and the airline’s efforts to manage higher fuel prices while preserving cash for operations and fleet investment.
The two companies face different financial challenges.
PAL is primarily an airline operator with substantial exposure to fuel costs, aircraft financing and passenger demand.
MacroAsia is a provider of food, airport and related services, with additional exposure to maintenance joint ventures.
The decision by PAL to bring more routine maintenance work in-house directly affects the business model of LTP.
However, it would be inaccurate to conclude from the available reporting that PAL made the decision solely because of its own financial losses.
The commercial rationale may involve operational control, efficiency, cost management or other considerations.
The confirmed development is that PAL’s internal maintenance shift contributed to LTP’s restructuring.
PAL’s Credit Profile Shows Why Aviation Cost Control Matters
The pressure to manage costs is also visible in the wider airline industry.
Philippine Airlines received an investment-grade BBB rating with a stable outlook from Japan Credit Rating Agency in October 2026.
But the rating assessment also identified challenges involving higher fuel expenses, debt and reduced earnings margins.
For airline operators, maintenance remains essential to safety and regulatory compliance.
The commercial question concerns how these services should be organized and financed.
Airlines may perform selected maintenance activities internally while outsourcing major overhauls or specialized repairs to independent providers.
That creates different opportunities for aviation service companies.
LTP’s decision to stop line maintenance while expanding heavy maintenance capabilities reflects a shift in its operating focus.
Whether the revised strategy produces stronger returns will depend on demand, contracts and the cost of providing those services.
Sangley Airport Could Create Long-Term Opportunities for Aviation Services
The Philippine aviation sector is also preparing for major infrastructure changes.
Plans to develop Sangley Point International Airport in Cavite could increase the long-term demand for aviation support facilities and related services.
MacroAsia has previously been identified among participants associated with the Sangley airport development consortium.
In another report, WWC ONE MEDIA examined GMR Group’s interest in the proposed ₱150-billion Sangley airport project and the hurdles that must be resolved before major construction can proceed.
The project remains subject to financing, regulatory and construction requirements.
MacroAsia’s involvement in earlier consortium arrangements should not be interpreted as a guarantee of specific future revenues.
However, broader airport development could eventually create opportunities for ground handling, catering, maintenance and other aviation-related businesses.
The commercial benefits will depend on the airport’s final development structure, operating arrangements and airline participation.
MacroAsia Management Promises Margin Recovery
MacroAsia president and chief operating officer Eduardo Luis T. Luy acknowledged the company’s financial challenges while emphasizing that its underlying businesses remain active.
Management identified inflation-related expenses, restructuring at LTP and higher lease costs as important pressures on earnings.
The company is pursuing measures intended to improve operating efficiency.
These include productivity improvements, procurement initiatives, shared services and possible pricing adjustments.
Management also continues investing in facilities intended to expand production capacity and diversify revenue.
The objective is to improve margins as exceptional restructuring costs ease and new businesses generate additional contributions.
However, the timetable for full earnings recovery remains uncertain.
Higher lease charges and other recurring expenses may continue affecting profitability.
The company must therefore demonstrate that its operating improvements are sufficient to offset these costs.
Five Financial Indicators MacroAsia Investors Should Watch
1. Recovery in earnings from Lufthansa Technik Philippines
The contribution from LTP will be important as restructuring expenses ease and the company adjusts to higher lease costs.
2. Food services margins
The segment is growing rapidly, but the company must convert rising meal volumes into stronger profits.
3. Ground handling profitability
Investors should monitor whether revenue growth can offset labor and airport-related costs.
4. Completion of the Muntinlupa commissary
The ₱1.2-billion expansion could support future growth, provided the additional capacity attracts sufficient demand.
5. Long-term returns from Clark and water infrastructure
The maintenance, water supply and desalination projects may diversify MacroAsia’s income sources, but their full financial benefits will depend on completion and commercial operations.
The Bottom Line: MacroAsia Is Growing, but Profits Are Under Pressure
MacroAsia’s latest results demonstrate an important reality of the aviation services industry.
Higher revenue does not always lead to higher profits.
During the first nine months of 2026, the company generated ₱7.76 billion in revenue, supported by growth in food services, airport ground handling and water operations.
But rising direct costs, higher operating expenses and reduced earnings from associated companies pushed attributable net income down 45.2% to ₱560.4 million.
The restructuring of Lufthansa Technik Philippines following PAL’s decision to handle more routine maintenance internally added pressure.
The business also faces higher recurring lease expenses at its Manila facilities.
Yet MacroAsia continues investing in its future.
A major aircraft maintenance complex is being developed in Clark, a larger food commissary is planned in Muntinlupa, and water infrastructure projects could expand revenue sources outside aviation.
Those investments create potential opportunities but do not guarantee a recovery.
For investors, the decisive issue is whether MacroAsia can restore profitability while managing the costs of its expansion.
Lucio Tan’s MacroAsia has seen its nine-month profit fall 45% even as revenue continues rising. But with Philippine Airlines shifting maintenance work in-house, Lufthansa Technik restructuring and billions of pesos committed to new facilities, can the aviation services giant rebuild its earnings—or could the cost pressures continue eating away at its profits?