MANILA, Philippines — November 5, 2026 | WWC ONE MEDIA | Philippine Business, Financial Technology & Startups
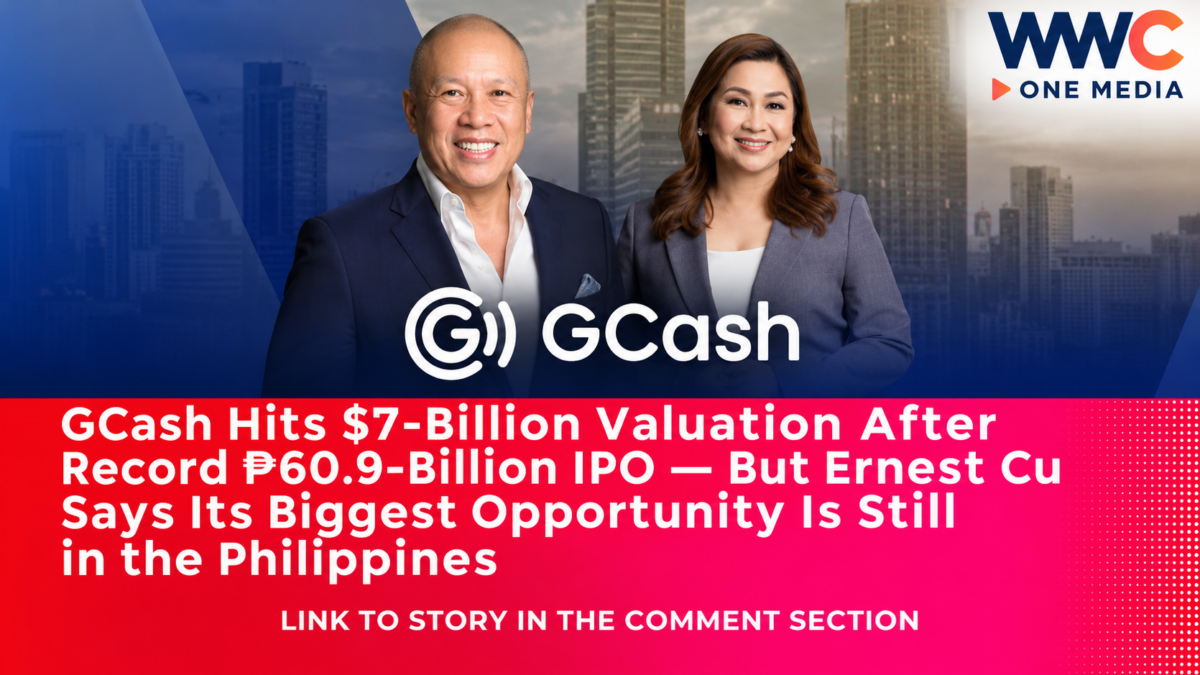
GCash has become one of the Philippines’ most valuable publicly traded companies, but chairman Ernest Cu believes its future depends less on conquering Southeast Asia and more on understanding the market that made it successful.
Speaking before venture capital investors and startup founders in Makati on November 4, Cu offered a striking message to Filipino entrepreneurs: pursuing growth across multiple countries does not automatically create a stronger business.
The discussion came just over two weeks after Mynt Inc., the company behind GCash, completed the largest initial public offering in Philippine stock-market history.
Mynt debuted on the Philippine Stock Exchange on October 20 with an equity valuation of approximately $7 billion, or ₱442 billion, after pricing its shares at ₱6.60 each.
The landmark offering raised approximately ₱60.9 billion through a combination of newly issued shares and shares sold by existing investors, including the overallotment.
Yet Cu’s message was not about how quickly companies can expand.
It was about knowing when to stop expanding, when to improve profitability and when to reject opportunities that could weaken the business.
According to InsiderPH’s November 5 account of the Kaya Founders annual LP Summit, Cu explained how GCash evolved from a small mobile-money service into a major digital financial platform.
His central argument was simple: technology alone is not enough to create a successful business.
But after reaching a $7-billion valuation and entering the public stock market, can GCash continue growing while resisting the temptation to expand beyond its strongest competitive advantage?
From an Overlooked Globe Business to a $7-Billion Fintech Giant
GCash began in 2004 as a mobile-money service operating primarily through text messages.
When Cu became president and CEO of Globe Telecom in 2009, digital financial services were still far from becoming part of everyday life for most Filipinos.
Smartphones were less accessible, mobile broadband remained limited and digital payments had not achieved widespread acceptance.
Cu recalled that GCash was not initially regarded as one of Globe’s most important businesses.
Its operations were relatively small compared with the telecommunications company’s core activities.
Rather than treat the service as a failed experiment, Cu eventually began assigning stronger management talent to the business.
The strategy helped prepare GCash for a period when smartphone adoption, mobile connectivity and demand for digital financial services would expand rapidly.
The transformation illustrates how an overlooked corporate division can become a major source of shareholder value.
However, GCash’s success also depended on resources that many independent startups do not possess.
Globe already had a nationwide distribution network, established customer relationships and significant experience managing large-scale consumer services.
Those advantages helped accelerate GCash’s adoption.
Why Ernest Cu Waited Before Scaling GCash
One of Cu’s most important lessons concerned timing.
He believed the opportunity for digital financial services existed long before the Philippine market was technologically ready for mass adoption.
Millions of Filipinos had limited access to traditional banking services.
But the ability to offer electronic payments at scale depended on mobile connectivity, smartphones and reliable transaction systems.
Expanding aggressively before those requirements were in place could have resulted in costly investments without sufficient customer demand.
Instead, Globe waited for the market to develop.
GCash subsequently benefited from technology provided through its partnership with Ant Financial, now part of Ant Group.
The partnership combined digital financial technology with Globe’s customer access and distribution capabilities.
The result was a business model that could eventually reach tens of millions of Filipinos.
The lesson for entrepreneurs is that identifying an opportunity is not the same as having the infrastructure needed to serve it profitably.
Globe’s Distribution Network Became a Competitive Advantage
The partnership with Ant provided important technology, but Globe contributed an equally valuable asset: distribution.
Cu explained that Globe sales personnel were given GCash-related business targets alongside their existing telecommunications responsibilities.
That allowed the fintech business to use an established nationwide organization rather than build every distribution channel independently.
The arrangement helped GCash connect with merchants and consumers.
For startups, this is a particularly important distinction.
Developing a useful app does not automatically solve the challenge of attracting customers.
A financial platform must also establish trust, support users and maintain accessible channels for payments and related transactions.
GCash benefited from a distribution network that already existed.
That advantage helped differentiate it from smaller financial technology companies entering the market without comparable resources.
The Pandemic Nearly Exposed a Dangerous Financial Problem
GCash experienced extraordinary growth during the COVID-19 pandemic as lockdowns and changing consumer behavior accelerated digital payments.
But Cu revealed that the growth created a serious financial challenge.
By the third quarter of 2020, the company was processing increasing transaction volumes while its cash-in subsidies exceeded the revenue generated from those activities.
In practical terms, certain transactions were costing the company more than it earned.
As transaction volumes increased, the unfavorable economics risked creating larger losses.
Cu recognized that this arrangement could not continue indefinitely.
Management renegotiated pricing agreements with business partners and worked to improve transaction profitability.
The experience reinforced a fundamental principle of business growth.
A company can attract millions of customers and process billions of pesos in transactions while still operating an unsustainable financial model.
Growth becomes valuable only when the underlying business can support it.
Why Profitability Matters More Than Vanity Metrics
Startup companies frequently emphasize customer acquisition, transaction volumes, geographical reach and other measures of growth.
Those metrics can demonstrate demand.
But they do not necessarily establish that a company is financially sustainable.
For a financial platform, the economics of each transaction matter.
Revenue must eventually cover the costs of technology, customer acquisition, partnerships, processing, cybersecurity and operations.
Cu’s experience demonstrates why rapid expansion can become dangerous when management does not understand the cost of serving additional customers.
The principle also applies to the broader Philippine fintech industry.
WWC ONE MEDIA previously examined this issue in Tala Expands Banking and Fintech Partnerships to Bring Loans to More Filipinos — But the Real Test Is Whether Borrowers Can Afford to Repay.
That report explored how digital lenders are developing partnerships to reach underserved customers.
Tala’s business is separate from GCash, but both illustrate the challenge of expanding access to financial services while maintaining sustainable economics.
For digital lenders, profitability must also be balanced with responsible underwriting and consumer protection.
Why GCash Refused to Conquer Southeast Asia
Perhaps Cu’s most surprising argument was his decision not to pursue aggressive expansion into neighboring markets.
According to InsiderPH, GCash received invitations to enter countries including Thailand, Indonesia and Malaysia.
But Cu questioned whether its competitive advantages would be equally strong outside the Philippines.
GCash benefited from Globe’s distribution network, relationships and understanding of Filipino consumers.
Those advantages would not automatically transfer to foreign markets.
Entering another country could require significant investment in marketing, regulatory compliance, partnerships, technology and customer acquisition.
The company would also face established competitors.
Cu’s position challenges a common assumption in venture capital: that technology companies must operate internationally to justify high valuations.
GCash demonstrates that a company focused primarily on a sufficiently large domestic market can still become a multibillion-dollar business.
The strategy does not reject international opportunities altogether.
Instead, it places greater emphasis on serving the customers the company understands best.
Overseas Filipinos Remain Part of the Growth Strategy
GCash has continued expanding its international services, particularly for Filipinos living and working abroad.
That differs from attempting to compete directly for every consumer in a foreign country.
Overseas Filipinos may already have financial relationships with relatives and businesses in the Philippines.
Services involving cross-border payments and remittances can therefore extend GCash’s existing customer ecosystem.
This approach allows the company to pursue international transactions while maintaining a strong connection to its original market.
However, operating internationally still involves financial regulations, security requirements, partnerships and compliance responsibilities.
The strategy does not eliminate the risks of cross-border financial services.
It simply focuses on markets where management believes the business has a clearer advantage.
GCash Makes Philippine Stock Market History
The October 20 IPO marked a major milestone for the Philippine technology industry.
According to the Philippine Stock Exchange, Mynt raised ₱60.9 billion through the landmark offering.
The company’s shares began trading under the ticker symbol GCASH.
The listing gave investors an opportunity to buy shares in the business behind one of the country’s most widely used digital financial platforms.
WWC ONE MEDIA covered the milestone in GCash Parent Mynt Makes Stock Market History With ₱60.9-Billion IPO — But Can Its Shares Keep Rising?.
The report examined Mynt’s transition from a private fintech business into a publicly listed company.
The IPO attracted substantial interest because of its size and the company’s position in Philippine digital finance.
But investors should distinguish the company’s market valuation from the capital it received.
The approximately $7-billion figure describes the equity value implied by the listing price.
The ₱60.9-billion IPO involved both primary shares, which raise money for the company, and secondary shares sold by existing shareholders.
Not all proceeds represented fresh capital entering Mynt.
BlackRock, Citadel and Other Investors Join the IPO
The offering also attracted major international institutional investors.
The investor group included companies such as BlackRock, Citadel and other global investment managers.
WWC ONE MEDIA examined the international interest in GCash’s Record ₱60.9-Billion IPO Draws BlackRock, Citadel and Global Investors — But the Real Test for Philippine Tech Begins Now.
The participation demonstrated substantial investor interest in a Philippine digital financial company.
However, institutional participation does not guarantee future share-price appreciation.
The stock market will evaluate Mynt’s earnings, growth prospects, valuation and risk profile over time.
Reuters reported that Mynt’s shares closed their first trading day at ₱6.60, unchanged from the offer price.
That gave the company a market capitalization of approximately ₱442 billion.
The relatively subdued opening performance demonstrated that even a record IPO does not guarantee immediate gains for investors.
GCash Lets Filipinos Participate in Its IPO Through the App
The listing also introduced an unusual opportunity for retail investors.
Eligible users could subscribe to Mynt shares through GStocks PH within the GCash app.
The minimum application involved 100 shares at ₱6.60 each, or ₱660.
WWC ONE MEDIA covered the program in Mynt IPO Opens to Retail Investors Through GStocks PH at ₱6.60 Per Share.
The arrangement made the offering accessible through a platform already familiar to millions of Filipinos.
However, buying shares in Mynt is different from holding money in a GCash wallet.
An equity investment is exposed to market-price fluctuations and potential losses.
The accessibility of a stock purchase does not remove investment risk.
For GCash, the initiative also illustrated how its financial ecosystem could connect digital payments with investment services.
GCash Has Become a Profitable Digital Finance Business
Mynt entered the stock market with a substantial operating business.
Reuters reported that GCash had approximately 41.5 million monthly active users during the first half of 2026.
The platform processed approximately ₱9.84 trillion in transactions over that period.
Mynt’s first-half revenue increased 10.4% to ₱43.27 billion.
Net income rose 7.3% to ₱10.82 billion.
These figures provide evidence that GCash has moved beyond the early stage of attracting customers without a sustainable profit base.
But different measures should not be confused.
Monthly active users are not the same as total registered accounts.
Transaction value is not company revenue.
Likewise, a reported company valuation is not equivalent to annual profit.
These distinctions matter when assessing the actual scale and economics of a fintech company.
Lending Becomes the Next Major Opportunity
GCash is expanding beyond consumer payments into lending, merchant services and other financial products.
At the Kaya Founders event, Cu said the group’s lending portfolio had already exceeded $1 billion.
He explained that transaction data can help the company understand customer behavior and assess borrowing risk.
For consumers and small businesses with limited conventional credit histories, alternative data may support access to formal lending.
However, digital lending brings risks that differ from payments.
Borrowers must have the capacity to repay.
Lenders must manage defaults, fraud and responsible credit assessment.
The company’s ability to grow its lending portfolio does not automatically establish that every new loan is profitable or appropriate for the borrower.
Cu also acknowledged that competitors are developing similar credit-scoring technologies.
The advantage GCash once held through its transaction data could therefore become less exclusive.
Merchant services may become increasingly important as the company seeks additional information about business activity and new sources of revenue.
The Biggest Risk May Be Losing Consumer Trust
While investors often focus on revenue growth and valuation, Cu identified another concern as particularly important: the possibility of losing public confidence.
Financial technology companies depend on trust.
Customers expect payment systems to work reliably and their funds and information to be protected.
A major cybersecurity incident, operational outage or failure to address customer complaints can damage that confidence.
GCash reportedly processes more than 60 million transactions daily, according to Cu’s interview.
At that scale, even a relatively small operational problem can affect large numbers of users.
The challenge becomes more complex as a platform adds lending, investment, savings and other financial services.
Each new product can create additional technology, compliance and customer-protection responsibilities.
For Mynt, maintaining secure and reliable services may be as important as attracting additional users.
Public Market Investors Will Demand Consistent Results
The IPO changed GCash’s relationship with investors.
Previously, the business answered primarily to its private shareholders.
As a publicly listed company, Mynt must also meet the expectations of public-market investors and comply with continuing disclosure requirements.
Cu acknowledged that the company must consistently deliver financial results.
Its first post-listing earnings call is scheduled for November 10, 2026.
Investors will be watching the performance of the payments business, digital lending, merchant services and other revenue sources.
They will also assess whether the company can maintain profitability while investing in growth.
The financial results may influence perceptions of Mynt’s valuation.
However, the November 10 earnings call has not yet occurred as of this November 5 report.
No figures from that upcoming release should be treated as already announced.
What Independent Reporting Confirms
InsiderPH’s November 5 interview provides Cu’s account of GCash’s early development, its pandemic-era challenges and his decision to prioritize the Philippine market.
A separate essay published by Oblique Asia, written from the perspective of an attendee working in the Philippine fintech industry, independently examines the same Kaya Founders discussion.
That account also highlights the importance of distribution, profitability, IPO planning and the company’s decisions about geographic expansion.
Reuters independently confirms Mynt’s October 20 stock-market debut, ₱60.9-billion IPO and approximately $7-billion valuation.
The Philippine Stock Exchange confirms that Mynt completed the largest IPO in its history.
GMA News independently documented the listing price and opening market capitalization.
These reports establish the financial significance of the IPO and corroborate the setting of Cu’s remarks.
However, the detailed internal history of GCash’s cost negotiations and earlier management decisions largely comes from Cu’s retrospective account.
Those details should be presented as his recollections rather than as independently audited operational findings.
The Bottom Line: GCash’s Next Test Is More Than Growth
Ernest Cu’s latest message challenges the conventional belief that successful technology companies must expand aggressively into international markets.
GCash reached a valuation of approximately $7 billion by building a powerful business within the Philippines.
It benefited from Globe’s existing distribution network, technology partnerships and the rapid adoption of mobile payments.
But Cu’s experience also demonstrates the importance of understanding transaction economics.
During the pandemic, rapid growth created serious financial pressure until the company improved its arrangements with partners.
Today, GCash is profitable, publicly listed and expanding into additional financial services.
The challenge is different from the one it faced during its early years.
Management must balance growth with profitability, innovation with cybersecurity, and new opportunities with the competitive advantages that made the business successful.
GCash has demonstrated that a Philippine-focused fintech company can become a multibillion-dollar enterprise. The harder question is whether it can sustain that success while resisting costly distractions.
As GCash enters life after its historic IPO, will Ernest Cu’s strategy of focusing on the Philippine market protect its $7-billion valuation—or could growing competition in digital lending, payments and financial services force the company to rethink the formula that made it successful?