
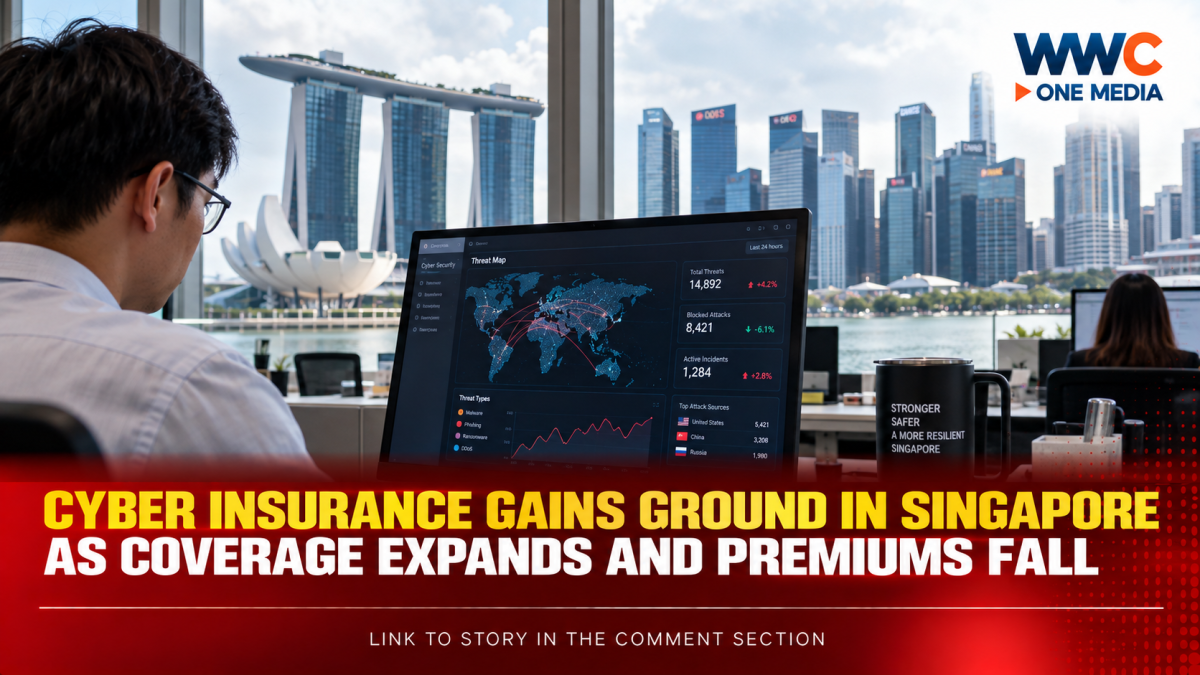
SINGAPORE — Cyber insurance is gaining traction among Singapore businesses as companies confront increasingly sophisticated digital threats, while greater competition among insurers is helping push premiums lower.
The shift is particularly visible among small and medium-sized enterprises (SMEs) and mid-market companies, according to insurers and brokers surveyed by The Straits Times. Eight industry players reported stronger demand, with some seeing particularly noticeable growth over the past two to three years.
The development reflects a growing recognition among businesses that cybersecurity is no longer solely an IT issue. A major cyber incident can disrupt operations, expose customer information and create significant legal, recovery and business-interruption costs.
More companies are looking for protection
Cyber insurance policies can cover a range of expenses associated with cyber incidents, depending on the policy.
Coverage may include incident response, forensic investigation, legal expenses, notification costs, business interruption and certain third-party liabilities. Some policies can also provide access to specialist response teams following an incident.
Munich Re says cyber insurance can cover losses stemming from hacking, data breaches, software vulnerabilities and other cyber events, with policies potentially addressing both first-party and third-party costs.
For smaller companies in particular, access to these response capabilities can be as important as the financial compensation itself.
Why are premiums falling?
The apparent contradiction at the heart of the market is that cyber threats are increasing while insurance prices are declining.
The explanation lies partly in the insurance market itself.
Howden’s 2026 cyber-market report says cyber premiums declined for a fourth consecutive year in the first half of 2026. It attributes the soft pricing environment to abundant insurance capacity and intense competition among carriers.
Reuters has similarly reported that global cyber rates fell for a 12th consecutive quarter in the second quarter of 2026, with competition and excess capacity putting downward pressure on prices.
For businesses, that creates an unusual opportunity: broader or more competitive coverage can become available at a lower cost.
But insurers face a difficult question — how low can premiums go before pricing stops reflecting the underlying risk?
Singapore’s market still has room to grow
Despite rising interest, cyber insurance is far from universal among Singapore businesses.
Chambers’ 2026 Singapore insurance guide cited data indicating that fewer than 40% of SMEs held cyber insurance in 2025, suggesting a significant protection gap remains.
Market research also points to continued expansion. Mordor Intelligence estimates Singapore’s cyber-insurance market could grow from about US$61.8 million in 2026 to US$94.7 million by 2031, representing an estimated annual growth rate of 8.93%.
The figures vary depending on methodology and market definition, but they point in the same direction: cyber insurance remains a developing market rather than a mature one.
AI is creating a new insurance headache
The next challenge may come from artificial intelligence.
AI is making it easier for organizations to automate business processes, but it is also changing the nature of cyber threats.
Reuters reported in August that insurers are adapting policy language to address risks involving autonomous AI agents, which can potentially perform actions without direct human instruction. Traditional cyber policies may not always fit situations where an AI system causes damage without a conventional hacking event.
That creates difficult questions for insurers.
Who is responsible when an AI system makes an unauthorized decision? Does a conventional cyber policy respond? How should insurers price a risk for which there is relatively little historical claims data?
Those questions are likely to become increasingly important in Singapore’s highly digital economy.
Falling prices don’t mean falling danger
The biggest misconception businesses could make is assuming cheaper insurance means cyber threats have become less serious.
The opposite may be true.
Howden reported record ransomware activity in the first half of 2026, alongside a continued shift toward data theft and greater regulatory scrutiny following breaches.
Munich Re has likewise warned that the majority of cyber risks remain uninsured, despite the growing availability of insurance products.
The protection gap therefore remains a central issue.
Insurance can help transfer financial risk, but it does not replace strong cybersecurity, employee awareness, backup systems or incident-response planning.
Singapore’s cyber-insurance market enters a crucial phase
Singapore’s growing adoption of cyber insurance highlights a broader change in how businesses view digital risk.
Cybersecurity was once largely treated as a technical problem handled by IT departments. Increasingly, it is becoming a financial, operational and board-level risk.
For businesses, falling premiums could make coverage more accessible. For insurers, however, the challenge is ensuring that aggressive competition does not result in inadequate pricing or coverage that fails when a major claim arrives.
That tension could shape the next phase of Singapore’s cyber-insurance market.
Cyber insurance may be getting cheaper, but the risks it is designed to cover are becoming more complex. For Singapore businesses, the real question may no longer be whether to insure against cyber threats — but whether their coverage is strong enough when the next major attack arrives.
Leave a Reply