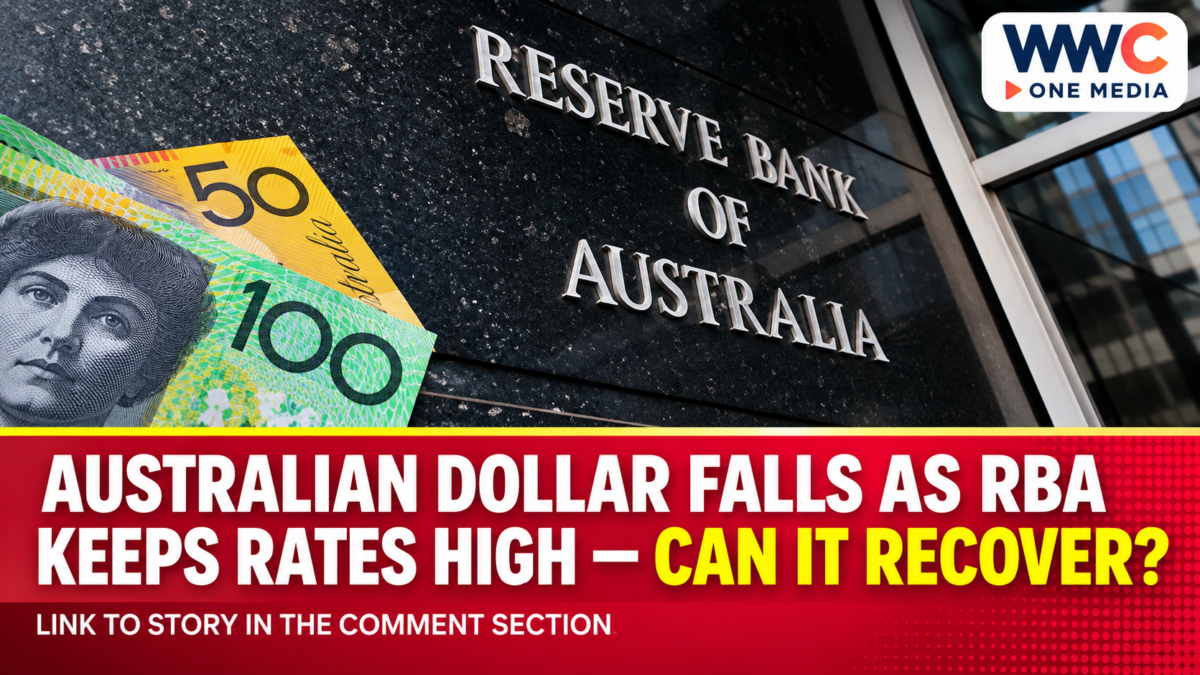
The Australian dollar weakened against the US dollar in the Reserve Bank of Australia’s official exchange-rate observations through Nov. 18, 2026, slipping to US$0.6720 from US$0.6742 a day earlier. The decline came after the central bank increased its cash-rate target to 4.85% earlier in November, leaving traders to weigh restrictive borrowing conditions against still-elevated inflation.
This Australian dollar outlook requires a distinction between exchange-rate facts and predictions about future rate cuts. The latest official readings demonstrate a near-term currency decline, but they do not establish that all of 2026’s earlier gains have disappeared or that the RBA has committed to easing.
Australian dollar outlook: what the official prices show
The RBA recorded US$0.6759 per Australian dollar on Nov. 16, US$0.6742 on Nov. 17 and US$0.6720 on Nov. 18. Each quote shows how many US dollars one Australian dollar could buy in the bank’s published reference series; a falling number indicates a weaker Australian dollar against the greenback.
The November minutes offer a different, longer-term comparison. At the Nov. 2–3 meeting, policymakers assessed the Australian dollar as approximately 5% stronger since the start of the year on a nominal trade-weighted basis. A trade-weighted index measures the currency against a basket of trading partners, not just the US dollar, and its movement cannot be equated with AUD/USD performance.
The observations establish neither a full-year currency loss nor the rate Australians would receive from an individual bank or money-transfer provider. The claim that the currency is certain to surrender its 2026 gain remains a forecast rather than an official result.
Analysis: A few weaker trading sessions can coexist with a stronger year-to-date trade-weighted exchange rate. Readers should specify the currency pair, starting date and measurement before drawing conclusions about a rally or reversal.
RBA’s November move was a rate increase, not a cut
On Nov. 3, the Monetary Policy Board voted six to three to increase the cash-rate target by 25 basis points to 4.85%, effective Nov. 4. Three members preferred to keep the rate at 4.60%. That is the bank’s most recent completed decision, not a confirmed easing cycle.
The bank’s minutes show that policymakers had been concerned about stronger-than-expected inflation and uncertainty over how restrictive financial conditions really were. The board considered both leaving rates unchanged and raising them, ultimately choosing the increase by majority vote.
WWC previously examined the divided November RBA rate decision. The new currency figures are a separate development and should not be treated as evidence of another monetary-policy announcement.
Why it matters: Interest-rate expectations can influence demand for a currency, but they compete with global dollar moves, commodity prices and changing investor appetite for risk. A single trading-day decline cannot identify one decisive cause.
Inflation and wages complicate the case for easing
Australia’s annual consumer-price inflation was 4.3% in September, up from 4.0% in August, exceeding the RBA’s 2%–3% target range. The bank’s November economic outlook said inflation was expected to remain high for longer, with a return to the middle of the target band not projected until mid-2028.
New figures released Nov. 18 showed the Wage Price Index rising 1.1% in the September quarter and 3.5% over the year. Public-sector wages rose 1.3% over the quarter and private-sector wages rose 1.0%. These are movements in an index of wage rates, not an individual pay guarantee.
WWC’s report on Australia’s September-quarter wage acceleration provides more detail on how pay growth and living costs interact. For the exchange-rate debate, wages are relevant because they can affect demand and business costs, although one quarterly reading does not dictate the RBA’s next vote.
Analysis: A central bank facing above-target inflation may have less room to reduce rates quickly than a simple currency-market prediction implies. Conversely, a sharper slowdown could change its assessment. Both paths remain conditional on data.
The exchange rate responds to more than Australian rates
The RBA’s November minutes discussed global uncertainty, higher oil prices and changing expectations for monetary policy. They also recorded that domestic housing turnover had weakened and household loan payments had risen, suggesting restrictive financial conditions.
An international investor choosing between Australian-dollar and US-dollar assets considers both expected interest rates and exchange-rate risk. Even a comparatively high Australian cash rate does not guarantee a stronger Australian dollar when market expectations change or global investors prefer US-dollar liquidity.
WWC previously covered the Australian dollar’s October strength during a broader US-dollar retreat. That historical market episode highlights why dollar strength or weakness can shift the apparent performance of its Australian counterpart without any immediate change in the RBA’s rate.
For Philippine readers, AUD/USD is not the same as AUD/PHP. The peso cost of Australian education, travel or imports depends on the relevant cross-rate and fees. No precise peso saving or cost increase can be derived from the US-dollar quotation alone.
What the next policy decision can actually settle
The RBA’s published schedule sets the next monetary-policy decision for Dec. 8, 2026. Its November statement projected that inflation would remain elevated and emphasised returning price increases to the 2%–3% target range, but it did not promise a particular decision for December.
New data may alter the balance between prices and demand. Meanwhile, additional daily reference exchange rates will show whether the Nov. 18 currency decline extends or reverses.
Analysis: Investors should distinguish a forecast of rate cuts from a decision to cut rates. What matters is not only whether the policy rate eventually falls but whether the outcome differs from what market participants have already anticipated.
What happens next
The verified position as of Nov. 19 is straightforward: the Australian dollar weakened against the US dollar in the RBA’s latest published observations, while Australia’s most recent rate decision was an increase to 4.85%. The bank’s next meeting is still ahead, and the available official records do not establish that the currency has erased all gains made in 2026.
The practical test will be subsequent RBA guidance, inflation data and actual exchange-rate observations. None supplies a guaranteed trading outcome, and the Australian dollar could move in either direction as conditions change.
FAQ
What was the Australian dollar worth on Nov. 18, 2026?
The Reserve Bank of Australia’s reference series showed US$0.6720 per Australian dollar on Nov. 18, compared with US$0.6742 on Nov. 17.
Has the RBA begun cutting interest rates?
No. The latest completed policy decision, on Nov. 3, raised the cash-rate target by 25 basis points to 4.85%.
Has the Australian dollar lost all its 2026 gains?
The official figures reviewed do not establish that claim. The RBA’s November meeting minutes said the trade-weighted currency was about 5% above its start-of-year level at the time of the meeting.
When is the next RBA interest-rate decision?
The next decision is scheduled for Dec. 8, 2026. No outcome has been announced in advance.