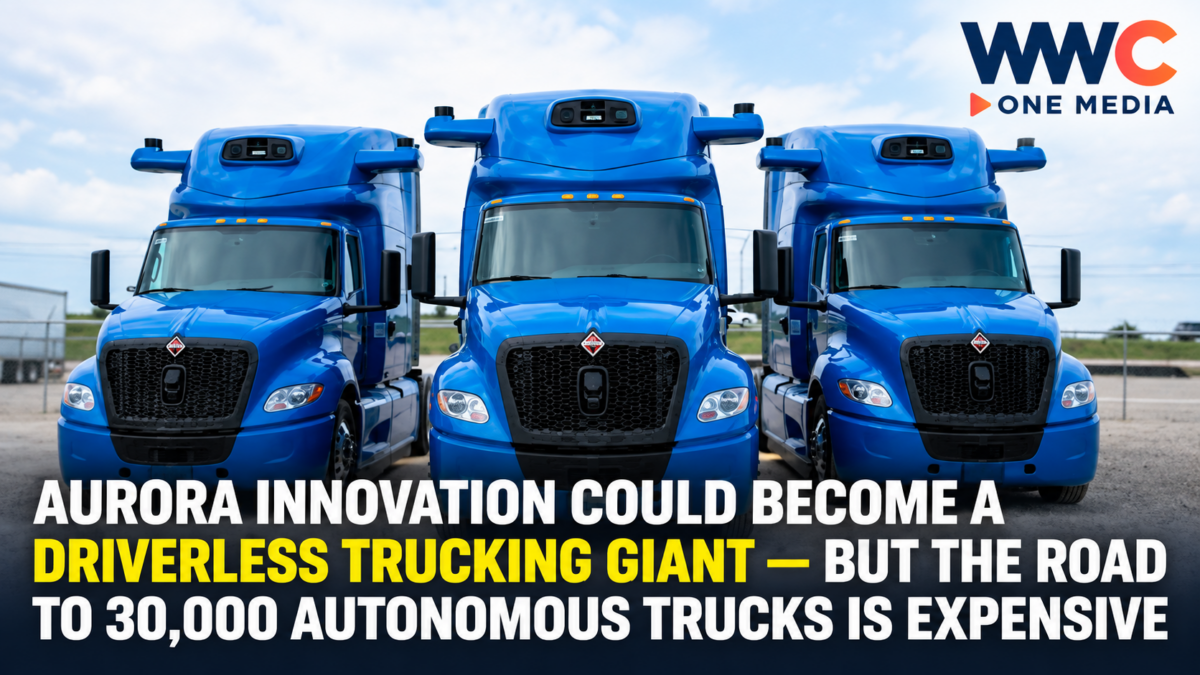
DALLAS — One of Wall Street’s most aggressive driverless-trucking bets is moving from science experiment to commercial freight operation, with Aurora Innovation already hauling loads on public highways without anyone behind the wheel and laying out a plan to scale from hundreds of autonomous trucks to more than 30,000 by the end of the decade.
That explosive growth target is why Aurora has become one of the most closely watched autonomous-vehicle stocks in the market.
The company says it has reached what CEO Chris Urmson calls a:
“commercial inflection point.”
Aurora has already completed more than:
500,000 fully driverless commercial miles
since launching autonomous freight operations.
It plans to finish 2026 with approximately:
200 driverless trucks
in operation.
By 2030, management wants more than:
30,000 trucks
powered by its autonomous-driving system.
If that happens, Aurora says annual revenue could exceed:
$5 billion.
The company is also targeting gross margins of roughly:
60%.
Those numbers explain why some analysts believe Aurora shares could rise dramatically if management executes.
But the same numbers reveal the risk.
Aurora is attempting to scale a business that today still generates only millions of dollars in revenue while consuming hundreds of millions of dollars in cash.
AURORA IS ALREADY OPERATING TRUCKS WITHOUT A DRIVER
Aurora is no longer testing only with safety drivers.
In April 2025, the company launched regular driverless commercial operations on the:
Dallas-to-Houston freight corridor.
Its trucks began carrying freight for customers including:
Uber Freight
and
Hirschbach Motor Lines.
There is no human driver sitting behind the wheel during these operations.
That separates Aurora from many autonomous-trucking companies still operating primarily in supervised testing.
The company says its trucks now routinely carry paying commercial freight.
THE DALLAS-HOUSTON LANE IS THE STARTING POINT
Aurora chose Texas for a reason.
The Dallas-Houston freight corridor offers:
High freight volume
Long highway stretches
Predictable routes
and
A relatively favorable regulatory environment.
Highway trucking is also a more controlled problem than urban robotaxis.
A long-haul truck spends much of its journey on interstate highways rather than navigating:
Pedestrians
Cyclists
Complex intersections
and
Dense city traffic.
Aurora believes this makes freight one of the most commercially attractive first uses for autonomous driving.
THE TRUCKS HAVE NOW DRIVEN MORE THAN 500,000 DRIVERLESS MILES
Aurora says its autonomous fleet has completed:
more than 500,000 driverless commercial miles.
That is a significant milestone.
Autonomous systems need enormous amounts of real-world exposure to demonstrate performance across:
Traffic
Lane changes
Construction zones
Merging vehicles
Emergency situations
and
Changing weather.
Every additional mile provides more operational data.
But mileage alone does not prove long-term commercial success.
The real test is whether those miles can be converted into:
Safe operations
High truck utilization
and
Profitable customer contracts.
AURORA SAYS ITS DRIVERLESS TRUCKS WORK MUCH HARDER THAN HUMAN-DRIVEN ONES
One of the biggest economic arguments for autonomous trucking is utilization.
Human truck drivers face legal limits on how many hours they can drive.
They also need:
Sleep
Meal breaks
and
Time off.
Aurora says its autonomous trucks used by customers including McLane and Werner are operating at an annualized rate above:
225,000 miles per year.
That is more than:
twice the utilization
of a typical human-driven truck, according to the company.
If that level can be sustained, the economics could become compelling.
A truck that runs more miles spreads its fixed cost across more freight.
THIS IS WHY TRUCKING MAY BE EASIER TO MONETIZE THAN ROBOTAXIS
Robotaxis receive much of the public attention.
But autonomous trucking may have a simpler economic argument.
A trucking company already pays for:
A tractor
Fuel
Maintenance
Insurance
and
A driver.
If autonomous software can reduce the human-driving requirement on long-haul routes, the savings are easier to quantify.
The truck may also operate longer each day.
That means the customer could get:
More freight movement
from
The same physical vehicle.
The challenge is proving that the technology is reliable enough to justify its cost.
AURORA WANTS 200 DRIVERLESS TRUCKS BY YEAR-END
Aurora says its supply for 2026 is already fully allocated.
Management expects to exit the year with:
more than 200 driverless trucks
in operation.
That would represent a major increase from its original small commercial fleet.
Aurora estimates those 200 trucks would translate into an annualized Transport-as-a-Service revenue run rate of about:
$80 million.
That is a dramatic increase relative to current reported revenue.
But it is still only the beginning of the company’s plan.
THE REAL BUSINESS MODEL CHANGES IN 2027
Aurora currently operates much of its business under a:
Transport as a Service, or TaaS, model.
Under TaaS, Aurora owns or controls the truck and charges customers for moving freight.
That requires substantial capital.
Aurora must help fund:
Vehicles
Maintenance
Operations
and
Fleet infrastructure.
Beginning in 2027, Aurora wants to transition toward what it calls:
Driver as a Service, or DaaS.
That model is much more important to the long-term investment story.
DRIVER AS A SERVICE COULD MAKE AURORA MUCH MORE ASSET-LIGHT
Under DaaS, customers would own and operate the trucks.
Aurora would provide:
The autonomous-driving system
Software
Hardware
Remote support
and
Ongoing updates.
In theory, this means Aurora would not need to fund thousands of expensive trucks itself.
Its customers would provide the vehicles and capital.
Aurora would sell the technology layer.
That could make the company much more:
Scalable
and
High-margin.
It is one reason management believes gross margins could eventually approach software-like levels.
HIRSCHBACH PLANS 500 AURORA-POWERED TRUCKS
One of the strongest pieces of evidence behind the DaaS model is Hirschbach.
The trucking company intends to own and operate:
500 Aurora-powered trucks.
Deliveries are expected to begin in:
2027.
That arrangement is strategically important because it shifts vehicle ownership away from Aurora.
Instead of buying hundreds of trucks itself, Aurora can generate recurring revenue from the autonomous-driving system installed on customer-owned vehicles.
If that model works with Hirschbach, it could become the template for other fleet operators.
WERNER IS ALSO TALKING WITH AURORA
Aurora has also worked with major trucking company:
Werner Enterprises.
The companies have already hauled commercial freight together.
Werner is now discussing the economic and contractual structure for future autonomous deployments.
That shows Aurora has interest from established freight carriers.
But it also highlights an important risk.
Potential customers still need to be convinced the economics work.
A technology can function technically while still being too expensive commercially.
30,000 TRUCKS BY 2030 IS THE BIG TARGET
Aurora’s Investor Day laid out an aggressive long-term goal.
By 2030, management wants:
more than 30,000 driverless trucks
operating on the road.
If reached, Aurora projects annual revenue above:
$5 billion.
That would represent a completely different company from the Aurora that exists today.
The business currently generates only a small amount of revenue.
Reaching $5 billion would require extraordinary scaling across:
Truck manufacturing
Customer adoption
Service networks
Mapping
Maintenance
and
Regulatory coverage.
AURORA IS TARGETING AROUND 60% GROSS MARGINS
Management also says the mature business could generate:
roughly 60% gross margins.
That is unusually high for the trucking industry.
Traditional transportation businesses often operate on thin margins.
Aurora’s margin target depends on becoming a technology provider rather than a conventional fleet operator.
Once customers own the physical trucks, Aurora could potentially collect recurring fees for:
Autonomous-driving software
and
Associated services.
That is why investors sometimes compare Aurora’s long-term model more closely with software than transportation.
THIS IS WHAT MAKES THE STOCK SO SPECULATIVE
Aurora today is valued largely on:
what it could become
rather than
what it currently earns.
In Q2 2026, Aurora generated only:
$2 million in revenue.
For the first half of the year, total revenue was:
$3 million.
Yet the company has traded at a market capitalization measured in the:
billions of dollars.
That gap between current revenue and market value means investors are pricing in substantial future success.
If Aurora reaches tens of thousands of trucks, today’s valuation could look very different.
If the rollout stalls, the current valuation could prove difficult to justify.
OPERATING LOSSES ARE STILL ENORMOUS
Aurora reported a Q2 operating loss of:
$266 million.
That included approximately:
$60 million
of stock-based compensation.
Research and development expenses remain extremely high because Aurora is still investing heavily in:
Autonomous software
Sensors
Hardware
Safety validation
and
Future truck platforms.
The company posted a net loss of:
$270 million
for the quarter.
For the first six months of 2026, net losses reached:
$493 million.
So despite the commercial milestones, Aurora remains far from profitability.
CASH BURN IS THE MOST IMPORTANT NEAR-TERM RISK
Aurora used approximately:
$225 million
of operating cash during Q2.
The company expects average quarterly cash use of about:
$190 million to $220 million
during 2026.
It also expects around:
$150 million
in full-year capital expenditures.
At that burn rate, funding matters almost as much as technology.
Aurora needs enough liquidity to survive until its commercial fleet becomes large enough to generate meaningful revenue.
AURORA HAS ABOUT $1.2 BILLION IN LIQUIDITY
At the end of Q2, Aurora reported nearly:
$1.2 billion
in cash and short-term investments.
That provides an important financial cushion.
But if the company continues burning roughly $200 million per quarter, that money can disappear relatively quickly.
Management expects scaling revenue to gradually improve the picture.
But there is little room for a multi-year commercial delay without additional financing.
AURORA HAS ALREADY ISSUED MORE STOCK
Dilution is another risk shareholders need to understand.
During Q2, Aurora issued:
30 million new Class A shares
through its at-the-market stock program.
That raised approximately:
$215 million in net proceeds.
The company used part of the money for:
Cash bonuses
and
Employee tax obligations,
and increased liquidity by roughly:
$126 million.
Selling stock strengthens the balance sheet.
But it also increases the number of shares outstanding.
That means each existing investor owns a slightly smaller percentage of the company.
MORE FUNDRAISING COULD HAPPEN
Aurora may eventually need additional capital depending on:
Cash burn
Truck rollout speed
and
Customer adoption.
That funding could come from:
More stock issuance
Debt
Strategic partners
or
Customer financing.
The move toward Driver as a Service is designed partly to reduce the amount of capital Aurora itself must provide.
But until that model reaches scale, financing remains one of the biggest risks.
AURORA HAS A POWERFUL GROUP OF INDUSTRY PARTNERS
One reason investors remain interested is Aurora’s partner network.
The company works with organizations including:
Uber
Toyota
AUMOVIO, formerly Continental
and major freight carriers.
These partnerships are strategically important because Aurora does not want to manufacture everything itself.
Instead, it wants other companies to handle:
Vehicle manufacturing
Fleet ownership
and
Freight operations.
Aurora concentrates on what it believes is its biggest competitive advantage:
the autonomous-driving system.
CONTINENTAL IS CRITICAL TO MASS PRODUCTION
One of Aurora’s most important partnerships is with:
Continental, now operating under the AUMOVIO name.
The supplier is helping industrialize and manufacture hardware for the Aurora Driver.
That relationship matters because moving from:
200 trucks
to
30,000 trucks
is not merely a software challenge.
The hardware must be manufactured:
Reliably
Cheaply
and
At automotive scale.
That is a very different task from building small prototype fleets.
AURORA USES ITS OWN LONG-RANGE LIDAR
Aurora’s technology stack includes its proprietary:
FirstLight lidar.
Lidar uses laser pulses to measure the environment around the vehicle.
Aurora says its long-range sensing is particularly important for trucking.
An 80,000-pound truck traveling at:
65 miles per hour
takes much longer to stop than a passenger car.
The system therefore needs to detect hazards far down the road.
Aurora believes long-range lidar provides a safety advantage for autonomous trucking.
SAFETY IS THE ENTIRE BUSINESS
One serious accident could become a major setback.
That is the reality of autonomous transportation.
Aurora says it developed a formal:
Safety Case
before launching fully driverless operations.
The company argues its system is designed to handle failures through redundant systems and minimal-risk maneuvers.
But large-scale commercial deployment will create situations impossible to reproduce perfectly in testing.
Those can include:
Unexpected road debris
Extreme weather
Emergency vehicles
Construction
and
Human drivers behaving unpredictably.
Every new operating lane increases complexity.
WEATHER IS STILL A LIMITATION
Aurora’s initial operations have focused heavily on favorable environments.
The company has been working to expand capabilities into:
Night driving
Heavy traffic
Construction zones
and
More difficult weather.
Reuters previously reported Aurora planned to introduce harsh-weather capability only after its initial commercial deployment.
That matters because true nationwide trucking requires operations through:
Rain
Snow
Fog
and
Changing road conditions.
Texas is a starting point.
It is not the entire U.S. freight network.
EXPANSION INTO NEW LANES IS ESSENTIAL
A trucking network creates more value as the number of routes increases.
A Dallas-Houston lane is commercially useful.
But customers eventually want freight moved across:
Texas
Arizona
New Mexico
California
The Midwest
and beyond.
Aurora plans to gradually expand its Operational Design Domain across major U.S. freight corridors.
The faster it can safely add lanes, the larger its addressable market becomes.
DRIVERLESS TRUCKING COULD TRANSFORM FREIGHT ECONOMICS
The potential opportunity is enormous.
Long-haul trucking is expensive partly because humans can drive only limited hours.
Autonomous trucks could operate closer to:
24 hours per day
with pauses mainly for:
Fuel
Loading
Maintenance
and
Inspection.
That could reduce freight transit times.
A route that normally requires a human driver to stop for rest could potentially keep moving.
That has implications for:
Inventory
Warehousing
Supply chains
and
Delivery speed.
HUMAN DRIVERS WOULD NOT NECESSARILY DISAPPEAR
Driverless trucking does not automatically mean the end of truck-driving jobs.
Early autonomous systems are focused primarily on:
Long-haul highway segments.
Humans may still handle:
First-mile pickup
Last-mile delivery
Urban roads
Loading
and
Customer interactions.
This could create a hub-to-hub system.
A human driver moves a trailer to an autonomous terminal.
The robot truck handles the long highway portion.
Another human handles the final destination.
That could change trucking jobs rather than eliminate all of them.
THE ECONOMIC QUESTION IS COST PER MILE
For fleet operators, the central question is not whether autonomous trucks look impressive.
It is:
How much do they cost per mile?
Carriers will compare autonomous operations with:
Driver wages
Fuel
Maintenance
Insurance
Truck financing
and
Utilization.
Aurora needs its DaaS fee to be low enough that carriers save money while high enough for Aurora to earn strong margins.
That balance will determine adoption.
COMPETITION IS GETTING STRONGER
Aurora is not alone.
Kodiak AI is preparing to launch unsupervised driverless long-haul service on the same:
Dallas-Houston corridor
by the end of 2026.
Kodiak says it is already completing end-to-end deliveries on the route without human intervention during validation runs.
Other competitors include:
Torc Robotics
and technology efforts tied to major truck manufacturers.
Tesla is also developing autonomous capabilities around its Semi platform.
The market may ultimately support several providers.
But first-mover advantage could matter enormously.
KODIAK IS CHASING THE SAME LANE
Kodiak’s launch plans show how competitive Texas is becoming.
The company announced in September that it aims to begin fully unsupervised long-haul service on Dallas-Houston by year-end.
That puts it directly against Aurora in one of the most commercially attractive autonomous-trucking corridors in America.
Competition could benefit customers by lowering costs.
But it could also pressure Aurora’s future pricing.
AURORA HAS THE ADVANTAGE OF ALREADY OPERATING COMMERCIALLY
Aurora’s strongest argument is that it is already running driverless commercial freight.
That makes it more than a development-stage technology company.
It has:
Real trucks
Real customers
Real freight
and
Real driverless miles.
The next challenge is scaling from a technically successful deployment into a profitable industrial business.
That transition is often much harder than proving the technology works.
ANALYSTS HAVE RAISED THEIR TARGETS
Aurora’s recent Investor Day prompted several analysts to become more optimistic.
Canaccord Genuity raised its price target to:
$17.
Morgan Stanley raised its target to:
$18.
Cantor Fitzgerald maintained a:
$12 target.
Those targets reflected optimism around:
30,000-truck scale
DaaS economics
and
Aurora’s early commercial lead.
But analyst targets are opinions, not guarantees.
Different analysts continue to disagree sharply about how much the business is worth today.
THE STOCK’S VALUATION STILL ASSUMES A LOT OF SUCCESS
At recent prices, Aurora has carried a market value of more than:
$10 billion
despite current quarterly revenue measured in only a few million dollars.
Traditional valuation metrics such as:
Price-to-sales
therefore look extreme.
But investors are not valuing Aurora on today’s revenue.
They are valuing the probability that it eventually becomes a:
multi-billion-dollar autonomous-driving platform.
That makes the stock highly sensitive to changes in expectations.
ONE DELAY COULD HAVE AN OUTSIZED EFFECT
If Aurora misses:
Truck deployment targets
Customer contracts
or
Safety milestones,
the market can quickly recalculate how long commercialization will take.
Every extra year matters because the company continues burning cash.
A delay does not simply push revenue into the future.
It can also require additional financing.
That is why execution risk is so important.
THE UPSIDE CASE IS ENORMOUS
If Aurora reaches:
30,000 trucks
and
more than $5 billion in annual revenue
with gross margins around:
60%,
the company would look radically different from today.
A software-like business generating billions of dollars from autonomous trucking could justify a significantly larger valuation.
That is the logic behind bullish arguments that the stock could potentially:
double
or more.
But investors are effectively betting today on financial results that may not arrive until several years in the future.
THE DOWNSIDE CASE IS JUST AS REAL
The bear case is straightforward.
Autonomous deployment could scale more slowly than expected.
Customers could resist pricing.
Competitors could gain ground.
Regulators could impose new restrictions.
A serious accident could slow deployment.
Truck manufacturers could delay production.
And Aurora could burn through substantial cash before reaching profitability.
In that scenario, shareholders could face:
Further dilution
and
A much lower valuation.
That is why Aurora remains a high-risk growth company rather than a mature trucking investment.
THE BIGGER STORY: AURORA HAS ALREADY SOLVED ONE OF THE HARDEST PROBLEMS — NOW IT HAS TO SOLVE THE BUSINESS
For years, the biggest question around autonomous trucking was:
Can an 80,000-pound truck safely haul freight on public highways without anyone sitting behind the wheel?
Aurora can now point to more than:
500,000 driverless commercial miles
and say it is already doing exactly that.
The next question may be harder.
Can the company turn that technology into a business with:
30,000 trucks
$5 billion-plus in revenue
and
60% gross margins
before its cash runs low?
Aurora plans to exit 2026 with 200 autonomous trucks.
Hirschbach wants 500 customer-owned vehicles beginning in 2027.
And the shift toward Driver as a Service could allow fleet operators—not Aurora—to finance the physical trucks.
If that model works, autonomous trucking could become a recurring software business layered on top of one of America’s largest industries.
But today Aurora is still generating only millions of dollars in revenue while losing hundreds of millions.
That is why the opportunity looks so dramatic.
And why the risk is impossible to ignore.
Aurora has already proved that a truck can move freight without a driver — but the next four years will decide whether driverless trucking can move Aurora itself from a cash-burning technology company into a multibillion-dollar transportation platform.