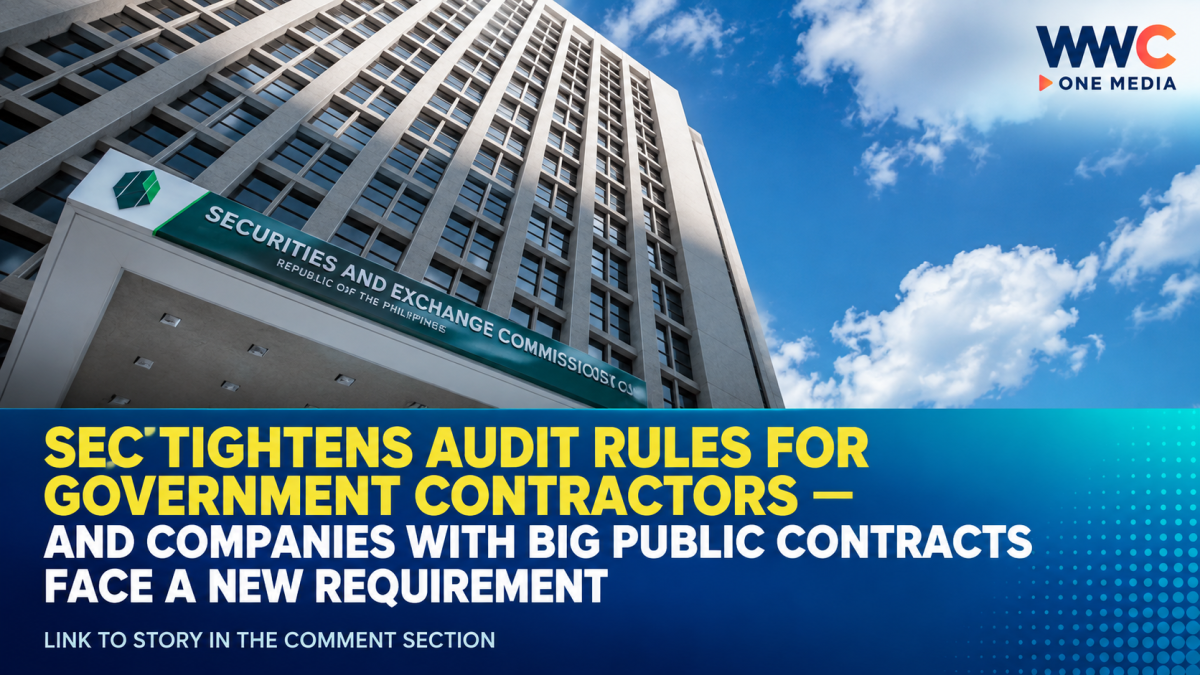
MANILA, Philippines — Companies handling large government contracts are facing tighter financial scrutiny as the Securities and Exchange Commission (SEC) strengthens its accreditation rules for external auditors.
Under SEC Memorandum Circular No. 26, Series of 2026, the corporate regulator has tightened audit requirements for government contractors while raising the qualification and experience standards for auditing firms. The move comes as scrutiny of public infrastructure spending intensifies following investigations into alleged irregularities involving government projects.
The new framework places particular attention on companies awarded major government contracts. A corporation that receives a single government contract worth at least ₱100 million, or government contracts with a combined value of at least ₱150 million within a reporting year, is required to engage an SEC-accredited external auditor under Group A.
The accredited auditor must remain engaged until the covered projects have been completed or delivered.
Companies covered by the requirement must also submit a notarized schedule of their government projects, including details such as the project description, government agency involved, contract cost and project status. The disclosures must be covered by an auditor’s report, creating an additional layer of independent financial documentation.
Higher standards for auditors
The SEC is also raising the experience requirements for auditing firms seeking accreditation.
For Group A accreditation, firms will need at least five corporate clients with assets of at least ₱100 million each, compared with the previous requirement involving clients with assets of at least ₱50 million.
For Group B, the requirement rises to five corporate clients with assets of at least ₱50 million each, from three clients with assets of at least ₱20 million.
For Group C, applicants must have at least five corporate clients with assets of at least ₱5 million each, compared with the previous requirement of three clients.
The SEC classifies auditors according to the types and sizes of entities they are qualified to audit. Group A covers entities including listed companies, issuers of registered securities and other major regulated market participants. Group B covers institutions such as investment houses, securities brokers and dealers, while Group C includes certain financing and lending companies and transfer agents.
Tougher grounds for accreditation denial
The new rules also expand the circumstances under which an auditor’s accreditation application can be denied.
These include misrepresenting or concealing information during the accreditation process, issuing an unqualified audit opinion despite material misstatements involving an inappropriate accounting framework, having six or more material findings in a single set of financial statements, and failing to maintain auditor independence.
The independence provision is particularly significant because auditors must not take on responsibilities that compromise their ability to provide an objective assessment of a client’s financial statements. The rules specifically address situations in which an auditor directly prepared the financial statements being audited.
The framework also limits how often an auditor can receive conditional accreditation. Under the reported rules, an applicant can receive conditional accreditation no more than three times throughout its history, whether the instances are consecutive or not.
Why the change matters
The strengthened requirements give the SEC a greater role in monitoring the financial reporting of companies handling substantial government contracts.
The regulator has said the changes are intended to strengthen the accreditation framework, improve the quality of audit work and protect the public interest by expanding oversight of government contractors and raising the standards for auditors.
The timing also comes amid heightened scrutiny of government infrastructure projects following the Philippines’ flood-control controversy. However, the SEC’s stated regulatory objectives concern broader audit quality and oversight; the SEC did not explicitly identify the controversy as the sole basis for the changes.
The SEC’s broader accreditation framework has long required accredited external auditors for certain regulated entities. In April 2025, the Supreme Court also upheld the SEC’s authority to require companies issuing registered securities to use SEC-accredited CPAs for independent audits, reinforcing the regulator’s accreditation framework.
For government contractors, the practical effect is clear: companies handling sufficiently large public contracts now face stronger independent-audit and documentation requirements, while auditors themselves face higher qualification and accountability standards.
The changes put greater emphasis on creating an independent financial trail around major government-funded projects—one that can be examined not only by the companies and government agencies involved, but also through the regulatory audit framework.