
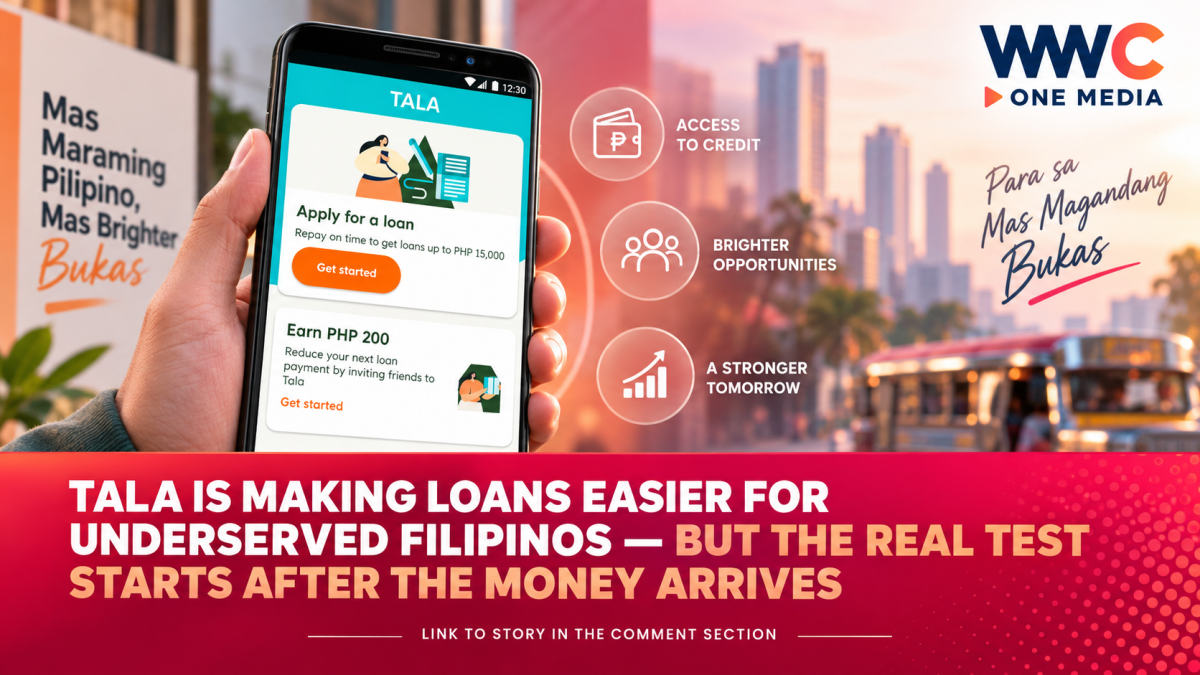
MANILA, Philippines — Getting a loan through a smartphone has never been easier for many Filipinos. But Tala says the bigger test for digital lending begins after the money arrives.
The financial technology company is stepping up its push for what it calls responsible credit, arguing that financial inclusion should not simply be measured by how many previously underserved consumers can borrow.
Instead, Tala Philippines President and General Manager Moritz Gastl says borrowers should receive clear information, flexible repayment options and fair treatment throughout the entire credit cycle — including when they struggle to pay.
The position comes as digital lending expands rapidly in a Philippine market where millions of people remain outside traditional bank credit systems, particularly workers, small merchants and entrepreneurs without collateral or long credit histories.
And the numbers show why lenders see a huge opportunity.
Only 16% of Filipino adults borrowed from formal sources
The Bangko Sentral ng Pilipinas’ 2025 Consumer Finance and Inclusion Survey found that just 25% of Filipino adults had outstanding loans.
Only 16% of adults borrowed from formal sources, including microfinance organizations, government institutions, lending and financing companies and banks. Informal borrowing accounted for another 10%.
Perhaps more revealingly, seven in 10 adults said taking out a loan was generally not a good idea, illustrating how deeply caution — and in some cases distrust — remains embedded in Filipino attitudes toward debt.
Yet that attitude is changing.
TransUnion’s 2026 Credit Perception Index climbed to 75 out of 100, the highest since the study began in 2023. Its survey of 1,000 consumers found improving trust and knowledge of credit products despite continuing pressure from inflation and living costs.
Transparency was cited by 56% of respondents as a major factor influencing trust, followed by fair or low interest rates at 53% and strong security and fraud protection at 52%.
That is precisely the battleground Tala is targeting.
Tala says borrowers need more than fast approval
Tala’s message is relatively simple: making credit accessible within minutes means little if borrowers encounter unclear fees, aggressive collection tactics or repayment structures that do not reflect their circumstances.
The company has been promoting its “Debt with Dignity” initiative, which calls for more respectful treatment of borrowers, particularly when financial difficulties interfere with repayment.
Gastl said most borrowers want to repay what they owe and argued that lenders should provide appropriate tools and flexibility rather than treating financial hardship automatically as unwillingness to pay.
Tala has also advocated for stronger oversight of debt collection, including accreditation of collection agencies and clearer disclosure of financial products.
The issue is significant because abusive collection practices have been one of the biggest reputational problems facing parts of the online lending sector.
The Securities and Exchange Commission has rules prohibiting unfair debt collection practices, while its broader consumer-protection framework requires lenders to comply with disclosure and fair-conduct standards.
But responsible lending is also about how much credit costs
There is another side to the responsible-credit discussion: the price borrowers ultimately pay.
According to Tala’s currently published Philippine loan terms, its regular loans carry a processing fee ranging from 3.99% to 9.99% of principal and a daily service fee ranging from 0.21% to 0.43%, depending on the borrower and loan.
Regular loans can generally be repaid over 15 to 61 days. Tala says the specific charges are personalized and comply with SEC regulations.
That makes disclosure critical because short-term digital loans can appear manageable when expressed as a daily charge even though the total repayment cost may become considerably larger over several weeks.
Philippine regulators have tightened rules for smaller short-term loans.
Beginning April 1, 2026, SEC Memorandum Circular No. 14 applies to unsecured, general-purpose loans of ₱10,000 or less with terms of up to four months.
For covered loans, the effective interest rate — which incorporates interest and most applicable fees — is capped at 12% per month, down from the previous 15% ceiling. Late-payment penalties are subject to separate limits.
Those rules provide an important counterweight to the rapid growth of lending apps: access may be digital, but consumer protection still depends on borrowers knowing the full peso cost before accepting a loan.
Tala is betting alternative data can find borrowers banks overlook
One of Tala’s biggest advantages — and one of the biggest changes occurring across fintech — is the use of information beyond traditional credit histories.
Many nano and microentrepreneurs have regular cash flow but lack the collateral, payslips or lengthy borrowing history that banks traditionally use when evaluating credit.
According to Tala, around 27% of its customers are nanoentrepreneurs, including sari-sari store operators who may borrow to replenish inventories.
Instead of relying solely on conventional credit files, Tala says it combines behavioral information, external information, telecommunications data and proprietary risk models to assess borrowers.
The company says it has generated underwriting records involving more than 50 million applicants globally, providing data it can use to evaluate people who might otherwise have thin or nonexistent conventional credit files.
Its Tala InSight platform is designed to turn that data into real-time credit decisions and more personalized loan offers.
Gastl has argued that traditional cash-flow and repayment data remain important but can become more useful when combined with behavioral, device and telecommunications information.
Small businesses are becoming central to Tala’s Philippine strategy
That approach matters particularly for small entrepreneurs.
At the Money20/20 Asia conference earlier this year, Tala said roughly a quarter of its Philippine customers use borrowed funds for business purposes.
The company said nine out of 10 customers who borrowed for business reported an improved business outlook, including greater stability, confidence or expansion. That statistic is based on Tala’s customer research and should therefore be understood as a company-reported outcome rather than an independently measured national result.
Tala’s focus on entrepreneurs also reflects the way small businesses operate in the Philippines.
A sari-sari store owner may not need hundreds of thousands of pesos or a traditional multi-year business loan. What may matter more is immediate access to a smaller amount of working capital to restock goods before a weekend, meet a supplier payment or respond to a sudden increase in demand.
That speed is precisely where digital lenders compete with banks, cooperatives, informal lenders and even borrowing from relatives.
Tala wants nearly another million customers
The commercial opportunity is substantial.
In March, Gastl told GMA Integrated News that Tala Philippines had around 3.5 million to 3.6 million customers and was targeting approximately 4.5 million to 5 million by the end of 2026.
The company was also aiming for 30% to 40% growth in its loan book this year, citing continued demand from consumers who lack collateral or immediate access to bank financing.
Tala separately reported substantial cumulative lending activity in the country, saying it had processed tens of millions of loans since entering the Philippine market. BusinessWorld reported company figures of ₱137 billion across around 28 million loans in early 2026.
The scale shows why the debate about responsible digital credit is no longer a niche fintech issue.
Millions of borrowers can now potentially receive a credit decision without entering a bank branch.
Regulators are reopening the digital-lending market — with tougher safeguards
The industry’s next phase could become even more competitive.
The SEC lifted its nearly five-year moratorium on new online lending platforms effective August 1, 2026, reopening the sector to new entrants under strengthened prudential, disclosure and consumer-protection requirements.
The regulator said the change was intended to encourage responsible innovation and financial inclusion while protecting borrowers and preserving market integrity.
That creates both an opportunity and a test.
More lenders could mean greater competition, better products and wider access.
But it could also expose more Filipinos to poorly designed credit if transparency, affordability and collection standards fail to keep pace.
The real financial-inclusion test comes after approval
Digital lenders have already solved part of the problem that once kept millions of Filipinos away from formal credit: speed and physical access.
A smartphone can now replace the branch visit, piles of paperwork and days of waiting associated with conventional loan applications.
The harder challenge is deciding what happens next.
Does the borrower understand exactly what the loan will cost?
Can an entrepreneur borrow enough to increase income rather than merely roll over debt?
Does a missed payment trigger reasonable assistance or escalating pressure?
And can alternative-data systems widen opportunity without exposing consumers to inappropriate levels of borrowing?
That is where Tala’s push for responsible credit will ultimately be judged.
Because for underserved Filipinos, a loan approved in minutes is only financial inclusion if it improves their options after the money is spent.
Leave a Reply