MANILA, PHILIPPINES — November 11, 2026 — One of the Philippines’ biggest financial services networks is joining forces with an international leadership organization in a move that could bring new opportunities to Filipino entrepreneurs, underserved communities and households seeking better access to financial services.
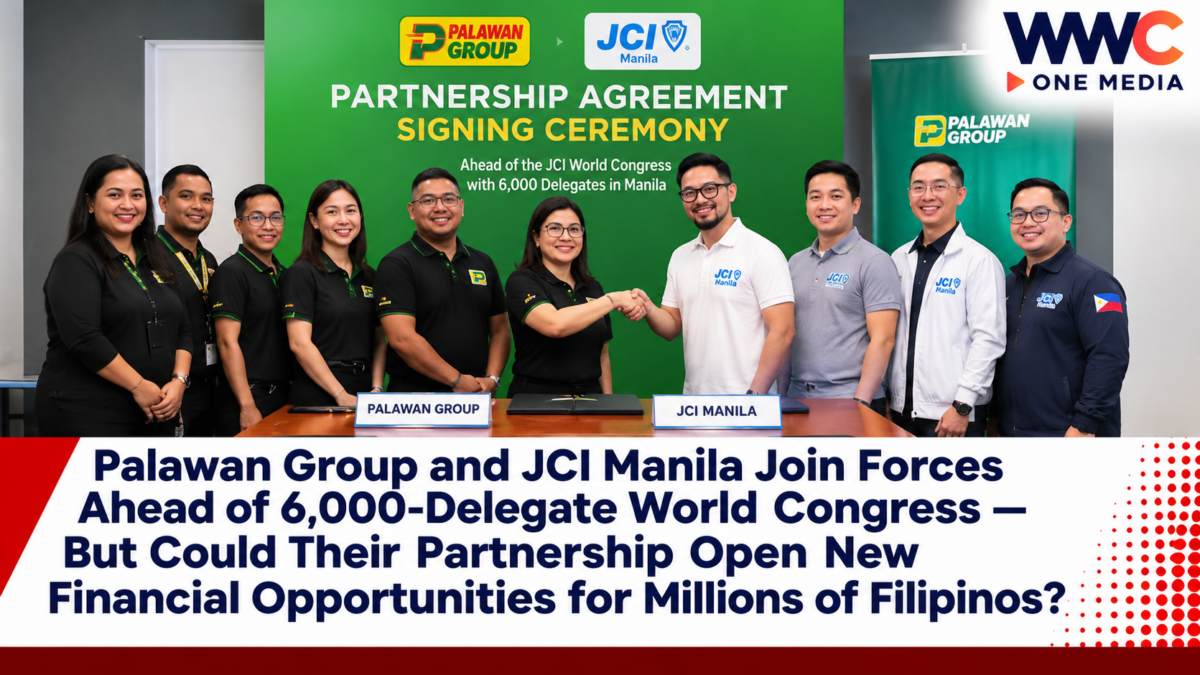
The Palawan Group of Companies has formally signed a Memorandum of Agreement (MOA) with JCI Manila, strengthening cooperation in financial inclusion, entrepreneurship, leadership development and community empowerment.
The agreement comes as the Philippines prepares to welcome more than 6,000 delegates from over 120 countries and territories to the JCI World Congress 2026, scheduled for November 11–15 at the Clark Expo & Convention Center in Pampanga.
For Palawan Group, the partnership creates an opportunity to connect its extensive financial services network with JCI Manila’s community of entrepreneurs, young professionals and civic leaders.
The company says its PalawanPay digital wallet now has 23 million users, while its nationwide network includes more than 70,000 branches, Pera Padala outlets and PalawanPay Money Shops.
But the partnership is about more than expanding a customer base.
Both organizations are exploring how financial access, entrepreneurship and leadership initiatives can contribute to stronger local economies.
The biggest question is whether the new alliance can transform international networking and corporate commitments into measurable financial opportunities for Filipinos who remain underserved by traditional banking institutions.
Palawan Group and JCI Manila Formalize Major Partnership
The agreement brings together two organizations with different but potentially complementary strengths.
Palawan Group operates an extensive network of financial service outlets supported by digital platforms.
JCI Manila, meanwhile, is part of Junior Chamber International, a global leadership organization that encourages entrepreneurship, professional development and community service.
Their partnership is intended to explore programs that combine practical financial services with community-based economic opportunities.
The areas identified include financial inclusion, entrepreneurship, leadership development and community empowerment.
The agreement also provides opportunities for collaboration during and beyond the JCI World Congress.
However, the organizations have not publicly disclosed a specific financial commitment, number of beneficiaries or detailed implementation calendar for the new initiatives.
The MOA establishes a framework for cooperation rather than proof that every proposed program has already begun.
For the partnership to deliver lasting benefits, both organizations will need to convert broad commitments into concrete projects that can be evaluated over time.
JCI World Congress 2026 Brings Global Attention to Clark
The timing of the agreement is significant.
The Philippines is hosting the JCI World Congress 2026 from November 11 to 15 at the Clark Expo & Convention Center inside Clark Freeport Zone, Pampanga.
Organizers expect more than 6,000 delegates representing over 120 countries and territories.
The international event will bring together young leaders, business owners, professionals and community advocates to exchange ideas and build relationships.
For the Philippines, the gathering presents opportunities to showcase domestic businesses, entrepreneurship initiatives and community-development programs.
It could also help local organizations establish partnerships with international counterparts.
For Palawan Group, participating in the congress creates a platform to introduce its financial services approach to a global audience.
But a successful international event should not be measured solely by the number of delegates or business connections created.
The more important question is whether those relationships eventually produce practical programs, investment opportunities or support for communities.
Palawan Group Wants Financial Services to Reach More Filipinos
The Palawan Group has grown from its traditional pawnshop and remittance businesses into a wider financial services organization.
Its portfolio includes Palawan Pawnshop, Palawan Express Pera Padala, PalawanPay, Palawan ProtekTODO, Palawan Credit, Palawan Gold and business-oriented financial services.
These products address different financial needs.
Remittance services allow people to send and receive money.
Pawnshop services provide collateral-based access to cash.
Digital wallets support electronic payments and transfers.
Microinsurance products offer specific forms of protection at relatively affordable prices.
For customers in underserved areas, access to nearby physical outlets can be particularly important.
Not everyone has reliable internet connectivity, a suitable smartphone or the confidence to conduct every transaction digitally.
Palawan Group’s strategy combines face-to-face financial services with digital technology.
The company refers to this approach as its bricktech model.
Rather than eliminating physical service locations, the model seeks to make them work alongside online platforms.
PalawanPay’s 23 Million Users Highlight the Scale of Its Digital Ambitions
PalawanPay has become an important part of the group’s broader growth strategy.
According to the company’s November partnership materials, the platform has reached 23 million users.
The figure illustrates the scale of its claimed customer adoption, although it should not be treated as a verified count of monthly active users.
PalawanPay supports services such as money transfers, bill payments, mobile load purchases, eligible pawn renewals and QR Ph transactions.
The platform gives users alternatives to visiting a physical outlet for some everyday financial activities.
For small businesses, digital payments can also make it easier to receive money from customers.
However, using a digital wallet does not automatically guarantee access to affordable loans, savings products or insurance.
Financial inclusion involves more than registering an account.
People also need suitable products, transparent fees, reliable services and the knowledge to manage financial risks.
This is where the JCI Manila partnership could become more valuable if it leads to practical community training and support.
Why Financial Inclusion Remains a Major Philippine Challenge
Despite rapid growth in digital payments and financial technology, millions of Filipino adults remain outside the formal financial system.
According to a Social Weather Stations survey cited by the Bangko Sentral ng Pilipinas in May 2026, approximately 58% of Filipino adults reported owning a formal financial account during the first quarter.
That represented an improvement from the 51% measured by the BSP’s 2025 Consumer Finance and Inclusion Survey.
However, the figures came from different survey exercises and should be interpreted with their methodologies in mind.
The 2026 survey still suggested that approximately 42% of adults did not own a formal financial account.
Common barriers include limited income, unemployment, lack of familiarity with account-opening requirements and difficulty accessing suitable financial services.
The challenge is especially important for households that depend heavily on cash transactions.
Without accessible formal services, people may have fewer options for saving money securely, making payments or obtaining appropriate credit.
Financial education can help individuals evaluate their options.
But education alone cannot eliminate poverty or create income where none exists.
Meaningful inclusion requires affordable, accessible services that people can actually use.
Palawan’s Physical Network Could Help Bridge the Digital Divide
Palawan Group says it operates more than 70,000 combined branches, remittance outlets and PalawanPay Money Shops nationwide.
The network gives the company a substantial physical presence across the Philippines.
That is potentially valuable because consumers outside major urban centers may encounter practical barriers when dealing with conventional banks.
Some communities have limited bank-branch availability.
Others face transportation costs or internet-connectivity difficulties.
A hybrid service model allows customers to choose between digital transactions and physical outlets, depending on their circumstances.
For example, a customer who receives money through a digital wallet might still prefer a nearby shop to convert part of the balance into cash.
A microentrepreneur may use digital payments but require in-person help with a specific transaction.
This combination could support wider participation in formal financial services.
However, the number of service locations alone does not establish how many previously unserved customers have gained meaningful financial access.
That would require additional measurements of account use, transaction affordability and customer outcomes.
Small Businesses Could Benefit From Greater Financial Access
One of the partnership’s stated objectives is entrepreneurship.
For Filipino micro, small and medium enterprises, managing everyday financial transactions can be a significant operational challenge.
Small businesses need ways to receive customer payments, pay suppliers, transfer funds and manage cash flow.
Some also require access to suitable credit for inventory, equipment or business expansion.
But traditional lending institutions may require financial records, collateral or credit histories that newer entrepreneurs struggle to provide.
Digital financial services and alternative distribution networks can help address some of these barriers.
However, responsible lending remains essential.
Making loans easier to obtain does not necessarily make them affordable or appropriate.
Borrowers must understand interest rates, fees, repayment schedules and penalties before accepting financing.
In related reporting, WWC ONE MEDIA examined Tala’s expansion of banking and financial-technology partnerships to widen access to formal credit for underserved Filipino borrowers.
That initiative reflects the same broader financial-inclusion challenge: extending access without exposing financially vulnerable customers to unaffordable debt.
For Palawan Group and JCI Manila, entrepreneurship-focused programs could eventually help business owners understand financial products and make more informed decisions.
But no specific new loan facility for JCI members has been announced under the latest agreement.
OFWs Were Already Part of an Earlier Palawan-JCI Partnership
The new MOA builds on an existing relationship between the two organizations.
In May 2026, Palawan Group participated in JCI Manila’s Leading OFWs Beyond program, a financial literacy initiative for overseas Filipino workers and their families.
The event was held at the Department of Migrant Workers office in Makati City.
It brought together more than 200 OFWs and family members from across Metro Manila.
Sessions covered managing remittances, recognizing financial scams, planning for future expenses and understanding selected financial products.
Palawan Group also discussed gold-related investments and microinsurance as part of its presentation.
The event reflected the importance of helping OFW households use remittance income effectively.
Remittances support millions of Filipino families, but their long-term financial benefits depend partly on how recipients allocate the money.
Households may need to balance food expenses, education, housing, savings and emergencies.
Financial education can help families consider those priorities more carefully.
However, investment products such as gold carry price risks, and insurance coverage depends on policy terms and exclusions.
No financial product should be treated as a guaranteed way to protect savings or build wealth.
OFW Remittances Are Becoming a Bigger Digital Finance Opportunity
The growing importance of remittances has encouraged banks and fintech companies to expand cross-border payment services.
In September, GoTyme Bank launched a promotional campaign involving international money transfers, demonstrating how digital banks are competing for customers who send or receive money from overseas.
As WWC ONE MEDIA reported in its analysis of GoTyme’s ₱5,000 qualifying remittance promotion and the multibillion-dollar OFW money market, financial institutions are increasingly competing to become the platform through which Filipino families manage their money.
The shift goes beyond the act of receiving remittances.
Financial companies want users to save, pay bills, transfer funds and access other services within their platforms.
For consumers, more competition could improve convenience and encourage innovation.
But the true cost of a remittance also depends on exchange rates, transfer fees and other charges.
For OFW families, financial literacy remains important even as services become faster and more digital.
The Palawan-JCI partnership could potentially help address this need through future educational activities.
JCI Manila’s Global Network Could Support Local Entrepreneurs
JCI Manila’s involvement gives the partnership a community-development dimension that extends beyond Palawan Group’s customer network.
The organization belongs to Junior Chamber International, which promotes leadership and civic engagement through local and international chapters.
The JCI World Congress provides opportunities for members to meet entrepreneurs and professionals from different countries.
These connections may help participants exchange business ideas and identify approaches relevant to their communities.
For Philippine entrepreneurs, international networking can be useful when exploring new markets, learning management practices or developing partnerships.
However, networking events do not automatically generate financing or new businesses.
The value depends on what participants do after the event.
Palawan Group chief operating officer Bobbit M. Castro emphasized this point by encouraging participants to turn relationships created through the congress into initiatives that continue benefiting communities.
JCI World Congress director Luis Angelo Sevilla similarly highlighted the importance of converting collaboration into meaningful action.
The partnership could therefore serve as a bridge between corporate financial services and community-driven entrepreneurship.
Its success will depend on whether both organizations establish clear activities and measure the results.
Financial Literacy Programs Are Expanding Across the Philippines
Palawan Group is not the only financial institution investing in community education.
Banks, foundations and technology companies have been expanding programs that teach Filipinos how to manage money and assess financial products.
In a separate report, WWC ONE MEDIA examined BPI Foundation’s partnership with Far Eastern University, which expanded its financial literacy activities as reported outreach reached 55,000 Filipinos.
That initiative illustrates the growing role of partnerships between businesses and educational institutions.
Financial literacy can include budgeting, understanding credit, avoiding scams and developing saving habits.
But attendance figures are not sufficient to establish long-term impact.
A successful program should eventually demonstrate whether participants are making better-informed financial decisions.
For the Palawan-JCI partnership, similar measures could help show whether the cooperation is producing practical benefits rather than only public commitments.
Government Digital Payments Show Why Access Matters
Financial inclusion is also becoming a major part of Philippine government service delivery.
Some public assistance programs are using digital wallets to distribute financial support directly to eligible beneficiaries.
The objective is to reduce travel, waiting times and logistical expenses for households receiving aid.
As WWC ONE MEDIA reported on the Department of Social Welfare and Development’s partnership with GCash for digital UPLIFT payments, digital distribution can make financial assistance easier to access for eligible recipients.
But these systems also face challenges involving account verification, connectivity, digital literacy and fraud prevention.
A beneficiary without a smartphone or reliable internet connection may still require alternative access methods.
This illustrates the potential relevance of hybrid financial service networks such as Palawan Group’s.
Digital technology can improve efficiency, while physical locations can help serve customers who are unable or unwilling to complete every transaction online.
For the Philippines, combining those channels may be important in preventing digital transformation from leaving disadvantaged communities behind.
Cybersecurity and Consumer Protection Must Remain Priorities
Expanding financial access also creates responsibilities.
People using digital wallets and other financial platforms may encounter phishing messages, fraudulent transactions or misleading investment offers.
Small-business owners can be particularly vulnerable when they are unfamiliar with financial technology or borrowing requirements.
Community-based financial education should therefore include consumer protection.
Useful subjects could include recognizing fraudulent links, protecting account credentials, checking fees and evaluating financial offers.
Consumers should avoid sharing PINs, passwords or one-time authentication codes with anyone claiming to represent a financial institution.
Insurance products should also be reviewed carefully to understand coverage, exclusions and claim requirements.
For financial service providers, trust is essential.
A large network and high user-registration figures cannot substitute for reliable transactions, clear disclosures and accessible customer support.
The long-term value of the Palawan-JCI collaboration will depend partly on whether future programs help people manage these risks.
What Happens After the JCI World Congress?
The first major opportunity for expanded engagement will come during the November 11–15 congress in Clark.
Palawan Group and JCI Manila will be able to connect with entrepreneurs, civic leaders and other participants from the Philippines and overseas.
After the event, the organizations will need to determine which initiatives to pursue.
Several practical questions remain unanswered.
Will they establish recurring financial literacy programs in underserved communities?
Could they develop entrepreneurship workshops or mentoring opportunities for small-business owners?
Will the partnership create specific support arrangements for OFWs and their families?
And will future activities have measurable targets for participation and financial outcomes?
None of those programs has been confirmed in sufficient detail under the latest MOA.
They represent possible directions consistent with the announced partnership objectives.
For readers and potential participants, formal announcements from Palawan Group and JCI Manila will be the best way to establish actual opportunities, eligibility and schedules.
The Bigger Picture: Financial Inclusion Must Deliver More Than Access
The partnership between Palawan Group and JCI Manila brings together a major Philippine financial services network and an international leadership organization at a moment when digital finance is becoming central to everyday economic activity.
Palawan Group brings physical outlets, remittance services, digital payments, microinsurance and other financial products.
JCI Manila brings a network of young leaders, entrepreneurs and community advocates.
The JCI World Congress creates a platform for both organizations to explore opportunities with international participants.
But the challenges facing financially underserved Filipinos remain substantial.
Millions of adults still lack formal financial accounts.
Small enterprises continue encountering barriers to affordable financing.
OFW families must manage remittances carefully while protecting themselves from scams and financial shocks.
For financial inclusion to become meaningful, households and entrepreneurs need more than access to services.
They need transparent costs, reliable transactions, appropriate products and practical knowledge.
The Palawan-JCI alliance has the potential to support those objectives.
Yet a signed agreement is only the beginning.
Palawan Group has built a financial services network reaching communities across the Philippines, while JCI Manila is bringing together thousands of international leaders at Clark. But can their new partnership convert that enormous reach into real financial opportunities for underserved Filipinos—or will the promise of greater inclusion remain another corporate commitment waiting to be fulfilled?