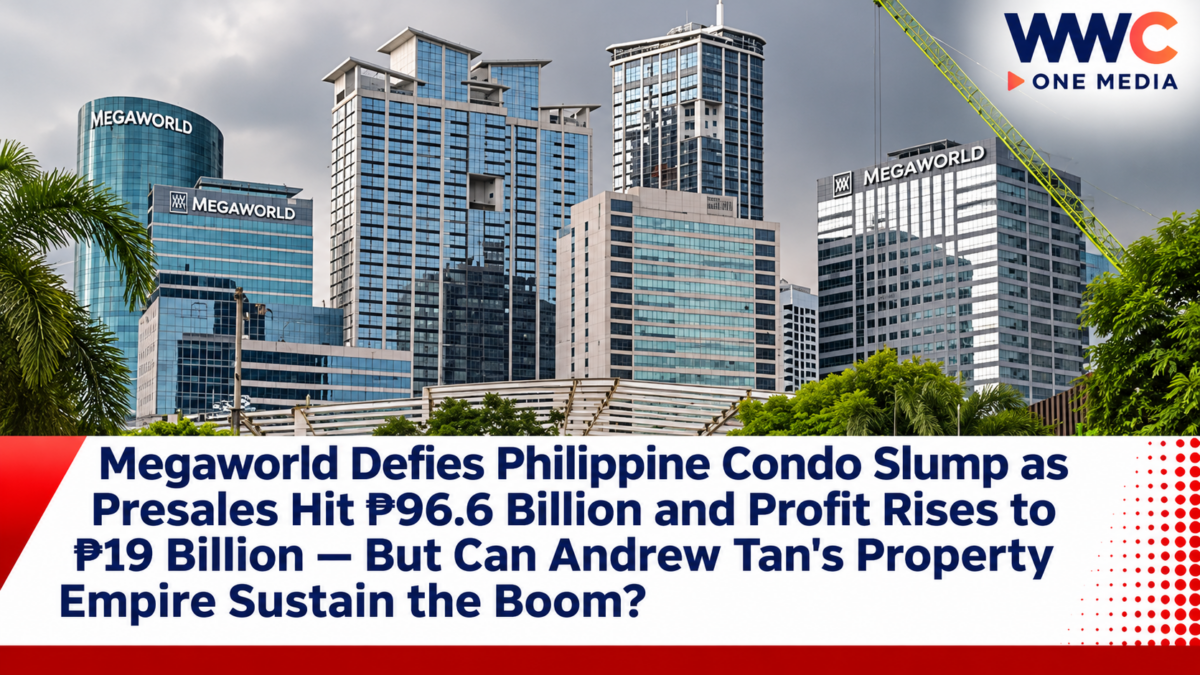
MANILA, PHILIPPINES — November 10, 2026 — While thousands of condominium units remain unsold across Metro Manila and major property developers struggle with weaker homebuyer demand, Andrew Tan’s Megaworld Corporation is delivering a surprisingly strong performance.
The township developer reported ₱96.6 billion in residential presales during the first nine months of 2026, an increase of 9% from the same period last year.
The figure represents more than 77% of Megaworld’s ₱125-billion full-year presales target, placing the company within striking distance of its annual goal despite continued uncertainty in the Philippine property market.
The company also reported consolidated net income of ₱19 billion, up 6% year over year, while consolidated revenue increased 3% to ₱66.5 billion.
But Megaworld’s success goes beyond residential property.
Its hotels, shopping malls and office developments all recorded higher revenue, demonstrating how the company’s integrated township model can generate income from several property segments.
Nearly half of its residential presales came from provincial developments, signaling that demand outside Metro Manila remains an important driver of growth.
However, the latest financial results also reveal risks.
Operating cash flow declined 28%, cash balances fell, and borrowing-related expenses increased.
As Megaworld defies a difficult housing market, investors now face a critical question: Can strong provincial demand and expanding rental businesses support another year of growth—or could financing costs and weaker cash generation eventually catch up with the property giant?
Megaworld Presales Climb 9% to ₱96.6 Billion
Megaworld’s residential presales reached ₱96.6 billion between January and September 2026.
That represents an increase of approximately 9% from the corresponding period last year.
Presales measure customer commitments to purchase properties, including residential units that have not yet been completed.
They are an important indicator of future demand.
However, they are not equivalent to recognized revenue or cash already collected.
Actual revenue recognition depends on accounting requirements, project progress and other conditions.
During the same nine-month period, Megaworld recognized approximately ₱40.6 billion in real estate sales revenue.
That figure was broadly unchanged from the previous year.
The distinction matters because a developer can record strong new reservations while revenue from those commitments is recognized over subsequent reporting periods.
For investors, the next challenge is ensuring that reservations translate into completed sales, collections and sustainable earnings.
Megaworld Already Achieves More Than 77% of Its Annual Target
The company has set a ₱125-billion residential presales target for 2026.
By the end of September, it had achieved approximately 77.3% of that goal.
That leaves roughly ₱28.4 billion in additional presales required during the final quarter to meet the full-year target.
The performance suggests continued demand for Megaworld’s township developments.
But reaching 77% of a target after nine months does not guarantee the remaining amount will be achieved.
Fourth-quarter demand can be influenced by financing costs, buyer confidence, product launches and the availability of attractive properties.
Megaworld must therefore maintain its sales momentum during the final months of the year.
Provincial Buyers Drive Nearly Half of Residential Demand
One of the most important findings in Megaworld’s announcement concerns the geographic distribution of its property sales.
Nearly half of residential presales originated from provincial developments.
That suggests buyers continue showing interest in projects outside the National Capital Region.
Megaworld has expanded its township portfolio across major growth areas, creating developments combining residences, commercial spaces and lifestyle facilities.
The strategy allows the company to serve buyers seeking homes near employment centers, retail destinations and other amenities.
Provincial expansion may also help reduce dependence on Metro Manila’s more competitive condominium market.
However, the company has not disclosed a complete project-by-project breakdown of the ₱96.6-billion presales figure in the reporting reviewed.
It would therefore be inaccurate to attribute a precise amount of sales to individual provincial developments without additional disclosures.
Why Megaworld Is Outperforming a Difficult Housing Market
The Philippines’ residential property industry has been under pressure from affordability concerns and cautious buyer sentiment.
Elevated living expenses can reduce the amount households are willing to commit to property purchases.
Financing costs can also affect mortgage affordability.
Some buyers delay purchases because of uncertainty about future income or property prices.
Megaworld has responded through its integrated township strategy and targeted sales initiatives.
During the October National Housing Expo, the developer offered selected condominium buyers promotional benefits, including unit upgrades and access to Pag-IBIG financing arrangements.
As previously reported by WWC ONE MEDIA, some offers highlighted housing loans of up to ₱10 million for eligible borrowers.
Related WWC ONE MEDIA coverage: Megaworld Offers Free Condo Upgrades and Pag-IBIG Loans Up to ₱10 Million — But a Bigger Housing Affordability Challenge Remains
The promotional program demonstrates how developers are adapting to buyers’ financial concerns.
However, the company has not established how much of its reported nine-month presales growth was directly caused by those particular offers.
Metro Manila’s Condominium Slowdown Provides a Stark Contrast
Megaworld’s growth becomes more significant when compared with conditions in the wider residential market.
A recent analysis of Metro Manila condominium inventory highlighted substantial unsold supply and growing buyer cancellations.
As previously reported by WWC ONE MEDIA, approximately 82,900 unsold condominium units were identified in a market assessment, alongside about 9,000 canceled purchases.
Related WWC ONE MEDIA coverage: 9,000 Metro Manila Condo Purchases Cancelled as Unsold Inventory Hits 82,900 Units — But Is the Philippines Facing a Bigger Property Crisis?
Those industry-wide figures are not Megaworld’s own unsold inventory or canceled purchases.
They provide background on the difficult environment facing residential developers.
Megaworld’s stronger presales suggest that its project locations, buyer mix and township offerings may be helping it compete.
However, the data alone cannot establish which specific factors explain the difference in performance.
Consolidated Profit Increases 6% to ₱19 Billion
Megaworld’s financial performance also remained positive.
Consolidated net income reached approximately ₱19.01 billion during the first nine months of 2026.
That represents a 6% increase from around ₱17.93 billion a year earlier.
Revenue rose approximately 3% to ₱66.53 billion.
But another important figure deserves attention.
Net income attributable specifically to Megaworld’s parent-company shareholders reached approximately ₱16.26 billion, increasing 2.1% year over year.
The difference reflects the allocation of consolidated profits between the parent company’s shareholders and noncontrolling interests.
Investors should not confuse total group earnings with income attributable to ordinary shareholders of Megaworld Corporation.
Both measures are important, but they answer different questions.
Hotels Become Megaworld’s Fastest-Growing Recurring Business
Megaworld’s hotel operations delivered the strongest growth among its major recurring-income segments.
Hotel revenue increased approximately 12% to ₱4.6 billion.
The company attributed the improvement to stronger bookings, higher room rates and contributions from newer properties.
Tourism, corporate travel and major events can support demand for hotels located within integrated townships.
These properties can also benefit surrounding restaurants, shopping centers and entertainment venues.
Megaworld has been expanding its hospitality portfolio, with plans to increase its room capacity over the coming years.
However, hotels remain sensitive to changes in occupancy, operating expenses and travel demand.
Higher revenue does not necessarily guarantee an identical increase in hotel profitability.
Shopping Mall Revenue Rises 9%
Megaworld’s mall rental business also grew.
Revenue increased approximately 9% to ₱5.5 billion during the nine-month period.
The company’s shopping mall portfolio reported occupancy of about 95%.
Average daily tenant sales increased approximately 10%.
Megaworld also reported nearly 36,000 square meters of new mall store openings during the period.
These indicators suggest sustained tenant activity and continued demand for retail space.
They also help explain why the company is maintaining its commercial property expansion plans.
As previously reported by WWC ONE MEDIA, Megaworld has appointed former Ortigas Land executive Javier Hernandez to lead Megaworld Lifestyle Malls.
Related WWC ONE MEDIA coverage: Megaworld Taps Former Ortigas Land Executive to Lead 27 Malls as ₱3.6-Billion Rental Business Surges — But Can He Deliver a Massive 2030 Expansion?
The company is targeting approximately one million square meters of retail gross leasable area by 2030.
That is a future expansion goal, not existing completed capacity.
Office Leasing Continues Growing Despite Market Uncertainty
Megaworld’s office business also posted higher revenue.
Office rental income increased approximately 7% to ₱11.9 billion during the first nine months.
Demand was supported partly by multinational companies expanding specialized corporate operations in the Philippines.
Global Capability Centers, or GCCs, are important tenants in this segment.
These facilities provide corporate services such as finance, technology, research, analytics and business operations.
Megaworld also reported that approximately 90% of office leases scheduled to expire in 2026 had been renewed as of September.
That figure is encouraging because lease renewals can support future rental-income visibility.
However, renewals do not guarantee that all office space is occupied or that future rental income will grow at the same rate.
The company must continue attracting tenants while managing new supply and changing corporate workspace requirements.
Megaworld’s Township Model Provides an Important Advantage
Megaworld’s business strategy differs from that of developers focused primarily on residential condominium sales.
Its integrated townships combine homes, offices, malls, hotels and other facilities in planned communities.
The approach can create multiple sources of revenue within a single development.
Residential buyers may be attracted by proximity to jobs, shopping and leisure facilities.
Office tenants may benefit from nearby services and housing.
Hotels and malls can generate recurring income from visitors and residents.
That mix can help reduce dependence on a single property segment.
As previously reported by WWC ONE MEDIA, Megaworld has emphasized its ability to balance residential growth with recurring rental businesses while maintaining corporate governance standards.
Related WWC ONE MEDIA coverage: Megaworld Wins Four Golden Arrows as ₱12.7-Billion Profit Drives Expansion — But Can Its Governance Keep Up With Rapid Growth?
The diversified model can provide resilience.
But it does not eliminate exposure to weak property demand, construction costs or changing economic conditions.
Cash Flow Declines Despite Higher Profits
One of the most important details in Megaworld’s financial disclosures concerns operating cash flow.
Net cash generated from operating activities declined to approximately ₱13.24 billion, compared with ₱18.39 billion during the first nine months of 2025.
That represents a decline of about 28%.
Meanwhile, cash and cash equivalents decreased from ₱20.79 billion at the end of 2025 to approximately ₱16.39 billion at September 30, 2026.
These figures deserve attention because accounting profit and cash generation are different.
A property developer may recognize income while awaiting scheduled payments from customers.
It may also need to fund construction before receiving all collections.
The company remains profitable and continues generating positive operating cash flow.
However, investors will want to determine why cash generation weakened even as consolidated earnings increased.
Sustaining residential sales and improving collections will be important.
Financing Costs and Short-Term Obligations Increase
Megaworld also reported rising financing-related expenses.
Interest and other charges increased approximately 23% to ₱5.29 billion.
The company attributed part of the increase to foreign-exchange losses.
Current liabilities also rose to approximately ₱96.35 billion, compared with ₱74.07 billion at the end of 2025.
Management identified maturing dollar-denominated bonds as an important factor.
These obligations will require continued financial management.
However, the company’s broader balance sheet also showed encouraging indicators.
Total equity increased to approximately ₱328.44 billion.
Interest-bearing loans and borrowings declined compared with the previous year-end.
The company also reported a relatively modest net debt-to-equity ratio of 0.24 times.
Those figures suggest that Megaworld retains financial flexibility.
But rising short-term obligations and lower cash balances mean liquidity deserves ongoing monitoring.
Can Megaworld Reach Its ₱125-Billion Sales Target?
The company needs approximately ₱28.4 billion in additional residential presales during the fourth quarter to achieve its annual target.
That amount is below the average quarterly presales generated during the first nine months.
This suggests the target may be achievable if demand remains relatively stable.
But management still faces uncertainty involving buyer confidence, financing conditions and project launches.
Reservations may also be affected by cancellations or changes in payment schedules.
The company must therefore maintain disciplined sales and collection practices.
Achieving the target would provide a positive signal about demand.
But investors should also assess whether those commitments translate into recognized revenue and cash over time.
The Bigger Picture: Is Megaworld Showing the Way Through the Property Slump?
Megaworld’s nine-month performance stands out in a challenging Philippine residential property market.
The company reported ₱96.6 billion in presales, a 9% increase.
Consolidated profit rose 6% to ₱19 billion.
Hotels, shopping malls and office rentals also recorded revenue growth.
Provincial developments accounted for nearly half of residential purchase commitments.
These results suggest that Megaworld’s diversified township strategy is helping it navigate softer demand.
But its financial disclosures also reveal issues that investors cannot ignore.
Operating cash flow declined.
Cash balances fell.
And financing-related expenses increased.
The company therefore faces two parallel challenges.
It must continue attracting buyers while strengthening the conversion of presales into collections and earnings.
At the same time, it must maintain the recurring-income growth that helps support its business during property-market downturns.
Megaworld’s latest results show that Philippine residential demand has not disappeared. But they do not prove that the broader property slump is over.
And as Andrew Tan’s property empire approaches its ₱125-billion annual presales target despite widespread condominium-market weakness, one question remains: Can provincial demand, hotels and shopping malls keep Megaworld growing—or will softer cash flow and rising financial obligations eventually test the strength of its township strategy?