Japan’s central bank just delivered another interest-rate increase — but financial markets reacted in almost the opposite way investors might normally expect.
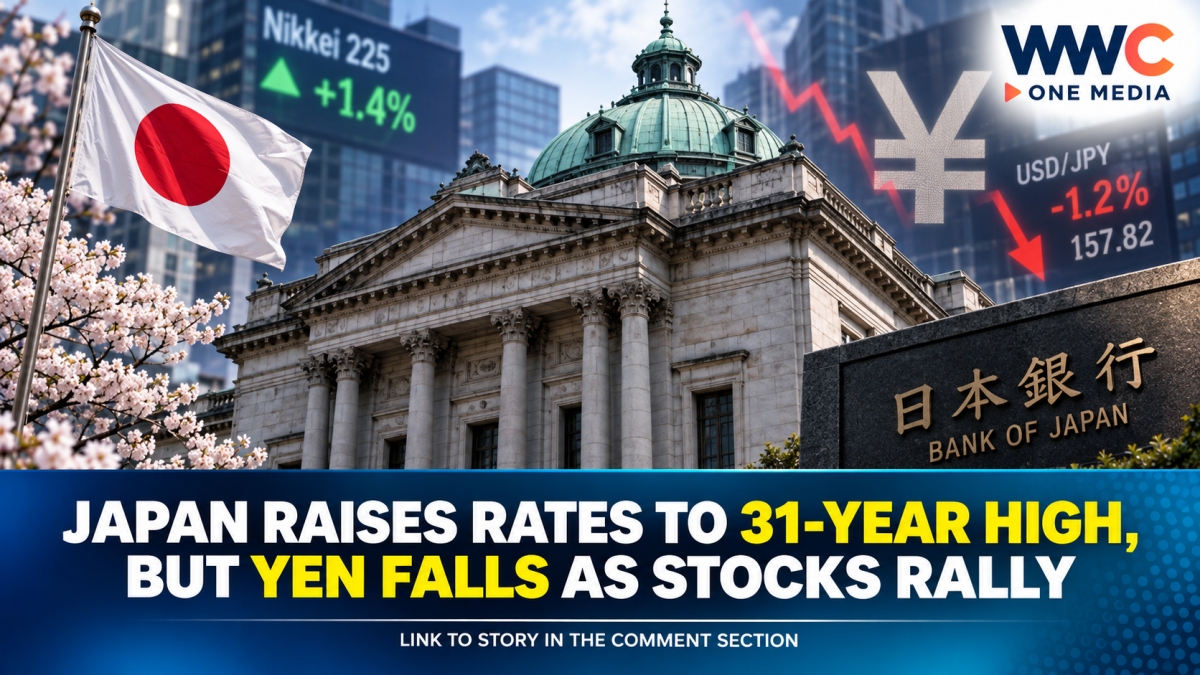
The Bank of Japan (BOJ) raised its policy rate from 1% to 1.25% on September 18, taking borrowing costs to their highest level since 1995. The decision was widely anticipated, but the yen weakened, Japanese government bond yields fell and Japanese stocks climbed.
The unexpected market reaction was driven in large part by a 7-2 vote at the BOJ and uncertainty over how aggressively policymakers will raise rates from here.
For investors, the rate increase itself was no longer the biggest story.
The real surprise was what the BOJ’s divided vote said about its next move.
BOJ pushes rates to a 31-year high
The quarter-point increase represents another step away from Japan’s decades-long era of ultra-low interest rates.
The BOJ said underlying inflation is approaching its 2% target, while Governor Kazuo Ueda indicated that monetary policy has entered a new phase in which the central bank is increasingly focused on preventing inflation from overshooting its objective.
The decision passed 7-2, with board members Toichiro Asada and Ayano Sato voting against the increase and favoring no change.
That dissent immediately became a major focus for markets.
Reuters reported that investors interpreted the split vote as a sign that the BOJ may be more cautious about additional increases than previously expected.
In other words, Japan raised rates — but the market did not necessarily hear a promise of rapid additional tightening.
The yen does the unexpected
The Japanese yen initially weakened after the decision and continued falling as investors absorbed the details.
The dollar climbed above 157 yen, with Reuters reporting a rise of more than 1.2% at one point to around 157.90, a two-week high.
That is significant because higher Japanese interest rates would ordinarily be expected to provide some support for the yen by increasing the return available from Japanese assets.
But currency markets were looking beyond Friday’s 25-basis-point increase.
The two dissenting votes raised questions about how quickly the BOJ could move again, while the Federal Reserve’s own recent rate increase kept the interest-rate gap between the United States and Japan substantial.
That combination helped keep pressure on the yen.
Japanese stocks rally instead of falling
Japanese equities also delivered an unusual response.
The Nikkei 225 rose roughly 1.4% to 1.7%, with Reuters and other market reports attributing part of the move to the weaker yen.
A weaker yen can benefit major Japanese exporters because overseas revenue can translate into more yen when brought back into Japan.
That helped offset the conventional concern that higher interest rates could increase financing costs and pressure equity valuations.
The result was a striking market combination:
BOJ rates up.
Yen down.
Bond yields down.
Japanese stocks up.
That unusual configuration is what made the September decision particularly important for investors.
Japanese bond yields also move lower
Japanese government bonds delivered another surprise.
The yield on the two-year Japanese government bond, which is particularly sensitive to expectations for monetary policy, fell after the BOJ decision. Reuters reported that the yield declined to around 1.82%, while the 10-year JGB yield also moved lower.
Bond yields move inversely to prices, meaning falling yields indicate that bond prices were rising.
The market reaction again suggested that investors viewed the BOJ’s decision as less aggressive than a simple headline reading of “rate hike” might imply.
Why the two dissenting votes mattered so much
The BOJ’s internal split is arguably the most important detail behind Friday’s market reaction.
The rate increase itself had been heavily anticipated.
What surprised investors was that two policymakers opposed it.
That matters because markets are constantly attempting to price the next move, not merely the decision that has already happened.
If investors believe the BOJ will continue raising rates rapidly, Japanese yields could move higher and the yen could strengthen.
But if the central bank signals that future increases will be gradual and dependent on incoming economic data, investors may reduce those expectations.
Reuters quoted analysts who described the outcome as tempering expectations for further rate increases.
Ueda leaves the door open
BOJ Governor Kazuo Ueda did not rule out additional increases.
He said that if risks of underlying inflation overshooting the 2% target materialize, that could hurt the Japanese economy, emphasizing the need to stabilize underlying inflation around the target.
At the same time, the BOJ has not committed to a predetermined sequence of rate increases.
That distinction is crucial.
The central bank is clearly moving away from its ultra-loose monetary-policy regime, but the pace of normalization remains dependent on inflation, wages, economic growth, financial conditions and external risks.
Japan is tightening as other central banks also fight inflation
The BOJ’s move came during an unusually busy week for global central banks.
The U.S. Federal Reserve also raised its benchmark rate, while the European Central Bank has been dealing with persistent inflation pressures. Oil prices above $100 a barrel have added another complication because energy costs can feed directly into inflation.
That creates a complicated environment for Japan.
A faster BOJ tightening cycle could support the yen and help limit imported inflation.
But significantly higher Japanese borrowing costs could also put pressure on households, companies and heavily indebted parts of the economy.
The yen remains the biggest market question
The currency reaction is likely to remain one of the most closely watched consequences of the BOJ decision.
Japan has previously taken steps to support the yen when excessive weakness threatened to push up import costs.
Reuters reported that Japanese officials remained attentive to currency movements after the latest BOJ decision.
A sustained weaker yen could make imported energy and other commodities more expensive for Japanese consumers and businesses.
At the same time, Japanese exporters could benefit from stronger overseas earnings when converted into yen.
That creates competing economic effects — one reason policymakers have to balance currency movements against inflation and growth.
What happens next?
The September rate hike marks another milestone in Japan’s gradual monetary-policy normalization.
But Friday’s market reaction shows that the headline rate itself is no longer enough to understand the BOJ’s direction.
Investors will now be watching several things closely:
- Whether Japanese inflation continues to remain near or above the BOJ’s target
- Whether wage growth remains strong enough to support household spending
- Whether the yen continues weakening despite higher Japanese interest rates
- Whether the BOJ’s two dissenters represent a broader resistance to faster tightening
- How the Federal Reserve’s policy affects the U.S.-Japan interest-rate gap
- Whether higher energy prices create another wave of imported inflation
The BOJ has raised rates to 1.25%, the highest level in roughly three decades.
Yet instead of triggering a stronger yen and higher bond yields, the decision initially produced the opposite market reaction.
And that leaves investors with a bigger question than the rate hike itself: was Japan’s latest move the beginning of a faster tightening cycle — or a signal that the road ahead will be much more cautious?