India turned to an unlikely financial backstop when pressure on the rupee intensified: the millions of Indians living abroad.
The result was far larger than policymakers initially expected.
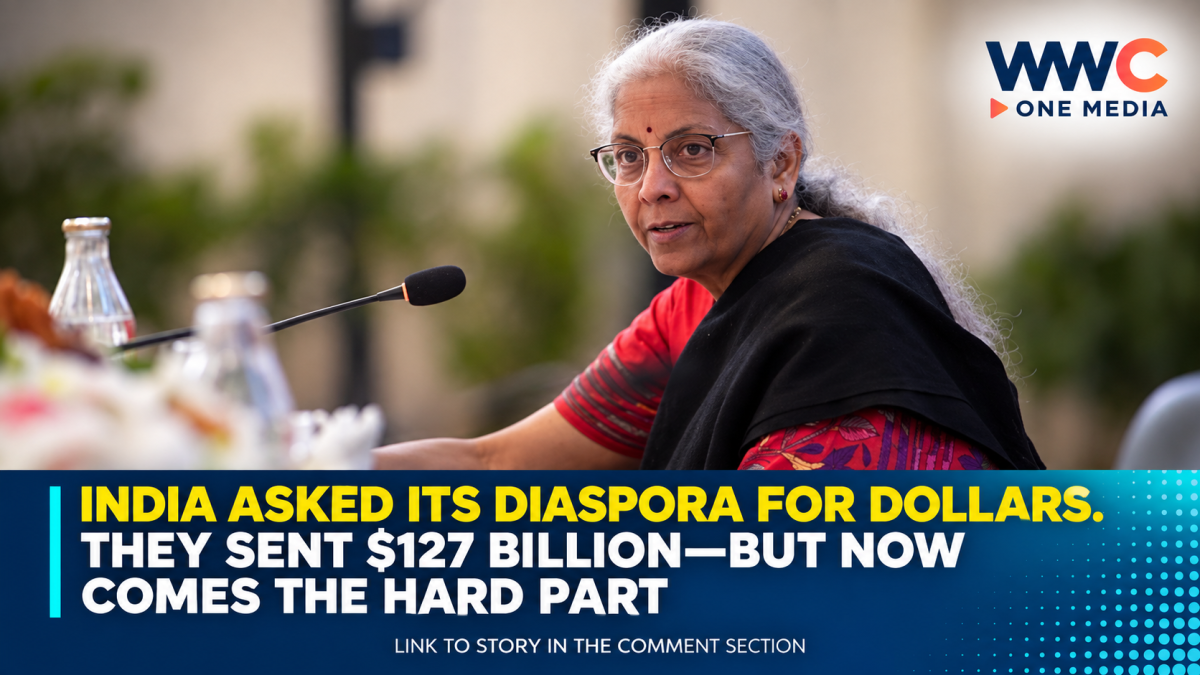
A special foreign-currency deposit campaign backed by the Reserve Bank of India attracted roughly $127.23 billion through Foreign Currency Non-Resident (Bank), or FCNR(B), deposits, according to RBI data reported in early September. When overseas foreign-currency borrowings and external commercial borrowings are included, total mobilized inflows reached about $136.38 billion.
The campaign was designed to bring dollars into India’s financial system while pressure on the rupee was intensifying.
But the enormous response has created a new question for policymakers:
What happens after the dollars arrive?
India turned to its 35 million-strong diaspora
India’s overseas population has become an increasingly important source of foreign currency.
The country has an estimated 35 million-strong diaspora, ranging from workers and entrepreneurs in the Gulf to professionals and high-net-worth investors in North America, Europe and Asia. Bloomberg reported that Indian banks mounted an unusually aggressive international campaign to attract their savings, using relationship managers, overseas branches and diaspora networks.
The campaign accelerated after the rupee came under pressure from higher energy costs, geopolitical uncertainty and global interest-rate movements.
In June, the RBI introduced measures allowing banks to offer more attractive FCNR(B) deposit rates while the central bank absorbed the banks’ hedging costs for qualifying three- to five-year deposits.
The objective was straightforward: bring in dollars without forcing banks to bear the full cost of protecting themselves against currency fluctuations.
Reuters reported at the time that banks expected the program could initially generate roughly $35 billion to $40 billion. The eventual response was dramatically larger.
The numbers exploded beyond expectations
By Aug. 21, the RBI said FCNR(B) deposits had already reached $65.397 billion, while total foreign-currency inflows under the broader measures had reached about $72.85 billion.
By the end of the special window on Aug. 31, the FCNR(B) figure had climbed to approximately $127.23 billion.
Adding other overseas foreign-currency debt and external commercial borrowing brought the total to roughly $136.38 billion, substantially exceeding the RBI’s earlier target of $80 billion.
India subsequently closed the special FCNR(B) window a month earlier than originally planned because the targeted inflows had already been achieved.
The Indian government said the program’s response demonstrated strong participation from the diaspora and described it as an unusually large mobilization of foreign exchange.
Why overseas Indians responded
The attraction was not simply patriotism.
Banks were able to offer unusually competitive returns on dollar deposits because of the RBI’s support.
Bloomberg reported that some lenders offered rates as high as 7.75% during the campaign. The combination of dollar-denominated deposits, relatively attractive returns and protection from rupee-dollar exchange-rate risk helped turn what is normally a relatively conventional banking product into a major fundraising effort.
Some investors also viewed the deposits as an alternative to more volatile assets.
Bloomberg reported examples of overseas Indians putting substantial sums into FCNR(B) deposits, including investors who cited retirement planning, currency considerations and the attraction of fixed returns.
Banks expanded their outreach accordingly.
HSBC, for example, held roadshows for wealthy and ultra-high-net-worth Indians in several international financial centers, including Hong Kong, Manila, Singapore and the Middle East, according to people cited by Bloomberg.
Modi also made a direct appeal to overseas Indians
The effort extended beyond the banking industry.
During a June event in Paris, Indian Prime Minister Narendra Modi urged overseas Indians to deepen their economic engagement with India, according to Bloomberg reporting carried by NDTV. The appeal came as India faced higher energy costs and pressure on the rupee.
That appeal formed part of a wider effort to tap India’s overseas community not only through remittances but also through deposits, investments and other financial channels.
India’s diaspora is already a major source of foreign currency.
World Bank data cited by Bloomberg/NDTV showed that remittances to India exceeded $150 billion in 2025, making India the world’s largest recipient of remittances.
However, it is important not to confuse those remittances with the $127 billion FCNR(B) figure.
Remittances are money sent home by overseas Indians, while FCNR(B) deposits are foreign-currency bank deposits held by eligible non-residents. The two represent different financial flows.
The rupee still faces pressure
The success of the deposit campaign does not mean the rupee’s problems have disappeared.
On Sept. 17, the rupee fell through the 96-per-dollar level, reaching 96.08 after the U.S. Federal Reserve raised interest rates, according to Reuters.
Traders said state-owned banks were seen offering dollars, likely on behalf of the RBI, while the central bank was also believed to have used dollar-rupee swaps.
Reuters reported that the RBI’s market operations were aimed at limiting pressure on the currency while also managing excess rupee liquidity in India’s banking system.
The timing illustrates the distinction between building foreign-exchange buffers and permanently changing the underlying forces that determine a currency’s value.
The $127 billion campaign gave India a much larger pool of foreign currency.
It did not eliminate the impact of oil prices, global interest rates, capital flows or India’s external financing needs.
And now the RBI has a liquidity problem of its own
The success of the program produced another challenge.
When banks bring large amounts of dollars into the country and exchange them through the RBI’s arrangements, the banking system can receive substantial amounts of rupees.
That creates excess domestic liquidity.
Bloomberg reported that the flood of deposits pushed banking-system surplus liquidity to extremely high levels, forcing policymakers to consider how to absorb the additional cash.
The RBI has several tools available, including open-market operations, reverse-repurchase facilities and foreign-exchange swaps.
RBI Governor Sanjay Malhotra has said the central bank has sufficient tools to manage the liquidity created by the inflows.
Reuters separately reported that excess liquidity had fallen to its lowest level since Aug. 31 after tax payments and recent RBI foreign-exchange operations.
The hidden cost: these dollars aren’t free
The $127 billion headline is enormous, but it should not be interpreted as $127 billion of permanent capital for India.
FCNR(B) deposits are liabilities of the banking system.
The deposits raised during the campaign have maturities of roughly three to five years, meaning the dollars eventually have to be returned to depositors. Bloomberg reported that economists viewed the funds as future dollar-denominated liabilities rather than a permanent addition to India’s financial resources.
There are also costs associated with the RBI’s decision to absorb banks’ currency-hedging expenses.
One analysis cited by Moneycontrol estimated that the favorable swap arrangements and associated liquidity management could cost the RBI as much as 1.2 trillion rupees, or about $12.7 billion, over five years. That is an estimate, not an official RBI cost figure, and the central bank had not publicly confirmed the calculation.
That distinction is crucial.
The program delivered an enormous quantity of foreign currency quickly—but it also created future obligations and potential costs.
India has used this playbook before
The strategy is not entirely new.
During the 2013 “taper tantrum,” when expectations of tighter U.S. monetary policy triggered capital outflows from emerging markets, India used special FCNR(B) measures to attract dollars from its overseas population.
The earlier program raised roughly $26 billion, according to the Indian government’s comparison of the two initiatives.
Other Indian reports put the 2013 mobilization at roughly $34 billion depending on the definition of the flows included, so comparisons should specify exactly what is being counted.
The 2026 response, however, was substantially larger under the reported FCNR(B) measure.
That reflects the dramatic increase in India’s overseas wealth over the past decade.
The bigger shift: India’s diaspora is becoming a financial policy tool
The most important development may not be the $127 billion headline itself.
It is the growing role of India’s overseas population in the country’s financial strategy.
For decades, remittances from Indians abroad have provided a relatively stable source of foreign currency.
Now policymakers and banks are increasingly looking at the diaspora as a source of deposits, investment capital, foreign-currency funding and broader participation in India’s financial markets.
The expansion of India’s GIFT City financial hub is part of that broader effort. Banks and financial firms have been using international financial centers and India’s own international financial-services ecosystem to reach wealthy overseas Indians.
The economic significance is considerable.
India is simultaneously one of the world’s largest recipients of remittances and one of the world’s largest emerging economies. Its overseas population therefore represents a substantial financial network extending across the Gulf, North America, Europe and Asia.
But the rupee story isn’t over
The record inflow has strengthened India’s external buffers and provided the RBI with additional foreign-currency resources.
Yet the latest currency trading shows why policymakers remain active.
On Sept. 17, even after the enormous diaspora mobilization, the rupee weakened past 96 per dollar as higher U.S. rates and broader global pressures weighed on emerging-market currencies. Reuters reported that the RBI was likely intervening to limit the decline.
That leaves India with a delicate balancing act.
The country has successfully attracted an extraordinary amount of foreign currency from its diaspora.
Now it must manage the liquidity, hedging costs, future repayment obligations and currency pressures that come with that success.
The $127 billion campaign may therefore prove to be one of India’s most powerful short-term foreign-exchange operations in years.
But the next chapter will be about what happens when those dollars have to be managed—and eventually returned.
The diaspora answered India’s call for dollars. The harder question may be what India does with them next.