MANILA, PHILIPPINES — Philippine digital financial services giant Maya is stepping up its fight against online fraud by strengthening cooperation with the Department of Justice (DOJ), regulators, telecommunications providers and law enforcement agencies as increasingly sophisticated scams threaten the financial security of millions of Filipinos.
The initiative comes amid alarming findings that 84% of Filipino adults encountered at least one scam attempt over the past year, while estimated nationwide financial losses reached ₱121.8 billion, according to the 2026 State of Scams Philippines report.
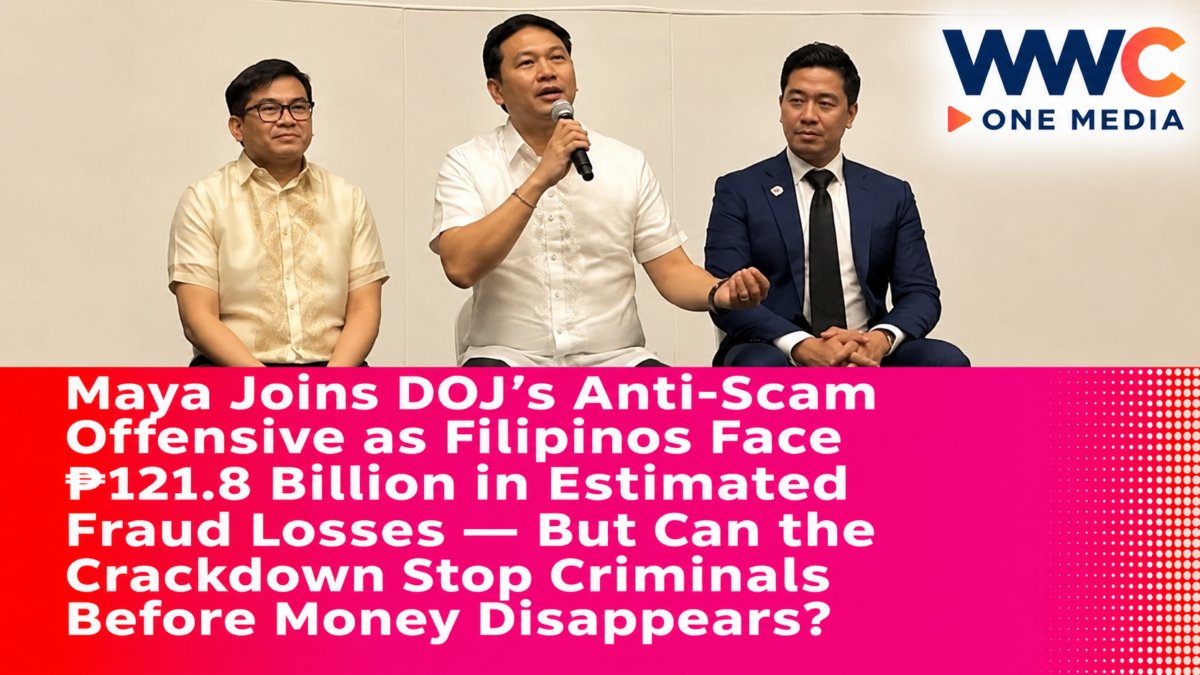
Maya backed the DOJ–Office of Cybercrime’s CyberReady Campus Tour at the University of the Philippines Diliman, highlighting the growing importance of cybersecurity awareness, coordinated investigations and stronger financial safeguards.
Speaking at the event, Maya Head of Corporate Affairs Kristoffer Rada emphasized that protecting consumers requires cooperation between government and private institutions.
The company is also participating in a DOJ-led technical working group examining financial cybercrime concerns.
Maya’s involvement comes as the Philippines strengthens enforcement of the Anti-Financial Account Scamming Act, a law designed to combat social engineering, money-mule operations and fraudulent financial transactions.
But despite stronger regulations and new technologies, scammers continue adapting their tactics.
As Maya joins government agencies in the battle against digital fraud, can faster intelligence sharing and stronger account-security measures protect Filipino consumers—or are cybercriminals evolving faster than the country’s defenses?
Maya Supports DOJ’s CyberReady Campus Tour at UP Diliman
Maya’s latest initiative centers on the Department of Justice–Office of Cybercrime’s CyberReady Campus Tour at the University of the Philippines Diliman.
The program promotes cybersecurity awareness among students, faculty members and other participants.
During the event, attendees were encouraged to recognize fraudulent schemes, protect personal information and practice safer digital financial habits.
Maya Head of Corporate Affairs Kristoffer Rada participated alongside DOJ–Office of Cybercrime representatives, including Director Dr. Aris S. Manguera and prosecutor Chris Jark Ace M. Maño.
The initiative reflects growing recognition that cybercrime prevention must extend beyond banking applications and financial institutions.
Many fraudulent transactions begin outside the banking system.
Victims may encounter deceptive social media messages, fraudulent shopping promotions, impersonation calls or links designed to capture account credentials.
By the time funds are transferred, criminals may already have manipulated their targets into authorizing payments.
The campus initiative aims to help consumers recognize warning signs before financial losses occur.
Why Maya Says Fighting Scams Requires More Than Technology
According to Maya, stronger cybersecurity requires cooperation among financial institutions, government agencies, telecommunications providers and consumers.
The company argues that individual organizations cannot fully address fraud schemes operating across different platforms and jurisdictions.
For example, a criminal may contact a potential victim through a messaging application, persuade them to disclose information through a fraudulent website and then move stolen funds through several financial accounts.
Investigating such activity can require evidence from multiple organizations.
Banks may hold transaction records.
Telecommunications companies may possess relevant registration and communications information, subject to applicable law.
Law enforcement agencies may need to obtain evidence, identify suspects and coordinate prosecutions.
Rada emphasized that existing laws must be supported by practical cooperation and implementation.
The challenge is turning these different capabilities into a coordinated response while respecting data privacy, due process and legal safeguards.
₱121.8 Billion in Estimated Scam Losses Raises the Stakes
The scale of the problem is illustrated by the 2026 State of Scams Philippines report.
Prepared by the Global Anti-Scam Alliance in collaboration with Mastercard and Gogolook, the study surveyed 1,160 Filipino adults.
It found that 84% encountered a scam attempt during the preceding year, compared with 77% in the previous survey.
Approximately 15% reported losing money or personal information that resulted in financial losses.
The report estimated total annual losses at ₱121.8 billion.
However, this figure requires careful interpretation.
It is a survey-based estimate extrapolated to the country’s adult population, rather than an independently audited total of confirmed fraudulent transactions.
It is also not an estimate of losses specifically involving Maya.
Nevertheless, the findings point to widespread scam exposure and significant potential harm to consumers.
The report also found that many scam victims did not report their experiences to authorities.
That creates an additional challenge for investigators because unreported fraud may make organized criminal activity harder to identify.
Digital Wallets Are Becoming a Major Target
The growing popularity of digital wallets has transformed how Filipinos pay bills, transfer money and purchase products.
Mobile financial services provide convenience, especially for customers who prefer not to visit traditional bank branches.
But criminals have also adapted.
According to the 2026 scam survey, 73% of respondents who suffered financial losses said scammers received payments through digital wallets.
That compares with 34% in the previous year’s survey.
The figures describe payment channels reported by affected survey respondents.
They do not establish that digital wallets are inherently less secure than all other payment methods or that the reported losses occurred on a particular provider’s platform.
Fraudsters can exploit legitimate payment systems through deception.
A customer may be persuaded to send money voluntarily to someone falsely claiming to be a seller, employer, investor or bank representative.
Because the victim initiates the transfer, identifying the fraud before the money leaves the account can be particularly difficult.
Anti-Financial Account Scamming Act Strengthens Legal Protection
Republic Act No. 12010, the Anti-Financial Account Scamming Act (AFASA), provides an important legal framework for combating financial fraud.
Signed into law in July 2024, AFASA defines and penalizes activities involving money mules and social engineering.
Money-mule operations can involve accounts used to receive, conceal or transfer proceeds from criminal activity.
Social engineering involves deception intended to obtain sensitive financial information and gain unauthorized access or control over accounts.
The law also requires covered financial institutions to maintain appropriate risk management systems and safeguards.
These can include multifactor authentication, fraud management systems and customer verification procedures.
Under applicable BSP rules, institutions may take authorized measures involving suspicious or disputed transactions.
However, those powers are subject to legal conditions and procedural safeguards.
AFASA does not mean that all disputed transfers are automatically refundable.
Nor does it guarantee that every scammer can be identified or prosecuted.
Its effectiveness depends on implementation, evidence gathering, institutional cooperation and enforcement.
BSP and DOJ Strengthen Financial Crime Investigations
Maya’s participation in government-led anti-scam initiatives comes after a significant regulatory development.
On July 22, 2026, the Bangko Sentral ng Pilipinas and Department of Justice signed an information-sharing agreement to strengthen investigations and prosecutions under AFASA.
The arrangement establishes procedures for authorized DOJ requests for relevant financial-account information from the BSP.
It also includes safeguards governing how that information may be accessed and used.
The agreement is intended to improve the ability of investigators to trace suspicious transactions and identify people involved in financial scams.
Earlier in 2026, the BSP also signed related agreements with other enforcement and regulatory agencies.
These developments demonstrate a wider effort to improve coordination.
But faster information sharing does not automatically result in the recovery of stolen funds.
Successful investigations still require timely reporting, legally obtained evidence and appropriate action by the relevant institutions.
Maya Joins Financial Cybercrime Technical Working Group
Beyond supporting the campus seminar, Maya participates in the DOJ–Office of Cybercrime’s Technical Working Group on Financial Cybercrime Concerns.
The working group brings together government regulators, financial institutions and telecommunications-sector participants.
According to Maya, participating organizations include representatives of the Department of Trade and Industry, Bangko Sentral ng Pilipinas and National Telecommunications Commission.
The initiative provides a forum for discussing financial fraud risks and opportunities to improve coordination.
Maya also supports the Cybercrime Investigation and Coordinating Center’s Scam Safe initiative.
That cooperation builds on activities the company previously announced in January 2026.
However, membership in a technical working group should not be confused with a new financial agreement, government contract or automated system for freezing suspected fraudulent accounts.
The company’s announcement focuses on institutional collaboration, consumer education and the use of existing safeguards.
Maya’s Security Center Helps Customers Protect Accounts
Maya has also highlighted security features already available through its digital financial platform.
Its in-app Security Center allows eligible customers to review account activity and manage selected security settings.
Depending on the account and product, users can review login history, manage trusted devices and adjust certain transfer limits.
The app also provides a card-freezing function for eligible credit card products.
These tools can help customers respond when they detect suspicious activity.
For example, reviewing login history may reveal an unfamiliar device or unexpected account access.
Transfer limits can reduce the amount a customer is able to send through covered transaction channels.
A card-freezing feature can help prevent additional card use while a suspected security issue is investigated.
However, such features do not guarantee protection against every form of fraud.
A scammer may still convince an account holder to authorize a payment, disclose sensitive information or change security settings.
Customers should therefore treat these features as part of a broader security strategy.
Philippine Banks Are Struggling to Detect Fraud Before Payments Leave
The challenges facing Maya are part of a broader regional problem.
WWC ONE MEDIA previously reported on Asia-Pacific Banks Struggling to Detect Scams Before Customers Lose Money.
That report examined concerns among banking executives about their institutions’ ability to identify situations where customers are being manipulated into authorizing fraudulent payments.
Traditional systems are often designed to detect unauthorized access or unusual transaction patterns.
But a social engineering scam may involve a legitimate customer completing a transaction after being deceived.
The payment may appear technically authorized even though its underlying purpose is fraudulent.
This creates a difficult balance for financial institutions.
They must detect suspicious behavior without unnecessarily delaying legitimate payments.
The problem reinforces why customer awareness, bank-level monitoring and interagency coordination are all necessary.
Fraud-Prevention Companies See Growing Demand in the Philippines
The rise of digital scams is also encouraging financial institutions to adopt specialized fraud-detection technology.
WWC ONE MEDIA previously examined the trend in Philippine Digital Finance Market Emerges as Key Growth Opportunity for Global Fraud-Prevention Firm.
That article covered the growing demand for tools capable of identifying suspicious account activity, fraudulent identities and unusual transaction behavior.
Advanced monitoring systems can analyze multiple signals, including patterns associated with transaction risk.
However, technology cannot replace institutional judgment or legal requirements.
Automated systems can generate false alarms.
They may also fail to recognize previously unseen fraud techniques.
For Maya and other digital finance providers, the challenge is combining effective detection with a reliable customer experience.
NTC Crackdown Targets Suspicious SIM Card Registrations
Telecommunications infrastructure is another major part of the fight against scams.
Fraudsters frequently use phone calls and text messages to impersonate banks, delivery companies, government agencies and online sellers.
WWC ONE MEDIA previously reported on NTC Targeting Owners of More Than 100 SIM Cards in Nationwide Scam Crackdown.
The initiative involves additional scrutiny of unusually large numbers of SIM cards registered under individual names.
Its purpose is to strengthen verification and address potential misuse of telecommunications services.
This is relevant to financial fraud because phone numbers are often used during impersonation and phishing attempts.
But tighter SIM registration alone cannot eliminate scams.
Criminals may also use compromised accounts, international numbers, messaging applications or stolen identities.
A comprehensive response therefore requires cooperation across both telecommunications and financial systems.
Police Enforcement Remains Essential
Consumer education can reduce exposure to scams, but criminal investigations remain necessary.
WWC ONE MEDIA examined enforcement challenges in PNP’s Cybercrime War Is Escalating: 86 Arrested, 201 Cases Filed — But What Are Scammers Doing Next?.
The report highlighted Philippine National Police efforts to pursue suspected cybercriminals and investigate technology-enabled fraud.
Such operations are important because scam networks may involve multiple participants.
One person may operate a fraudulent advertisement.
Another may communicate with victims.
Others may receive or transfer proceeds through financial accounts.
Disrupting these networks often requires evidence linking participants and transactions.
Government and private-sector information sharing may help investigators establish those connections.
However, arrests and filed cases are not equivalent to final convictions.
The outcome of criminal proceedings depends on evidence and judicial decisions.
Artificial Intelligence Could Make Future Scams Harder to Detect
Cybercriminals are also adopting increasingly sophisticated technologies.
Artificial intelligence can help produce convincing messages, imitate communication styles and personalize fraudulent approaches.
Some attackers may use synthetic audio or visual content to impersonate trusted people.
WWC ONE MEDIA previously reported on INTERPOL Warning That Agentic AI Could Automate Cyberattacks and Scale Scams.
The report examined concerns that AI-enabled tools could make certain cybercrime activities faster and more scalable.
The implications are significant for financial institutions.
A fraudulent message may contain fewer spelling mistakes or obvious warning signs than older phishing attempts.
A voice call may sound convincing even when the caller is not who they claim to be.
As these tools evolve, relying exclusively on appearance, language or caller familiarity becomes increasingly risky.
Independent verification remains essential.
Holiday Shopping Season Creates New Opportunities for Fraudsters
Maya’s announcement comes ahead of the year-end shopping season, when more consumers are expected to purchase products, send payments and respond to promotions online.
Fraudsters may exploit this activity through fake discounts, fraudulent payment requests and counterfeit shopping websites.
A common scenario involves a customer receiving a message claiming that an order cannot be delivered until an additional fee is paid.
Another involves a fake seller demanding an immediate transfer to secure a heavily discounted product.
Investment and employment scams may also promise unusually attractive returns or earnings.
Consumers should verify sellers and payment instructions through trusted channels rather than relying on unsolicited links.
They should also avoid sharing passwords, one-time passwords or PINs with anyone claiming to represent a financial institution.
A legitimate-looking logo, familiar company name or professional message does not guarantee authenticity.
What Maya Customers Should Do if They Suspect a Scam
Customers who receive suspicious requests should avoid clicking unfamiliar links or providing confidential account credentials.
If an unexpected message appears to come from Maya, users should verify it through the official app or the company’s published support channels.
Customers can review available Security Center features and check for unfamiliar account activity.
Those who suspect unauthorized access should promptly secure their accounts and contact Maya through official support channels.
If money has already been transferred, reporting the incident quickly may improve the chance that relevant institutions can investigate and take action.
However, recovery is not guaranteed.
Customers should preserve relevant transaction details, communications and other evidence that could assist with a complaint.
They may also report suspected cybercrime through authorized government channels.
The Bigger Picture: Can the Philippines Make Digital Finance Safer?
Maya’s support for the DOJ’s CyberReady Campus Tour illustrates an important shift in the country’s approach to financial cybersecurity.
Instead of relying entirely on banks or individual consumers, the response increasingly involves cooperation among regulators, law enforcement, telecommunications providers and technology companies.
That approach is necessary because modern scams frequently cross multiple digital systems.
A fraudulent interaction may begin on social media, move to a messaging application and end with a payment through a financial account.
No single institution sees every part of the process.
The Anti-Financial Account Scamming Act provides a legal foundation for stronger safeguards and investigations.
Maya’s Security Center provides customers with practical account-management tools.
Government working groups and information-sharing agreements can support coordinated responses.
But the success of these efforts must ultimately be measured by whether scam attempts are detected earlier, victims receive timely assistance and criminals face effective investigation.
For millions of Filipinos using digital wallets and online banking, the stakes are substantial.
As Maya strengthens cooperation with the DOJ and the Philippines confronts an estimated ₱121.8 billion in annual scam losses, can better technology, tougher enforcement and stronger consumer awareness finally turn the tide against online fraud—or will increasingly sophisticated cybercriminals remain one step ahead?