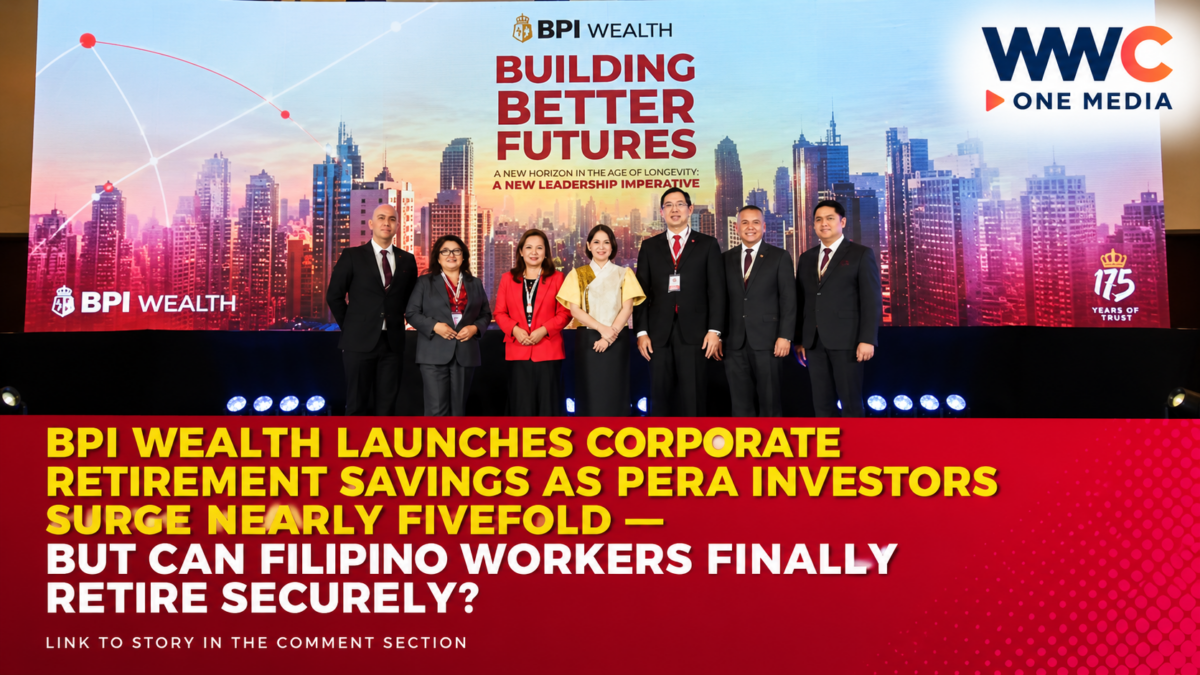
MANILA, Philippines — October 30, 2026. Bank of the Philippine Islands (BPI) is taking a major step toward expanding retirement investment access among Filipino employees, introducing a workplace-based savings program as national participation in tax-advantaged retirement accounts climbs to more than 30,000 contributors.
Through its wealth management subsidiary, BPI Wealth, the bank has launched BPI Corporate Personal Equity and Retirement Account (PERA), an employer-supported retirement savings solution designed to make long-term investing more accessible to Filipino workers.
The initiative allows participating companies to incorporate PERA into their employee benefits packages while giving workers the freedom to decide whether to enroll and how much they can afford to invest.
The launch comes as Bangko Sentral ng Pilipinas data show that PERA participation surged to 30,055 contributors as of June 2026, compared with 6,193 in June 2025.
That represents an increase of approximately 385% in the number of contributors within one year.
But despite the rapid growth, PERA participation remains small relative to the size of the Philippine workforce.
Can BPI’s workplace retirement initiative convince more Filipinos to prepare financially for life after employment, or will rising living costs continue to make long-term savings difficult for ordinary workers?
BPI Wealth brings retirement investing directly to employers
BPI Corporate PERA was introduced during the company’s “Building Better Futures 2026: Retirement in the Age of Longevity, A New Leadership Imperative” event, held as part of BPI Wealth’s Wealth Wellness Month.
The initiative reflects a growing recognition that retirement preparation should involve cooperation among workers, employers, financial institutions and government agencies.
Instead of expecting employees to discover and arrange retirement investment products independently, BPI Wealth is encouraging companies to include PERA within their existing employee benefits systems.
The approach could make it easier for workers to become familiar with retirement investment options and incorporate regular contributions into their financial planning.
However, participation remains voluntary.
Employees are not automatically required to open an account simply because their employer offers the program.
They also retain responsibility for choosing contribution amounts according to their financial circumstances and retirement objectives.
BPI Wealth president and chief executive officer Maria Theresa D. Marcial said the initiative is intended to help employees develop financial confidence through early and consistent investing.
The company is positioning the offering as a long-term financial wellness benefit rather than an immediate cash incentive.
PERA membership jumps from 6,193 to 30,055 contributors
The launch follows a dramatic increase in participation in the Philippines’ voluntary retirement investment system.
According to BSP figures, the number of PERA contributors reached 30,055 as of June 2026.
That compares with just 6,193 contributors a year earlier.
In absolute terms, the increase represents 23,862 additional contributors.
The total number grew to approximately 4.85 times its previous level.
Reported contributions reached ₱757.55 million as of June 2026.
The figures suggest that awareness and adoption of PERA are improving, supported by digital onboarding, financial education and initiatives encouraging employers to participate.
But the number remains modest compared with the millions of Filipinos who depend on income from employment or self-employment.
This gap creates an opportunity for banks and other authorized providers to expand retirement investment access.
It also highlights an important policy challenge.
Opening more investment accounts does not necessarily mean that every contributor is saving enough to finance retirement.
The adequacy of retirement savings depends on contribution amounts, investment performance, inflation, retirement age and expected living expenses.
What is PERA, and how does it work?
The Personal Equity and Retirement Account was established under Republic Act No. 9505, commonly known as the PERA Act of 2008.
It is a voluntary retirement savings and investment arrangement intended to supplement, rather than replace, benefits from the Social Security System, Government Service Insurance System and other retirement programs.
Unlike an ordinary savings account, PERA allows eligible contributors to invest through authorized financial products while receiving certain tax advantages.
The account belongs to the individual contributor.
This portability is particularly important for employees who change jobs during their careers.
Workers may maintain their PERA arrangements independently of a particular employer, subject to the applicable account and administrative rules.
Qualified contributions are entitled to an annual tax credit equivalent to 5% of eligible contributions, subject to regulatory conditions.
Investment earnings within qualifying PERA products generally enjoy specified tax exemptions.
Qualified retirement withdrawals may also receive favorable tax treatment.
However, not every withdrawal automatically qualifies for tax-free treatment.
The applicable rules include retirement eligibility conditions, generally involving age 55 and contributions for at least five years, as well as specific exceptions.
Early withdrawals outside qualifying circumstances may have tax consequences.
New retirement tax incentives could attract more employers
One of the most important developments behind the workplace PERA strategy involves enhanced incentives for employers.
Under the Capital Markets Efficiency Promotion Act, private employers that meet the qualifying contribution requirements may claim tax deductions totaling 150% of eligible employer contributions.
The incentive combines the 100% deduction provided under the PERA framework and an additional 50% deduction.
The BSP has explained that the enhanced deduction applies to qualifying employers that match or exceed the PERA contributions of eligible employees.
The arrangement potentially benefits both parties.
Workers receive another opportunity to accumulate retirement investments.
Employers may receive tax benefits while strengthening their employee welfare packages.
But a 150% deduction does not mean companies automatically receive 150% of their contributions back in cash.
A tax deduction reduces the amount of income subject to applicable taxation, subject to the governing rules.
Actual tax savings depend on eligibility, the company’s taxable position and other factors.
Businesses should therefore evaluate the legal requirements and administrative costs before adopting the program.
Workers can begin investing through BPI Wealth with ₱1,000
BPI Wealth has previously announced that individuals can open a PERA account through its e-Invest platform with a minimum initial investment of ₱1,000.
The relatively modest entry amount is intended to make retirement investing more accessible to individuals who may not have substantial savings.
However, the exact onboarding arrangements for corporate participants may differ depending on an employer’s program and the investment products selected.
Workers should confirm the applicable minimums, fees, investment choices and account requirements before enrolling.
The ability to start with a small contribution may encourage participation among younger employees.
But beginning with ₱1,000 does not guarantee a particular retirement outcome.
Investment balances may rise or fall depending on the performance of the underlying assets.
Contributors also need to consider whether their chosen investment strategy matches their time horizon and tolerance for losses.
Financial education remains a critical part of the program
For many Filipinos, understanding investment risk may be as important as gaining access to an investment account.
BPI Foundation has been expanding financial literacy initiatives focused on saving, debt management, investing, fraud prevention and retirement preparation.
WWC ONE MEDIA previously covered these efforts in BPI Foundation Expands Financial Literacy Program With FEU as Outreach Reaches 55,000 Filipinos — But Teaching Money Skills Is Only the Beginning.
The foundation reported reaching more than 55,000 people through financial education activities by September 2026.
That achievement demonstrates growing outreach, but it does not establish that all participants improved their financial circumstances.
The distinction is relevant to retirement programs.
Workers need to understand not only how to contribute but also how investment risk, charges and long-term financial obligations can affect their savings.
BPI Wealth sees growing opportunity in retirement investing
BPI Wealth’s workplace initiative is part of a wider business strategy to expand the use of investment products among Filipinos.
In August 2026, the company said it was targeting a 15% to 20% increase in assets under management for the year.
Marcial cited the firm’s historical asset growth and expanding retirement investment initiatives.
The company has also continued investing in wealth management technology.
In August, BPI Wealth announced plans to adopt BlackRock’s Aladdin investment and wealth management platforms to strengthen risk analytics, portfolio oversight and investment management operations.
These initiatives illustrate how BPI Wealth is combining technology, employer partnerships and client education to expand its business.
However, an assets-under-management growth target is not a guaranteed result.
Nor does the introduction of new investment technology guarantee better market performance for clients.
The effectiveness of these measures will depend on execution, investor participation and market conditions.
Security Bank and EastWest are also exploring the PERA opportunity
BPI Wealth is not the only financial institution targeting Philippine retirement savings.
In April 2026, EastWest Bank became the first universal bank to introduce an employer-sponsored PERA arrangement with voluntary enrollment, according to the BSP.
This distinction is important because BPI Corporate PERA should not be described as the country’s first workplace PERA initiative.
Other banks are also examining opportunities to expand retirement investment access.
Security Bank has indicated interest in PERA-related offerings alongside its digital financial services strategy.
WWC ONE MEDIA reported this development in Security Bank Targets Apple Pay and Google Pay Integration for Cards by 2027.
The report examined Security Bank’s payment modernization plans and its consideration of retirement investment products.
Together, these developments suggest that retirement savings could become an increasingly competitive segment of Philippine financial services.
For workers, additional providers may offer more product choices and account access.
But those benefits depend on fees, investment options, service quality and clear consumer disclosures.
Competition alone does not guarantee superior returns.
BSP wants employers to play a bigger role in retirement security
The Bangko Sentral ng Pilipinas has been encouraging companies to provide employees with access to voluntary retirement investment programs.
In May 2026, the central bank highlighted the importance of employer participation and the tax advantages available to qualifying businesses.
BSP Deputy Governor Bernadette Romulo-Puyat has also emphasized that retirement preparedness requires shared responsibility among individuals, government and employers.
The central bank’s wider objective is to encourage more Filipinos to build long-term financial resources beyond mandatory pension systems.
This includes making investment products more accessible and improving financial awareness.
BSP initiatives such as the Open Finance for PERA pilot aim to simplify access through secure, consent-based financial data sharing.
These efforts could make retirement investment arrangements easier to open and manage.
However, digital access must be accompanied by appropriate privacy safeguards and clear disclosures.
Because PERA is an investment framework, contributors should understand the differences between deposit accounts, investment funds and other eligible instruments.
Why the Philippines needs stronger retirement savings
Preparing financially for retirement can be difficult for Filipino workers, particularly those supporting children, elderly relatives or other household members.
Housing, food, transportation, education and medical expenses can compete with long-term saving goals.
For some workers, mandatory pension contributions may be the only regular form of retirement preparation.
PERA provides an additional voluntary option.
The goal is to create savings that can help supplement future pension income and other financial resources.
However, the adequacy of retirement savings cannot be measured solely by the existence of a PERA account.
A person with a small account balance may still face a considerable retirement funding gap.
Investors must also account for inflation.
Money saved today may buy fewer goods and services decades later.
This means retirement planning should involve realistic assumptions about future expenses and an investment approach suited to the contributor’s circumstances.
Early investing matters, but there are no guaranteed returns
One advantage of starting retirement investing early is the possibility of earning returns on previously accumulated returns over long periods.
This effect is often called compounding.
Workers who begin saving earlier may have more time to build their investments than those who start close to retirement.
However, compounding does not eliminate the possibility of losses.
PERA products may invest in assets such as bonds, equities and investment funds.
Their returns depend on market movements and the characteristics of each investment.
BPI Wealth’s own PERA investment disclosures explain that certain fund products are not bank deposits and are not insured by the Philippine Deposit Insurance Corporation.
Investment values can fluctuate, and redemption proceeds may be lower than the original amount invested.
Contributors should therefore avoid treating PERA as a guaranteed-income product.
The tax advantages can improve the overall attractiveness of qualifying retirement investments, but they cannot remove market risk.
Can employer-backed PERA help deepen Philippine capital markets?
The retirement savings initiative also has implications beyond individual workers.
The BSP sees broader PERA participation as a way to develop the domestic investment market.
When more Filipinos invest through properly regulated retirement arrangements, additional long-term capital may become available for eligible investment instruments.
A larger investor base could support the development of Philippine bond and equity markets.
The Securities and Exchange Commission has also identified reforms involving PERA and broader participation in domestic capital markets.
WWC ONE MEDIA explored this institutional context in SEC Chair Francis Lim Credits Cesar Virata With Helping Build Modern Philippine Capital Markets.
That report examined the Philippine market’s development and continuing efforts to make investing more accessible.
Another indication of increasing retail participation came from GCash’s October 2026 stock market debut.
As reported by WWC ONE MEDIA in GCash’s Record ₱60.9-Billion IPO Draws BlackRock, Citadel and Global Investors — But the Real Test for Philippine Tech Begins Now, more than 140,000 users participated in the offering through the GCash platform.
The IPO and PERA serve different investment purposes, but both illustrate efforts to bring more individuals into Philippine financial markets.
Greater market participation also increases the importance of investor protection and financial education.
What workers should check before joining corporate PERA
Employees considering a workplace PERA arrangement should review the program’s terms carefully.
Important questions include whether their employer will contribute or match their savings, which investment funds are available, what fees apply and when withdrawals are permitted.
Workers should also confirm how the account will be managed if they change jobs.
The portability of PERA is an important benefit, but administrative procedures may still apply.
A worker’s monthly budget also matters.
Retirement investing should be considered alongside essential expenses, existing debts, emergency savings and other financial responsibilities.
For employers, adopting PERA involves evaluating tax eligibility, contribution policies, administrative arrangements and communication with employees.
The program is designed to encourage long-term saving, but it should not be presented as an automatic solution to every worker’s financial difficulties.
The bigger question: Can BPI change how Filipinos prepare for retirement?
BPI Wealth’s Corporate PERA launch represents a meaningful expansion of workplace-based retirement investment options.
It creates another channel through which employees can access tax-advantaged savings and investment products.
The timing is notable.
Nationwide PERA participation has increased dramatically, reaching 30,055 contributors in June 2026.
At the same time, the BSP is encouraging companies to participate through enhanced tax incentives and financial wellness initiatives.
But several questions remain unanswered.
How many employers will adopt BPI Corporate PERA?
How many employees will enroll and contribute regularly?
Will participating businesses offer matching contributions?
And will workers be able to accumulate enough retirement investments despite rising living expenses?
BPI Wealth has not disclosed a confirmed enrollment target or demonstrated long-term retirement outcomes for its newly launched corporate program in the reports reviewed.
These figures will be important in measuring its eventual success.
BPI Wealth is bringing retirement investing closer to Filipino workers. But the real test is whether more employees can afford to participate consistently—and whether the country’s growing retirement savings system can eventually deliver meaningful financial security beyond the working years.