
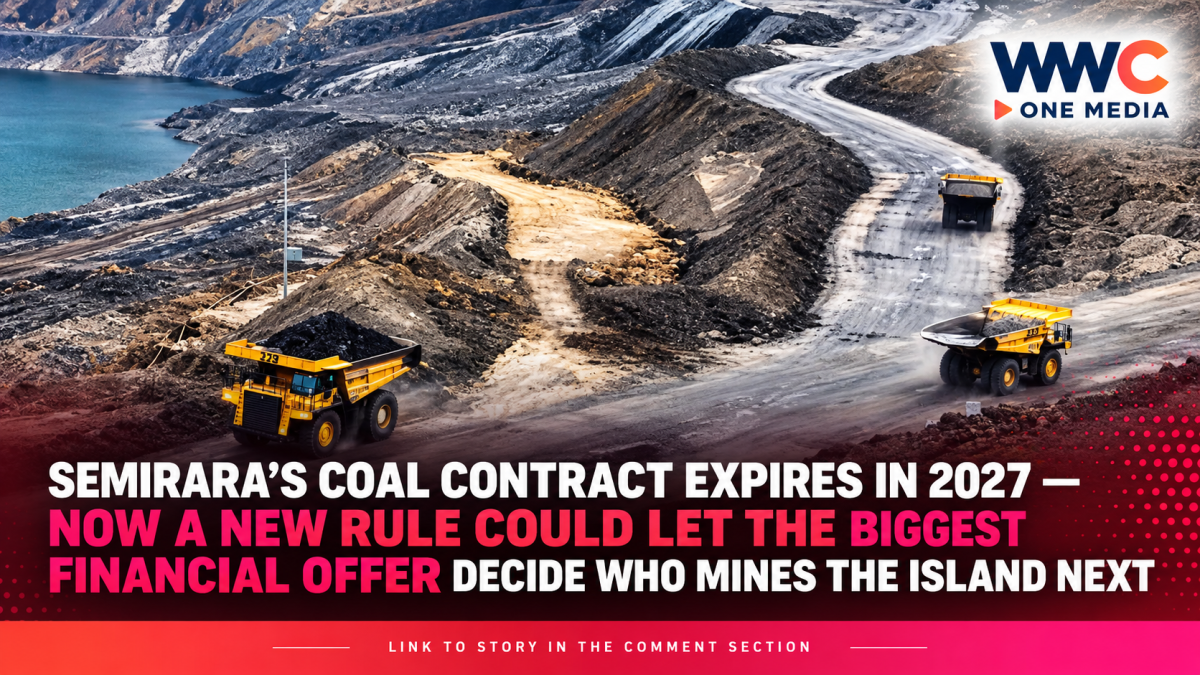
MANILA, Philippines — The company that has mined Semirara Island’s coal for nearly half a century is challenging the government’s attempt to rewrite the rules for what happens when its contract expires next year, turning what began as an energy auction into a much bigger argument over ownership, competition and how much the State should earn from one of the country’s most valuable energy resources.
Semirara Mining and Power Corp. has raised legal, constitutional and operational objections to proposed government rules governing the award of natural-resource contracts, including the new coal operating contract covering its longtime mining area in Antique.
The Consunji-led company’s existing Coal Operating Contract No. 5 expires on July 14, 2027. Rather than simply extending the arrangement, the Department of Energy decided to subject 10 coal blocks on Semirara Island to competitive bidding.
But the original auction has repeatedly stalled while regulators rethink how an already developed—or “brownfield”—resource should be awarded.
The newest proposal could dramatically change the contest.
Instead of determining the winner largely through technical and financial capability to operate the mine, a proposed National Interest Evaluation Framework would first screen bidders and then potentially rank qualified applicants according to which one delivers the greatest economic return to government.
For Semirara, that raises a fundamental question:
Should decades of mining experience and billions of pesos in existing infrastructure give an incumbent operator a decisive advantage—or should another technically qualified company be able to win simply by offering the government more money?
The government originally opened 18 coal blocks
The DOE launched its 2026 Philippine Conventional Energy Contracting Program coal bid round on February 27.
Three predetermined areas covering a combined 18 coal blocks and 18,000 hectares were offered.
Ten blocks covering 10,000 hectares are on Semirara Island in Caluya, Antique.
Three blocks totaling 3,000 hectares are in Amulung and Iguig, Cagayan.
Another five blocks covering 5,000 hectares are in Benito Soliven, Naguilian and Cauayan in Isabela.
The Semirara blocks are by far the most commercially significant because they are not unexplored prospects.
They are part of an established mining operation with decades of geological information, heavy equipment, roads, port facilities, stockyards, mining pits, workers and logistics infrastructure already in place.
SMPC reported around 160 million metric tons of estimated coal reserves on Semirara Island at the end of 2025.
That makes the coming contract fundamentally different from awarding rights over an undeveloped exploration area.
Whoever wins does not merely receive permission to search for coal.
The winner potentially takes over the right to develop the country’s largest existing coal-producing area.
Semirara has operated under the contract since the 1970s
The original Coal Operating Contract No. 5 was awarded in 1977 to a consortium before the rights were subsequently transferred to the company that became SMPC.
The contract originally ran for 35 years.
In 2008, the DOE approved a 15-year extension, bringing the expiration date to July 14, 2027.
The agreement operates under Presidential Decree No. 972, the Coal Development Act, and its amendments.
Under the current economic arrangement, government receives 30% of net proceeds from coal production, while the operator receives the balance under the production-sharing framework.
SMPC had hoped to continue operating beyond 2027.
Instead, DOE opted for competitive bidding.
That decision opened the door to one of the most consequential energy auctions the Philippines has held in years.
Five companies initially showed interest
The contest initially attracted several major industry players.
Companies attending the April pre-bid conference included SMPC, San Miguel Global Power units Limay Power Inc. and Malita Power Inc., TSR/Sta. Clara and DESCO.
Meralco PowerGen had also studied the opportunity but eventually decided not to submit a direct bid.
MGEN president Emmanuel Rubio said in May that his group lacked sufficient time to conduct the due diligence it considered necessary and would instead explore taking a minority position alongside Semirara if SMPC secured the new contract.
Rubio publicly described the incumbent as the “logical winner” because it already possessed the equipment and operating experience at the mine.
That observation highlights one of the government’s biggest problems.
A competitive auction works best when bidders compete from reasonably comparable starting points.
At Semirara, they do not.
One bidder has spent decades operating the mine.
The others would have to understand an enormous brownfield mining system quickly enough to propose how they would operate it safely and economically after July 2027.
Then the government stopped the clock
DOE initially set an April 28 deadline for applications.
That deadline was postponed after bidders sought clarifications and the department began reassessing how the Semirara area should be handled.
Energy Secretary Sharon Garin later said the government needed specific rules for existing operating or brownfield assets rather than treating Semirara like an ordinary undeveloped coal block.
DOE began coordinating with the Department of Environment and Natural Resources and other economic agencies on a revised framework.
By August, the auction had been pushed further back while officials reconsidered issues including government revenue, domestic coal supply and how existing assets would be treated.
The DOE now says it intends to complete its final consultation and finish the auction process before the end of 2026.
But the rules being discussed today differ significantly from what prospective bidders encountered in February.
The first hurdle would still be capability
Under the proposed framework reported by The Philippine Star, bidders would undergo a two-stage evaluation.
The first stage would operate on a pass-or-fail basis.
A bidder would have to demonstrate legal eligibility, technical competence, financial capability, national-security and integrity clearance and a willingness to allocate all or a specified portion of production to the Philippine domestic market.
Those requirements are important because operating a large open-pit coal mine is not simply a matter of offering the highest royalty.
A successful operator must manage mine engineering, geological risks, worker safety, rehabilitation obligations, equipment fleets, product quality, transportation and enormous amounts of earthmoving.
DOE’s February guidelines already required applicants to submit a five-year work program, annual expenditures and detailed plans covering exploration, development, production, safety and rehabilitation.
Only bidders capable of satisfying those standards would proceed.
But what happens afterward is generating much of the new controversy.
Once qualified, money could decide the winner
Under the proposed National Interest Evaluation Framework, the ranking stage could make the financial offer the decisive—or “sole”—ranking factor among bidders that passed the qualification stage.
The framework would seek the offer providing the highest economic benefit to the State.
Financial bids could include higher government shares, royalties, signing bonuses, production bonuses, discovery bonuses and minimum annual payments.
That differs materially from simply asking whether a company has enough capital to operate the mine.
A challenger could theoretically meet the minimum technical requirements and then beat the incumbent by promising significantly larger payments to government.
For the State, the attraction is easy to understand.
Coal belongs to the Republic.
Article XII of the Constitution states that coal, petroleum, minerals and other natural resources are owned by the State, and their development and utilization remain under full government control and supervision.
The government therefore has an interest in obtaining a competitive economic return when granting private companies the right to exploit those resources.
For the operator, however, offering a much larger State share also means less money remains to cover mining costs, investment, rehabilitation, financing and shareholder returns.
Finding the point where government revenue stops being attractive and begins making the mine economically difficult is therefore central to the auction.
The existing 30% government share may no longer be the final benchmark
Under SMPC’s current contract, government takes 30% of net proceeds.
DOE officials previously indicated that this established royalty structure might continue.
But Garin has also argued that a producing brownfield mine could justify better economic terms for government than an unexplored resource because much of the geological uncertainty has already been eliminated.
That logic changes the bidding equation.
A company receiving an unknown coal prospect carries the risk that commercial reserves may never materialize.
A company winning Semirara would take over access to an area where large coal reserves, operating infrastructure and decades of mining history are already established.
The government can therefore argue that the asset is worth more today than when private investment initially carried far greater geological and operational risk.
SMPC, meanwhile, can argue that much of the mine’s current value exists precisely because previous operators spent decades and substantial capital developing it.
Those two perspectives sit at the center of the dispute.
The fight over machinery may be even more important than the royalty
The other major conflict concerns who owns the equipment and infrastructure that make Semirara operational.
DOE instructed SMPC in June to submit a detailed schedule of property, plant, equipment and related asset information and to facilitate physical verification of assets at the mine and power complex.
The department said that information would be made available to participants in the bid round.
DOE has taken the position that certain assets whose costs were recovered by SMPC, as well as material not removed within a defined period after contract termination, could vest in government and become available to a successor operator.
SMPC disputes that interpretation.
The company says cost recovery is a financial accounting mechanism, not a transfer of legal ownership.
It argues that title to its assets remains with the company and that any government reversionary right is conditional, applies only in specified circumstances and is limited to certain assets in the exploration or production area.
That is now before the courts.
Semirara took DOE to court
On July 16, SMPC filed a petition for declaratory relief with Makati Regional Trial Court Branch 141 asking the judiciary to determine the parties’ rights under the existing contract and PD 972.
Among other things, SMPC wants a declaration that DOE cannot compel the disputed asset disclosures during the bid, that ownership presently remains with the company and that cost recovery does not automatically give government title to equipment before the contract expires.
SMPC has also objected to proprietary information potentially being provided to rival bidders.
The company argues that competitors should conduct their own technical studies instead of relying on information produced from SMPC’s decades of investment and operational experience.
No final court ruling establishing SMPC’s interpretation has been reported.
Likewise, DOE’s contrary position has not yet been judicially upheld.
That means the ownership issue remains disputed.
Why asset ownership could determine whether competition is real
The question may sound like a narrow contract argument.
It is not.
Imagine a new company wins the right to mine Semirara in 2027.
If the winner is allowed to use existing excavators, haulage infrastructure, ports, stockyards, roads and other facilities, transitioning from the old operator could potentially be manageable.
If those assets remain SMPC property and are removed or unavailable, the new operator might need to purchase or build replacements before maintaining production.
That could involve massive capital expenditure and significant operational delays.
This partly explains why MGEN concluded Semirara held an obvious operational advantage.
It also explains why asset disclosure matters to rival bidders.
A challenger cannot accurately calculate its financial bid without knowing what infrastructure it would inherit, what it would need to buy and how quickly it could take over production.
So the dispute is not merely about confidentiality.
It goes to the economic feasibility of the auction itself.
Contract uncertainty is already affecting Semirara’s operations
The uncertainty is no longer confined to lawyers and regulators.
SMPC announced in August that it would make 462 mine-site employees redundant after reducing its 2026 coal-production target by more than one-third from the previous year.
The company explicitly linked its operational planning to uncertainty surrounding the new coal contract.
At the end of July, SMPC said it employed 4,045 people, including more than 2,000 workers from host communities.
The company has also reduced planned mining capital expenditure while waiting for greater certainty over whether it will retain the concession.
That response is commercially understandable.
Heavy mining equipment can require enormous investment and have useful lives measured in years.
A company that does not know whether it will possess mining rights after July 2027 has less incentive to commit billions of pesos to equipment it may not be able to use on the site.
This creates the deadline problem facing DOE.
The longer the bidding uncertainty continues, the more difficult long-term mine planning becomes.
Semirara is not just another Philippine coal producer
Continuity matters because SMPC dominates local coal production.
Recent DOE-linked reporting says Semirara accounts for roughly 93.7% of domestic coal output.
The Philippines nevertheless remains heavily dependent on imported coal, particularly from Indonesia, because much of Semirara’s sub-bituminous coal has a lower calorific value than the fuel specifications used by many Philippine power plants.
DOE has even begun studying a national coal-blending facility that could mix local coal with imported fuel so more Philippine power plants can use domestically produced coal.
That gives the Semirara auction a national energy-security dimension.
A botched handover or prolonged production interruption would not eliminate coal supply—the Philippines can import more.
But greater import dependence exposes consumers and generators to international prices, shipping risks and foreign-exchange movements.
That is precisely why DOE says indigenous energy development remains strategically important even as the country expands renewable power.
Coal remains deeply embedded in the power system
The dispute is unfolding while the Philippines simultaneously tries to reduce long-term dependence on coal.
DOE has maintained a moratorium on endorsements for most new greenfield coal-fired power projects since 2020, although already operating and previously committed projects are excluded.
Yet coal remains a major part of existing Philippine generation capacity.
As of June 30, 2026, coal-fired plants accounted for roughly 9,410 megawatts, or about 39.4% of installed power capacity, according to DOE-linked figures.
That creates an energy-policy tension.
The Philippines wants more renewable power and a lower-carbon electricity system.
But it still needs reliable fuel for coal plants that may operate for many years.
The government therefore has two objectives that must coexist:
manage an eventual transition away from excessive coal dependence,
while ensuring the coal supply chain remains stable during that transition.
Semirara sits directly in the middle of those objectives.
The Constitution makes government control clear—but not every detail of the auction
Article XII of the 1987 Constitution says natural resources belong to the State and their exploration, development and utilization must remain under its full control and supervision.
It permits production-sharing and related arrangements with qualified Filipino citizens or corporations that meet constitutional ownership requirements.
That establishes broad government authority.
It does not automatically resolve every argument SMPC has raised about the proposed implementing rules, the treatment of existing contractual rights or the ownership of specific assets.
Those issues involve interpreting the existing Coal Operating Contract, PD 972, subsequent regulations and the limits of administrative rulemaking.
SMPC’s characterization of portions of the draft as legally or constitutionally problematic is therefore its legal position.
It should not be reported as though a court has already struck down the proposed government framework.
Similarly, DOE’s interpretation that certain assets may ultimately revert to the State remains contested.
The government is still rewriting the rules
Energy Secretary Garin said this week that regulators were preparing a final public consultation before releasing the revised terms.
DOE wants to complete the Semirara auction before the end of 2026, several months ahead of COC No. 5’s July 2027 expiration.
That timetable is significant.
Whoever wins needs enough time to prepare for the next contract period.
If SMPC wins, operational continuity could be comparatively straightforward.
If another company wins, regulators and both companies would have to manage one of the most complex mining transitions in recent Philippine history.
Equipment ownership would have to be settled.
Workers would need clarity.
Environmental permits and rehabilitation obligations would have to be coordinated.
Mine planning could require revision.
Supply commitments would have to continue.
And customers would need confidence that coal deliveries would not suddenly stop.
Those concerns are why the quality of the bidding rules matters as much as the speed of the auction.
The highest offer may not automatically be the best outcome
There is an obvious appeal to maximizing government revenue.
Coal belongs to the State, and the public has a legitimate interest in receiving strong economic returns from its extraction.
But natural-resource contracts last for years and involve obligations that extend well beyond an upfront payment.
An aggressive financial bid can become problematic if the winner later cannot maintain investment, environmental rehabilitation, worker safety or economically viable production.
The draft attempts to address that risk by screening technical and financial capability before bids are ranked.
Whether that first-stage screen is demanding enough—and whether a financial offer should then become the sole ranking factor—is exactly the sort of issue consultation is intended to resolve.
DOE has not yet published final terms.
So any suggestion that the concession will definitely go to the highest bidder is premature.
Semirara’s advantage may also be its biggest negotiating problem
SMPC enters the contest with obvious strengths.
It already operates the mine.
It has decades of geological information.
It has equipment.
It has workers.
It has logistics facilities.
And it has experience selling Semirara coal domestically and overseas.
Its own regulatory filings argue that these advantages reduce transition risk and support uninterrupted coal production.
But those same strengths may give government reason to demand better terms.
An established mine with known reserves and operating infrastructure presents less development risk than an unexplored concession.
That could justify a larger government economic return.
So the qualities that make SMPC difficult to replace may also make Semirara Island more valuable in an auction.
The real battle is over how the State values a mine someone else built
That is what makes this dispute much larger than one company asking for another contract.
The government owns the coal.
SMPC says it owns much of the machinery and infrastructure created through decades of private investment.
DOE wants a competitive process that protects energy security and extracts better value for the public.
Potential challengers need enough information to determine whether they can actually operate the site.
And everyone is working against a contract expiration only about 10 months away.
The February auction was supposed to answer a relatively straightforward question:
Who is qualified to operate Semirara after 2027?
The revised rules have introduced a harder one:
Once several companies are qualified, should experience decide—or should the government award the mine to whoever offers the public the biggest economic return?
Semirara Mining is now challenging parts of the framework before those rules are finalized.
DOE is continuing consultations.
The asset-ownership dispute is already in court.
And the clock on Coal Operating Contract No. 5 is still running.
The Philippines’ biggest coal mine has plenty of coal left underground.
What remains uncertain is who will have the right to dig it out after July 2027—and how much the government will demand in return.
Leave a Reply