
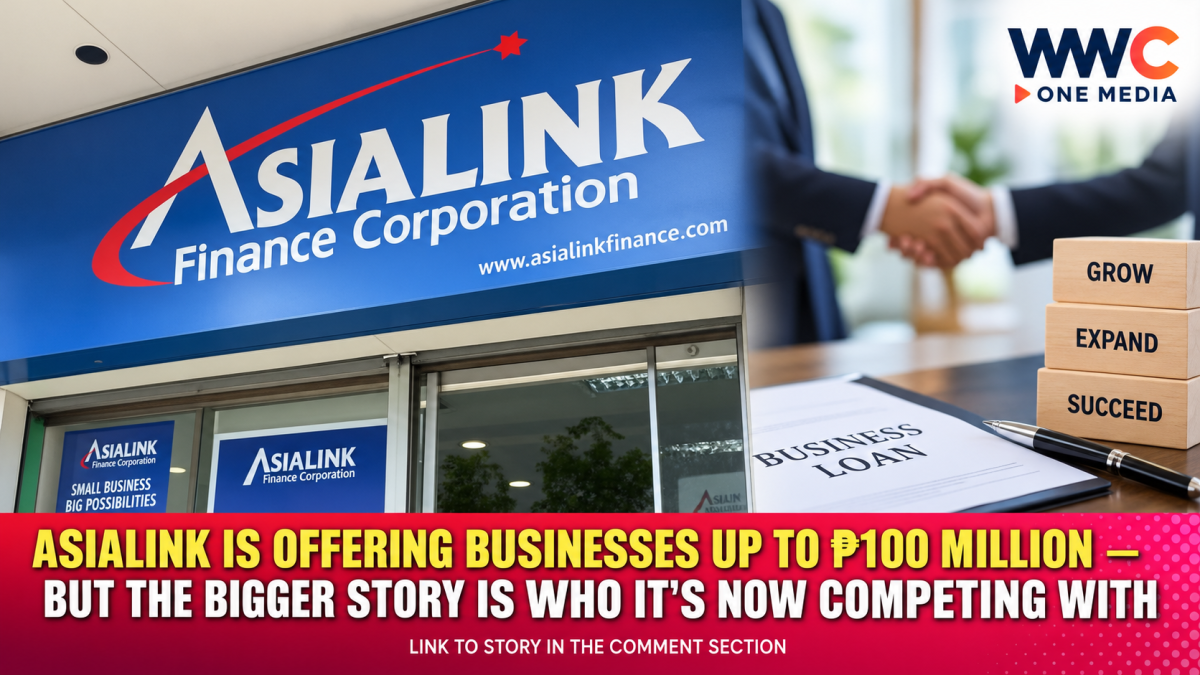
MANILA, Philippines — Asialink Finance Corporation is making a bigger play for established Philippine businesses, rolling out financing of as much as ₱100 million as it moves beyond the smaller loans that built much of its MSME lending business.
The financing company has introduced its GrowBiz Loan, a larger-ticket product aimed at medium-sized enterprises that need substantial capital for expansion, equipment, inventory, additional branches and working capital.
Qualified borrowers may access as much as ₱100 million, with repayment periods of up to seven years and advertised rates starting at 0.75% per month, subject to the borrower’s credit profile, financing requirements and capacity to repay.
That makes GrowBiz a significant step up from Asialink’s existing Real Estate Mortgage Loan, which carries a maximum amount of ₱20 million and a repayment period of up to five years.
In other words, Asialink is no longer focusing only on entrepreneurs looking for relatively modest capital. It is increasingly competing for businesses whose financing needs are beginning to resemble those traditionally handled by commercial banks.
Why Asialink is moving upmarket
Medium-sized companies often face an uncomfortable financing gap.
They may already be too large for traditional microfinance or small-business products, yet still find bank financing difficult because of collateral requirements, documentation, lengthy approval procedures or conservative credit standards.
GrowBiz is designed to occupy that middle ground.
Loans can reportedly be backed by real estate or fleets of vehicles such as cars and trucks, although borrowers will still undergo credit evaluation appropriate for loans of this size. Funds may be used to expand operations, buy vehicles or equipment, increase inventory, open additional locations or strengthen working capital.
Asialink President and CEO Anna Katrina C. Bañez said medium enterprises are often at a stage where they have already proven their business model but need considerably more funding to pursue the next phase of expansion.
The strategy is backed by rapid growth in Asialink’s lending operations.
From 2024 through July 2026, the company said it released roughly ₱27 billion in loans and served more than 53,000 MSME borrowers. Its loan portfolio stood at around ₱26 billion as of July, up 23% year on year, with business and MSME financing accounting for approximately 54% of the portfolio.
Bigger loans are part of a much bigger expansion
GrowBiz is not an isolated product launch.
Asialink has spent the past several years building the funding capacity needed to lend more aggressively to Philippine businesses.
In February 2026, Security Bank Capital arranged ₱4 billion in social corporate notes for the wider Asialink Group, with proceeds earmarked for expanding MSME financing.
A month later, BusinessWorld reported that the group signed another ₱5-billion multi-lender corporate notes facility, arranged with UnionBank, LandBank and EastWest, as it sought to expand its loan portfolio.
International development institutions have also backed the company’s expansion.
The Asian Development Bank previously led a $115-million financing package for Asialink designed to expand SME lending, particularly to women-owned enterprises. ADB estimated the financing gap for Philippine SMEs at roughly ₱67 billion to ₱180 billion, highlighting why nonbank lenders see substantial room to grow.
The International Finance Corporation, the private-sector arm of the World Bank Group, separately announced financing of up to $130 million for Asialink, with at least 60% of the loan proceeds intended for women-owned or women-led MSMEs.
Those deals effectively give Asialink more financial firepower to chase a market that remains underserved despite the continued expansion of Philippine bank lending.
The numbers show why lenders want this market
Small and medium enterprises remain crucial to the Philippine economy, but access to formal credit has long lagged their economic importance.
ADB has pointed out that many SMEs still struggle to obtain bank loans, with women-owned businesses facing even greater barriers.
Bangko Sentral ng Pilipinas data also show the enormous scale of the broader credit market. Philippine banks had about ₱12.78 trillion in net loan portfolios covered by MSME allocation reporting as of June 2026, while eligible financing for medium enterprises stood at roughly ₱325.6 billion.
That leaves considerable room for nonbank financing companies willing to accept different forms of collateral, move faster on approvals or structure products around businesses that do not neatly fit traditional bank lending models.
But bigger loans also mean bigger risks
Moving from smaller MSME loans into financing of as much as ₱100 million changes the risk equation for Asialink.
A single bad loan at the upper end of GrowBiz could equal dozens or even hundreds of smaller loans. Credit underwriting, collateral valuation and portfolio concentration will therefore become increasingly important as the company moves upmarket.
That makes asset quality one of the numbers investors and lenders will be watching closely.
Asialink Group reported ₱50.2 billion in assets under management at the end of June 2026, up 20% year on year, while maintaining a reported non-performing loan ratio of about 2%. MSME borrowers represented around 60% of the group’s assets under management.
The challenge will be maintaining that credit quality while simultaneously issuing larger and longer-term loans.
The bigger picture
GrowBiz signals something more important than the launch of another lending product.
Asialink is attempting to follow its customers up the financing ladder.
A small company that once needed several hundred thousand pesos for inventory could eventually require millions for trucks, machinery, warehouses or new locations. If Asialink can retain those borrowers as they expand rather than losing them to commercial banks, the economics of its lending business could change substantially.
The company already has more than 255 branches nationwide, giving it a physical distribution network that many newer financial-technology lenders lack.
Now it is pairing that network with substantially larger loan tickets.
For Philippine entrepreneurs, that means another financing option between small-business credit and traditional corporate banking.
For Asialink, however, the stakes are considerably higher.
The company has built its name lending to MSMEs. GrowBiz will test whether it can successfully grow alongside them — from financing small entrepreneurs to funding businesses requiring tens of millions of pesos at a time.
Leave a Reply