PASAY CITY, Philippines — Robinsons Land Corporation (RLC) is making a major push to attract Filipino homebuyers, bringing 10 condominium developments to the 2nd National Housing Expo 2026 with exclusive discounts, flexible payment schemes and access to expanded government-backed housing financing.
Through its residential division, RLC Residences, the Gokongwei-backed property developer joined the October 19–20 housing fair at the SMX Convention Center Manila, where prospective buyers could explore properties across Metro Manila and nearby Rizal.
The initiative comes as Pag-IBIG Fund increases its maximum individual housing loan from ₱6 million to ₱10 million, while offering promotional annual interest rates starting at 4.5% for eligible borrowers.
Qualified married couples who are both Pag-IBIG members may also combine their borrowing capacity for financing of up to ₱20 million, subject to the fund’s lending requirements.
But while the expanded loan limits give buyers more property options, a bigger question remains:
Will lower initial interest rates and developer discounts finally make condominium ownership affordable — or will high property prices and long-term payments continue to keep Filipinos out of the market?
RLC Residences Showcases 10 Condominium Developments
RLC Residences presented a portfolio of completed and ongoing developments in key urban and suburban locations.
The participating properties include:
- Gateway Regency Studios — Mandaluyong City: A condominium development offering access to Metro Manila’s central business districts.
- Aurora Escalades — Quezon City: A residential project positioned for buyers seeking access to the city’s commercial and transportation corridors.
- SYNC S-Tower — Pasig City: Part of RLC Residences’ SYNC development, targeting buyers interested in urban living.
- Cirrus — Pasig City: A residential property offering access to the Ortigas and C5 commercial corridors.
- Acacia Escalades Tower B — Pasig City: A mid-rise development providing another option within the eastern Metro Manila housing market.
- Woodsville Crest Building Oak — Parañaque City: Part of RLC’s residential development near the Ninoy Aquino International Airport corridor.
- The Radiance Manila Bay South Tower — Pasay City: A residential development near Manila Bay and major commercial destinations.
- Sierra Valley Gardens Building 1 — Cainta, Rizal: Located within RLC’s Sierra Valley mixed-use estate.
- The Sapphire Bloc East Tower — Ortigas Center: A high-rise residential development in one of Metro Manila’s established business districts.
- Chimes Greenhills — San Juan City: A condominium development located near the Greenhills commercial area.
The lineup gives buyers opportunities to compare properties across different locations and residential categories.
However, participation in the expo does not mean every unit in these developments is automatically eligible for Pag-IBIG financing.
Specific units must satisfy the fund’s applicable requirements and receive the necessary evaluation.
Special Discounts and Flexible Payment Arrangements
RLC Residences promoted exclusive discounts and special payment arrangements during the two-day housing event.
The company said its representatives would provide information about participating developments, unit availability, promotional offers and financing requirements.
However, the developer did not publicly disclose a uniform discount percentage or fixed peso value applicable to all 10 projects in its pre-expo announcement.
Actual incentives could differ depending on the property, unit, payment structure and booking conditions.
That is an important distinction for buyers.
A promotional offer available on one condominium should not be assumed to apply to every RLC Residences development.
Likewise, a lower initial payment does not necessarily mean a lower total acquisition cost.
Prospective buyers should assess the full contract price, reservation fees, downpayment requirements, financing charges and other expenses before committing to a property.
Pag-IBIG Raises Housing Loan Ceiling to ₱10 Million
One of the most significant developments surrounding the expo is Pag-IBIG Fund’s expanded housing financing program.
The government-backed fund increased the maximum individual housing loan amount from ₱6 million to ₱10 million under initiatives supporting the Expanded Pambansang Pabahay Para sa Pilipino, or Expanded 4PH, Program.
The increase allows eligible members to seek financing for a wider range of residential properties.
For qualified couples, combined borrowing capacity may reach ₱20 million if both spouses meet the necessary requirements and receive approval.
But the higher ceiling is not an automatic entitlement.
Actual loan approval depends on factors including creditworthiness, income, repayment capacity, membership qualifications, property appraisal and applicable lending rules.
A borrower does not necessarily qualify for a ₱10-million loan simply because the new maximum amount is available.
The expansion is intended to provide more financing flexibility, but responsible borrowing remains essential.
Pag-IBIG Offers Promotional Interest Rates of 4.5% and 5.75%
The financing arrangements include promotional interest rates intended to support eligible homebuyers.
For qualifying housing loans above the applicable socialized housing ceiling and up to ₱4.9 million, the annual rate is 4.5%.
Eligible loans above ₱4.9 million and up to ₱10 million may qualify for a 5.75% annual rate.
Applications under the promotional program are covered by the announced period ending December 31, 2026.
Both rates are fixed for the first three years of the loan.
This means borrowers should not assume that the same rate will remain unchanged throughout a 15-, 20- or 30-year loan term.
After the initial fixed-rate period, the loan may be repriced according to Pag-IBIG’s applicable terms.
The actual monthly payment could therefore change in the future.
For buyers considering long-term financing, understanding this repricing risk is just as important as comparing the advertised introductory rate.
How Much Could a Pag-IBIG Housing Loan Cost Each Month?
To illustrate the financing considerations, a hypothetical ₱4-million housing loan at an annual interest rate of 4.5%, amortized over 30 years, would require a monthly principal-and-interest payment of approximately ₱20,267.
Meanwhile, a ₱6-million loan at an annual rate of 5.75%, amortized over the same period, would require approximately ₱35,017 a month.
These examples assume conventional monthly amortization and unchanged interest rates purely for illustration.
They are not official Pag-IBIG loan quotations.
Actual payments will depend on loan approval, repayment term, interest repricing, insurance and applicable charges.
For condominium buyers, association dues, property taxes, maintenance expenses, utilities and other ownership costs must also be included in the household budget.
The examples show why access to a larger loan does not automatically translate into affordable homeownership.
Borrowers still need sufficient income to sustain the financial commitment.
Robinsons Land Signs Major Partnership With Pag-IBIG Fund
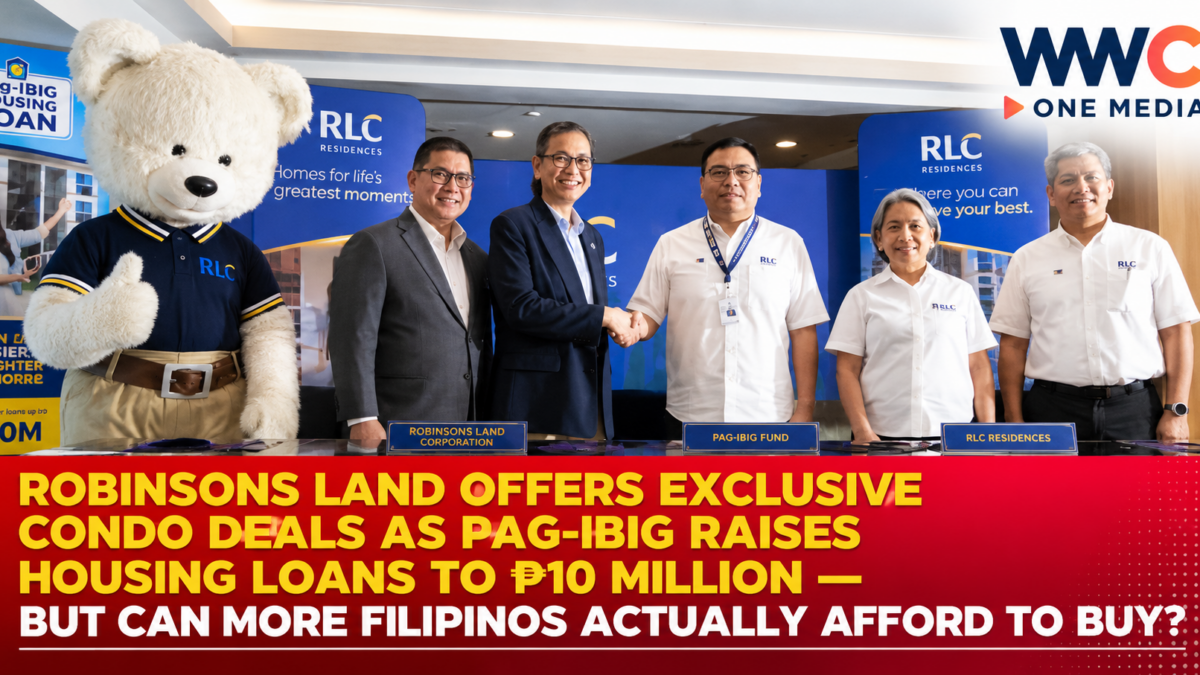
The housing expo came shortly after a new partnership between Robinsons Land Corporation and Pag-IBIG Fund.
On October 5, 2026, the two organizations signed a memorandum of understanding to expand access to housing financing for qualified members.
The agreement creates a pathway for more RLC Residences projects to undergo the necessary accreditation and eligibility procedures for Pag-IBIG-backed housing loans.
The signing involved Robinsons Land President and CEO Mybelle V. Aragon-GoBio, Pag-IBIG Fund CEO Marilene C. Acosta and senior representatives of the developer and government housing agencies.
Aragon-GoBio emphasized the importance of narrowing the gap between the desire to own a home and a household’s actual financial capacity.
The partnership seeks to connect residential developments in established locations with financing arrangements that can help qualifying buyers manage their payments.
However, the memorandum of understanding does not establish that every RLC project has already secured final accreditation.
Actual eligibility remains subject to the fund’s assessment and requirements.
National Housing Expo Brings Together More Than 80 Developers
The RLC initiative forms part of a much larger government-led housing campaign.
According to The Philippine Star’s October 20 report, the 2nd National Housing Expo brought together more than 80 partner property developers offering over 50,000 ready-for-occupancy homes, including condominium units.
The event was organized by the Department of Human Settlements and Urban Development and Pag-IBIG Fund.
President Ferdinand Marcos Jr. attended the opening ceremony on October 19 alongside senior housing officials.
The government expects more than 40,000 home seekers during the two-day event, compared with approximately 20,000 visitors recorded the previous year.
That expectation reflects the scale of interest anticipated by organizers, but it is not a final attendance figure.
The expo also featured special pricing, financing assistance and eligible Pag-IBIG acquired properties offered at discounts of up to 30%.
Those acquired-property discounts are separate from RLC Residences’ promotions and should not be presented as discounts automatically offered on RLC condominiums.
Developers Face Pressure to Turn Buyer Interest Into Actual Sales
The housing expo comes at a challenging time for Metro Manila’s condominium market.
Separate industry reporting has highlighted elevated unsold inventory and buyers’ increasing preference for flexible financing arrangements.
While interest in condominium living remains, buyers are becoming more selective about price, location, financing and long-term value.
For developers, promotional discounts and government-backed financing may help attract customers who have postponed purchases.
For prospective homeowners, additional supply can create opportunities to compare properties and negotiate payment arrangements.
But the existence of unsold condominium inventory does not automatically mean every project is overpriced or unsuitable for buyers.
Property values and demand vary significantly depending on location, developer, project quality and available units.
For RLC Residences, participation in the housing expo creates an opportunity to reach prospective customers who may be ready to purchase but require more suitable financing options.
The company’s success will depend on whether those inquiries become completed and sustainable property sales.
RLC Residences Expands Its Homeownership Strategy
The October housing expo is part of a wider strategy to reach different groups of Filipino property buyers.
Earlier in 2026, RLC Residences partnered with Bahaideals.com to help overseas Filipinos in the United States and Canada explore residential property investments in the Philippines.
The company has also expanded its international marketing arrangements, including collaboration with property professionals in Singapore.
Domestically, the developer continues advancing projects such as MIRA in Quezon City and Sierra Valley Gardens in Cainta, Rizal.
These initiatives demonstrate an effort to reach potential homeowners through a combination of residential development, digital channels, overseas marketing and financing partnerships.
The Pag-IBIG collaboration adds another option for qualifying buyers who prefer government-backed housing loans.
However, buyers should still assess individual project locations, completion schedules, contractual obligations and financing terms.
What Buyers Should Check Before Signing a Condo Contract
The combination of promotional discounts and expanded loan availability may make purchasing a condominium more attractive.
But homeownership involves a long-term financial obligation that should not be decided based only on a temporary sale.
Prospective buyers should request a written breakdown of the total selling price, reservation fee, downpayment schedule, loan amount and monthly amortization.
They should also verify whether the selected unit is eligible for Pag-IBIG financing and whether the borrower meets the fund’s qualification requirements.
Other essential considerations include turnover dates, construction progress, association dues, property taxes and the possibility of future interest-rate adjustments.
Buyers should be particularly careful when a promotional payment plan appears affordable during the initial months but requires a much larger mortgage payment later.
The most important question is whether the total cost remains manageable after the introductory offer ends.
The Bigger Question: Can Cheaper Financing Make Homeownership Truly Affordable?
Robinsons Land’s participation in the National Housing Expo provides Filipino buyers with more opportunities to explore condominium properties and financing arrangements.
The increase in Pag-IBIG’s maximum loan ceiling to ₱10 million is a significant expansion of housing credit availability.
Promotional rates of 4.5% and 5.75% could also improve initial payment affordability for eligible applicants.
But wider access to credit does not automatically solve the country’s housing affordability challenges.
Home prices, household income, interest-rate changes, construction costs and ongoing ownership expenses remain important barriers.
For developers, success will depend on offering properties that customers can realistically finance.
For government housing agencies, the challenge is ensuring that expanded borrowing opportunities do not encourage households to take on unsustainable debt.
RLC Residences is offering special condominium deals across 10 developments as Pag-IBIG expands its housing loans to ₱10 million. But the real test is whether lower initial interest rates and flexible payment schemes can help more Filipino families become homeowners without creating financial burdens they cannot sustain.