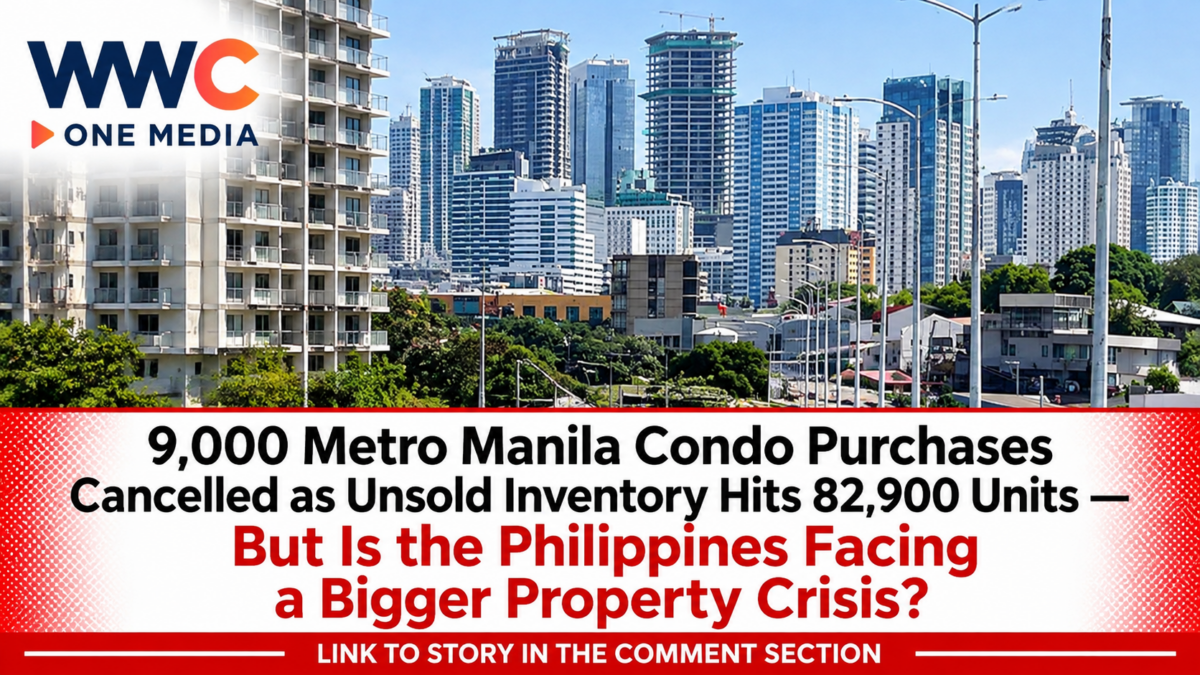
MANILA, PHILIPPINES — November 8, 2026 — Metro Manila’s condominium market is facing renewed scrutiny after property consultants reported approximately 9,000 cancelled condominium purchases in the first nine months of 2026, raising concerns about homebuyer affordability, mounting unsold inventory and the sustainability of long-term payment schemes.
But one of the country’s major real estate brokerage organizations is warning against a premature conclusion that thousands of Filipinos have permanently abandoned their dream of owning a home.
The Association of Real Estate Brokers of the Philippines (ABREP) Movement, led by president Anthony Leuterio, is demanding greater transparency from property-market analysts over how cancellations are counted and what happens to units after buyers withdraw from purchase agreements.
The concern comes as Metro Manila struggles with a substantial condominium inventory overhang.
According to figures cited by GMA Integrated News, Leechiu Property Consultants recorded approximately 82,900 unsold condominium units as of its midyear market assessment.
Meanwhile, Colliers Philippines has identified a growing number of buyers unable to complete purchases as their initial developer-payment arrangements end and much larger bank-financing obligations begin.
For some prospective homeowners, monthly payments that initially stood at around ₱10,000 to ₱12,000 can increase to ₱40,000 to ₱50,000, depending on the purchase price, financing arrangement and loan terms.
Yet brokers argue that not every cancellation reflects permanent financial distress.
Some buyers encounter temporary documentation problems, employment changes or financing delays. Others may eventually secure loans through alternative banks.
The bigger question is whether Metro Manila is experiencing a temporary financing adjustment—or whether a prolonged affordability problem could leave thousands more condominium units waiting for buyers.
Brokers Demand Answers Over 9,000 Cancelled Condo Purchases
In its November 8 report, GMA News highlighted concerns raised by ABREP regarding the widely cited cancellation figures.
The brokerage group questioned whether the reported 9,000 cancellations accurately reflect the condition of Metro Manila’s residential property market without a fuller breakdown of the underlying transactions.
Leuterio called for greater disclosure of the data’s methodology, coverage and classification.
The figure was attributed to Colliers Philippines, which reported approximately 9,000 condominium buyer cancellations between January and September 2026.
Of those transactions, approximately 5,200 involved units still under construction, while 3,800 involved ready-for-occupancy properties.
But ABREP warned that the total could be misleading if every cancelled purchase were interpreted as a permanently unsold property.
Some units may have been successfully resold.
Some cancellations may be attributable to financing paperwork or changes in a buyer’s circumstances rather than an inability to afford housing.
Others may represent more serious affordability difficulties.
The association wants these categories reported separately.
Its central argument is that a cancelled contract is not necessarily the same as a permanently lost sale.
That distinction matters when evaluating the financial outlook for developers, banks and the wider property industry.
The Condo Payment Shock: From ₱12,000 to ₱50,000 a Month
One of the biggest concerns involves the difference between introductory condominium payments and the mortgage obligations buyers face when their units are ready for turnover.
Many preselling condominium projects allow buyers to pay part of the purchase price through relatively small monthly installments over several years.
For example, a developer may structure an arrangement that allows a purchaser to pay an initial portion of a property’s price over five years.
Monthly installments under such arrangements may be around ₱10,000 to ₱12,000.
The difficulty can emerge when the remaining balance becomes due.
Buyers may need to secure a bank housing loan to complete the transaction.
Depending on the loan amount, interest rate and repayment period, monthly payments can rise substantially.
Colliers Research Director Joey Roi Bondoc explained that some buyers face obligations of approximately ₱40,000 to ₱50,000 after transitioning to bank financing.
That increase can be difficult for households that originally budgeted around much smaller monthly payments.
Some buyers discover that their income does not satisfy the bank’s lending requirements.
Others qualify for financing but decide that the resulting monthly obligation is too expensive.
The challenge is not necessarily that the initial payment terms were improper.
It is that buyers may underestimate the full financing commitment needed to complete the purchase.
Why Loan Rejections Do Not Always Mean Buyers Cannot Afford a Home
ABREP argues that financing problems deserve closer examination.
Leuterio said banks may reject or delay loan applications for reasons unrelated to a buyer’s long-term financial capacity.
These can include incomplete documents, changes in employment status, temporary job losses or difficulty verifying income earned overseas.
This is particularly relevant to overseas Filipino workers and self-employed individuals whose income documentation may differ from that of salaried employees.
A prospective buyer might initially fail to satisfy the requirements of one bank but later secure approval from another financial institution.
Other applicants may qualify after updating their records or addressing outstanding documentation issues.
That is why Leuterio wants property developers and brokers to evaluate whether affected customers received sufficient assistance before their transactions were cancelled.
The association argues that buyers should not automatically be blamed for financing failures.
But the same principle applies to banks and developers.
A loan rejection does not necessarily establish that a financial institution acted unfairly.
Likewise, a cancelled sale does not automatically mean the property was mispriced or that the developer made a misleading offer.
Each case needs to be examined according to its contract terms and financial circumstances.
Metro Manila’s Unsold Condo Inventory Remains a Major Challenge
The debate is taking place against a significant supply overhang.
According to Leechiu Property Consultants figures reported by GMA News, Metro Manila’s unsold condominium inventory reached approximately 82,900 units during the midyear reporting period.
Colliers, using its own research coverage and methodology, has separately estimated around 80,000 unsold units.
The difference between these figures should not be treated as a contradiction without examining the firms’ respective coverage and measurement periods.
More importantly, unsold condominium inventory does not mean every unit is a completed, vacant home.
The inventory may include units that are still under construction or being marketed before completion.
Colliers has separately identified tens of thousands of ready-for-occupancy units.
That distinction is essential when evaluating the market’s physical vacancy and potential pressure on rental prices.
As previously examined by WWC ONE MEDIA, Ayala Land is prioritizing completion and turnover of existing residential developments amid the broader property-market slowdown.
Related WWC ONE MEDIA coverage: Ayala Land Starts Turning Over Gardencourt in Taguig — But It’s Doing So Into an 80,000-Unit Condo Glut
The report illustrates how major developers are adapting to a market where delivering previously sold homes and reducing inventory can be more important than announcing additional towers.
Why Pasig and Mid-Income Condominiums Are Under Pressure
According to Colliers reporting, Pasig accounted for a substantial concentration of cancelled condominium purchases during the first nine months of 2026.
The difficulties were especially visible among mid-income developments.
Colliers has identified renewed cancellation pressure in segments involving properties priced from approximately ₱3.6 million to ₱12 million.
For many households, these prices require long-term mortgage financing.
Even when a buyer can afford the initial down payment, bank-loan approval depends on income, existing financial obligations, credit history and other lending requirements.
A change in employment or household expenses during the preselling period can alter the buyer’s ability to complete the purchase.
This creates an important vulnerability in condominium sales.
A reservation or preselling contract does not always become a completed turnover supported by sustainable financing.
Developers therefore face the challenge of assessing buyer capacity earlier in the sales process.
But the pressure is not uniform across Metro Manila.
Luxury developments, more affordable units and projects near major employment centers can experience different demand conditions.
The reported cancellations should not be interpreted as proof that every condominium in Pasig or other Metro Manila cities is financially distressed.
Brokers Warn Against Treating Every Cancellation as a Permanent Loss
ABREP’s most important warning concerns the way cancellation statistics are interpreted.
Consider a hypothetical developer that records 200 cancelled transactions.
If 150 of those units are subsequently resold, the company still has 200 cancellations in its historical records.
But only 50 of the affected units remain without replacement buyers at that point.
Those are very different measures.
The first describes purchase cancellations over a period.
The second describes the remaining unsold inventory from that group.
Leuterio argues that market reporting should distinguish among initial cancellations, confirmed loan-related withdrawals, successful resales and properties still available for purchase.
Without those details, consumers could wrongly conclude that every cancellation permanently increases unsold housing supply.
Investors might also misinterpret the financial consequences for developers.
The call for transparency does not mean that Colliers’ reported figures are necessarily incorrect.
Rather, it means that additional information is needed to determine precisely what the numbers reveal about the property market.
Rental Prices Become Another Source of Concern
The November 8 GMA report also highlighted ABREP’s response to forecasts of weaker condominium rental demand in Metro Manila.
The group cautioned property owners against automatically assuming that substantial rent cuts are inevitable.
Leuterio emphasized that rental performance depends on more than the advertised monthly rate.
Location, marketing, tenant demand, property condition and professional management can all affect occupancy.
Landlords with poorly maintained units or limited marketing may struggle to secure tenants even when their rents appear competitive.
Conversely, properties located near transport connections, employment centers and established communities may attract more consistent demand.
Nevertheless, elevated vacancies can create real pressure on rental yields.
Owners competing for a limited pool of tenants may need to offer more attractive lease terms.
The appropriate strategy depends on the building, neighborhood, unit characteristics and local supply.
A Metro Manila-wide average should not be treated as a guaranteed forecast for every individual condominium.
S&P Global Warns Housing Recovery Remains Difficult
The wider residential-market slowdown has also attracted attention from international credit analysts.
According to GMA News, S&P Global Ratings identified excess condominium supply, rising costs and expensive borrowing as continuing challenges for Philippine homebuyers.
High mortgage expenses can discourage purchases even when developers offer discounts.
Households may be reluctant to commit to long-term debt when economic conditions and future expenses remain uncertain.
Developers, meanwhile, must manage construction obligations, financing costs and unsold property inventory.
S&P has indicated that recovery will depend partly on an improvement in broader economic pressures and households’ purchasing capacity.
That means the housing market’s outlook cannot be determined solely by the number of units offered for sale.
Interest rates, wages, employment and confidence also matter.
Even lower property prices may not produce a strong recovery if prospective buyers cannot obtain affordable financing.
Developers Respond With Discounts, Longer Payments and Housing Loans
Major Philippine property companies are adjusting their sales strategies to attract buyers.
Some are offering extended payment terms, discounted units, flexible down payments and additional property features.
Others are working with financial institutions and government-backed housing programs to help customers secure funding.
Megaworld, for example, has promoted selected condominium packages and highlighted access to Pag-IBIG financing for qualified buyers.
As WWC ONE MEDIA previously reported, the company unveiled promotional upgrades and financing options during the October National Housing Expo.
Related WWC ONE MEDIA coverage: Megaworld Offers Free Condo Upgrades and Pag-IBIG Loans Up to ₱10 Million — But a Bigger Housing Affordability Challenge Remains
Such arrangements may improve accessibility for qualified buyers.
However, the maximum advertised loan amount does not mean every applicant qualifies for that amount.
Loan approval, repayment terms and eligibility requirements still apply.
Buyers also need to evaluate the full cost of ownership, including association dues, taxes, insurance and future maintenance.
A promotional discount is valuable only if the property remains affordable after the initial payment period.
Robinsons Land and Other Developers Pursue More Flexible Financing
The market adjustment is visible across several major developers.
Robinsons Land has also promoted condominium offers linked to the expanded housing-financing options available through Pag-IBIG.
The strategy reflects an effort to convert buyer interest into completed and financially sustainable purchases.
As covered by WWC ONE MEDIA, the company’s promotional campaign was presented against the broader challenge of affordability in Philippine housing.
Related WWC ONE MEDIA coverage: Robinsons Land Offers Exclusive Condo Deals as Pag-IBIG Raises Housing Loans to ₱10 Million — But Can More Filipinos Actually Afford to Buy?
Financing flexibility may reduce barriers for some buyers.
But developers also need to ensure that customers understand their obligations once promotional terms expire.
The industry faces growing pressure to match housing products with realistic household budgets.
That includes avoiding situations in which buyers commit to a property based mainly on an attractive introductory monthly payment.
Eton’s Bank Partnerships Highlight the Importance of Loan Readiness
The need for more effective financing assistance is also influencing developers’ sales operations.
Lucio Tan’s Eton Properties has highlighted the increasing role of bank financing in its recent transactions.
The company has been strengthening relationships with financial institutions to improve access to housing loans.
As WWC ONE MEDIA previously reported, bank financing has become an increasingly important part of Eton’s property-sales strategy.
Related WWC ONE MEDIA coverage: Lucio Tan’s Eton Says Bank Financing Now Drives Over 10% of Recent Property Sales — But Can Kyle Tan Beat the Philippines’ Housing Slowdown?
The development illustrates why early financing assessments can matter.
Buyers who understand their likely mortgage eligibility before making a long-term commitment may be better prepared for the eventual turnover process.
But prequalification should not be confused with guaranteed loan approval.
Final financing still depends on the lender’s requirements and the buyer’s financial circumstances at the time of application.
What Filipino Condo Buyers Should Check Before Signing a Contract
For prospective condominium owners, the reported cancellations offer an important financial lesson.
A manageable reservation payment or introductory installment does not necessarily mean the full purchase is affordable.
Before signing, buyers should understand the total contract price, the remaining balance at turnover and the expected financing arrangement.
They should also review the loan term, interest-rate structure and possible changes to monthly payments.
If the planned purchase depends on bank financing several years in the future, buyers need to consider what would happen if their income changes or the bank does not approve the requested loan.
Contracts should also be reviewed carefully for provisions involving cancellation, refunds, penalties and payment deadlines.
The Maceda Law, or Republic Act No. 6552, provides specified protections to qualifying buyers of real estate on installment, but eligibility and refund rights depend on the law’s requirements and the actual transaction.
Buyers should not assume they are automatically entitled to a full refund if they cancel.
Understanding these terms can reduce the risk of entering commitments that become difficult to complete.
Could Metro Manila’s Property Slowdown Last Into 2027?
The condominium market’s recovery depends on several interconnected factors.
Developers need to reduce existing inventory while avoiding excessive new supply.
Buyers need access to financing that aligns with their income.
Banks must maintain responsible lending standards.
And the broader economy needs to support stable employment and purchasing power.
Some analysts believe the residential sector may require additional time to absorb its substantial inventory.
But the market’s future remains uncertain.
Different research firms use different measures of condominium supply, buyer take-up, vacancies and completed sales.
Their findings should be compared with attention to reporting periods and methodologies.
Lower interest rates could improve affordability, but the effects would depend on how quickly mortgage lenders adjust their financing offers.
Developers could also reduce unsold inventory through targeted promotions or by changing the timing of new project launches.
None of those possibilities guarantees an immediate rebound.
The most reliable indicators will be completed purchases, successful turnovers, actual resale activity and sustainable demand.
The Bigger Picture: Is Metro Manila Facing a Condo Crisis or an Affordability Reset?
The reported cancellation of 9,000 condominium purchases has become a major warning sign for Metro Manila’s housing market.
Thousands of buyers are encountering difficulty as introductory payment arrangements end and much larger mortgage obligations begin.
At the same time, the capital region continues to carry substantial unsold condominium inventory.
Those conditions create genuine challenges for developers, lenders, brokers and prospective homeowners.
But ABREP’s warning is equally important.
Not every cancellation is a permanent loss.
Not every unsuccessful loan application means a buyer is incapable of purchasing a property.
And not every unsold unit represents a completed home sitting empty.
More detailed data is needed to distinguish temporary financing difficulties from lasting weakness in housing demand.
For developers, the challenge is to offer homes and financing arrangements that match buyers’ long-term financial capacity.
For prospective homeowners, the priority is understanding the complete cost of ownership rather than focusing only on attractive introductory payments.
And for regulators and industry analysts, transparent and consistent information will be essential to maintaining confidence in the market.
Metro Manila’s condominium industry is facing a difficult affordability test, but the scale of its underlying problems cannot be determined from cancellations alone.
As thousands of buyers reconsider their purchases and developers work to sell existing inventory, the question now is whether better financing and greater transparency can stabilize the market—or whether another wave of cancelled contracts will place even more pressure on Philippine real estate.