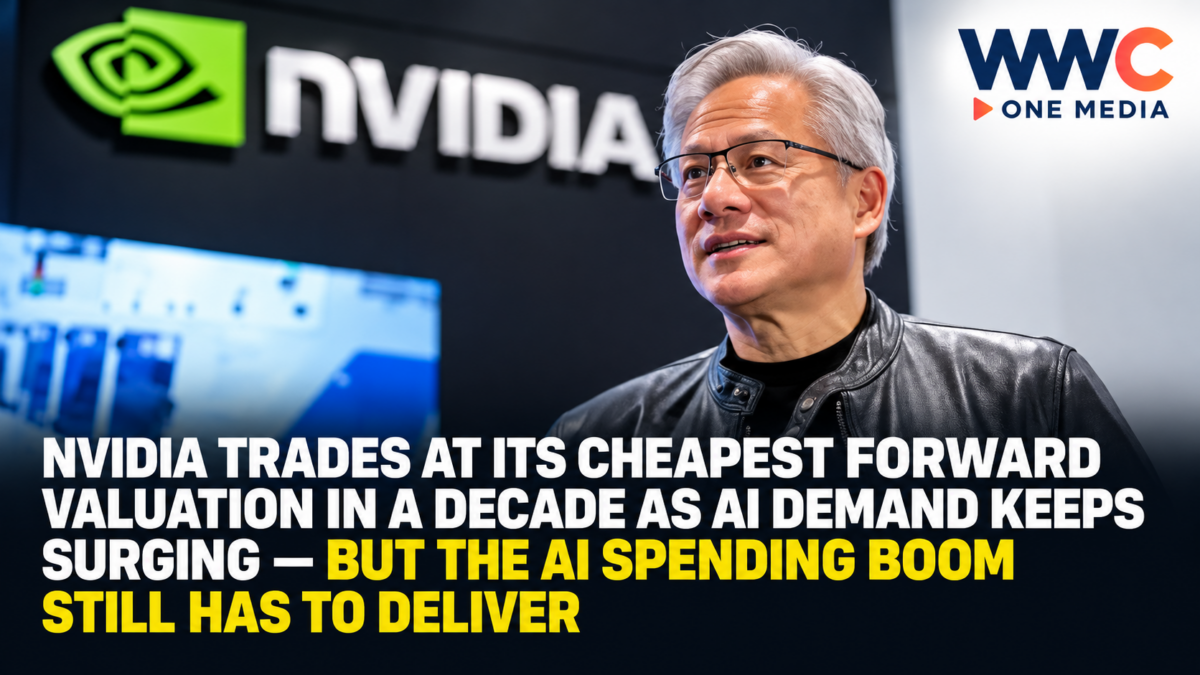
NEW YORK — Nvidia has become the world’s dominant supplier of artificial-intelligence computing hardware, doubled revenue again in its latest quarter and is forecasting another huge growth year — yet one closely watched valuation measure now makes the stock look cheaper than it has in more than a decade.
That apparent contradiction is why Hightower Advisors chief investment strategist Stephanie Link argues Nvidia is a:
“best-in-breed stock on sale.”
Nvidia shares closed October 2 at around:
$233.95
after gaining approximately:
1.3%
during the session.
Yet despite the company’s enormous growth, Nvidia recently traded at only about:
16.5 to 16.7 times forward earnings.
According to LSEG data, that is its lowest forward valuation multiple since:
January 2015.
For perspective, Nvidia’s long-term average forward earnings multiple has been closer to:
30 times.
That does not automatically make the stock cheap.
But it creates a striking situation:
Nvidia’s profits are rising so quickly that earnings expectations have increased faster than the share price.
NVIDIA’S STOCK HAS RISEN — BUT EARNINGS HAVE RISEN MUCH FASTER
Nvidia shares have gained roughly:
20% to 25% in 2026.
That would normally be considered strong performance.
But several semiconductor rivals have done substantially better.
AMD has more than doubled.
Intel has more than tripled.
That relative underperformance has helped compress Nvidia’s valuation.
At the same time, analysts have continued raising their earnings forecasts.
The result is a company whose stock price is higher—but whose valuation relative to expected profits is much lower.
THAT IS WHAT STEPHANIE LINK MEANS BY “ON SALE”
Link’s thesis is not that Nvidia’s share price has collapsed.
It has not.
The argument is that Nvidia’s business performance has grown much faster than its valuation.
The stock’s forward price-to-earnings multiple has fallen from levels above:
25 times
toward approximately:
16.5 times.
That is unusual for a company still delivering triple-digit growth in its largest business.
Link described Nvidia as:
“best in breed”
because of its leadership across:
AI GPUs
Networking
Software
Accelerated computing
and increasingly
Complete AI data-center systems.
NVIDIA JUST REPORTED $96.2 BILLION IN QUARTERLY REVENUE
Nvidia’s latest financial results remain extraordinary.
For the second quarter of fiscal 2027, revenue reached:
$96.22 billion.
That was up:
106% year over year
and
18% from the previous quarter.
Few companies anywhere near Nvidia’s size have ever sustained that level of growth.
The main driver was artificial intelligence.
DATA CENTER REVENUE HIT $89 BILLION
Nvidia’s Data Center business generated:
$89 billion
in the quarter.
That represented:
117% year-over-year growth.
Data Center alone now accounts for more than:
90% of Nvidia’s total revenue.
That demonstrates just how completely Nvidia has transformed.
It was once best known as a gaming graphics-chip company.
Today it is primarily an AI infrastructure provider.
BLACKWELL REMAINS THE ENGINE
Nvidia’s current-generation Blackwell architecture continues to drive most shipments.
Blackwell systems are being deployed by:
Amazon Web Services
Microsoft Azure
Google Cloud
Oracle
Meta
AI startups
and governments building sovereign AI infrastructure.
Blackwell was designed to accelerate enormous generative-AI models.
Nvidia says demand continues to exceed available supply.
That means one of Nvidia’s biggest current problems is not finding buyers.
It is manufacturing enough hardware.
SUPPLY IS STILL CONSTRAINING GROWTH
Nvidia expects supply limitations to continue through at least:
the end of fiscal 2028.
That is remarkable.
Companies usually worry about producing more than customers want.
Nvidia is dealing with the opposite problem.
Demand for AI computing is growing faster than its manufacturing ecosystem can supply:
GPUs
Memory
Networking equipment
Advanced packaging
and
Complete rack systems.
That shortage is one reason customers are placing orders years in advance.
VERA RUBIN IS ALREADY ENTERING PRODUCTION
The next growth engine is Nvidia’s:
Vera Rubin
platform.
Rubin succeeds Blackwell.
Nvidia says Vera Rubin has already entered production and systems are running with partners including:
Google Cloud
Microsoft Azure
Oracle Cloud
CoreWeave
and
Nebius.
Management expects Rubin to represent around:
20% of Data Center revenue
in the current quarter.
That is an unusually rapid transition to a next-generation architecture.
RUBIN COULD EXPAND NVIDIA’S REVENUE PER DATA CENTER
Nvidia’s strategy is increasingly about selling more than GPUs.
Under its earlier Hopper generation, Nvidia estimated its revenue opportunity at roughly:
$18 billion per gigawatt
of AI data-center capacity.
With Blackwell, that rose to around:
$25 billion per gigawatt.
With Vera Rubin, Nvidia estimates the opportunity could reach:
$40 billion per gigawatt.
Why?
Because Nvidia increasingly sells the entire system.
That includes:
GPUs
CPUs
Networking
Switches
NVLink
Software
and
Rack-scale infrastructure.
NVIDIA IS BECOMING AN AI DATA-CENTER PLATFORM COMPANY
This is one of the biggest reasons Nvidia has maintained its dominance.
Competitors can build powerful accelerator chips.
But Nvidia sells a complete ecosystem.
A modern AI data center may use:
Nvidia GPUs
Nvidia networking
Nvidia CPUs
Nvidia software
and
Nvidia management tools.
That increases the amount of revenue Nvidia can capture from each project.
It also makes switching suppliers more difficult.
CUDA REMAINS NVIDIA’S BIGGEST MOAT
Hardware alone does not explain Nvidia’s position.
Its biggest long-term advantage may be:
CUDA.
CUDA is Nvidia’s software platform used by developers to program its GPUs.
For nearly two decades, researchers and engineers have built AI software around CUDA.
That ecosystem includes:
Libraries
Developer tools
Optimization software
and
Millions of trained users.
Companies choosing another accelerator do not simply replace a chip.
They may need to rewrite and optimize software.
That creates significant switching costs.
NVIDIA STILL CONTROLS THE VAST MAJORITY OF THE AI GPU MARKET
Industry estimates cited by analysts put Nvidia’s share of the server GPU market at around:
90% or more.
Some estimates place it closer to:
97%.
The exact figure depends on the market definition.
But there is little dispute that Nvidia remains overwhelmingly dominant in high-end AI accelerators.
That leadership gives the company:
Pricing power
Scale
and
Developer loyalty.
It also creates a target for every major competitor.
AMD IS BECOMING MORE AGGRESSIVE
AMD remains Nvidia’s most direct conventional GPU competitor.
CEO Lisa Su has been rapidly expanding AMD’s AI portfolio.
The company has also been acquiring businesses to strengthen:
AI software
Robotics
Systems
and
Developer tools.
AMD recently agreed to acquire AI startup World Labs in an approximately:
$8.2 billion
stock transaction.
The goal is to build a broader AI ecosystem that can compete more effectively with Nvidia.
AMD still trails Nvidia substantially.
But competition is intensifying.
CUSTOM CHIPS MAY BE AN EVEN BIGGER THREAT
Nvidia also faces competition from its own biggest customers.
Google uses:
TPUs.
Amazon has:
Trainium
and
Inferentia.
Microsoft is developing:
Maia.
Meta is building:
MTIA.
Other hyperscalers are increasingly designing specialized accelerators.
Broadcom is helping several technology giants develop custom AI silicon.
These chips do not necessarily need to beat Nvidia everywhere.
If they can handle certain workloads more cheaply, customers can reduce their dependence on Nvidia.
OPENAI AND ANTHROPIC ALSO WANT MORE SUPPLIER OPTIONS
Large AI developers increasingly use multiple hardware providers.
OpenAI, Anthropic and other frontier labs need extraordinary amounts of compute.
They do not want to rely on one supplier.
That creates opportunities for:
AMD
Broadcom
Cerebras
and custom architectures.
But demand is currently expanding so quickly that Nvidia can lose some market share while still increasing revenue substantially.
That is an important distinction.
NVIDIA EXPECTS 70% REVENUE GROWTH NEXT YEAR
Perhaps the strongest part of the bullish argument came from management’s unusually long-range forecast.
Nvidia expects fiscal 2028 revenue to rise approximately:
70% year over year.
Before Nvidia provided that guidance, Wall Street analysts had expected growth closer to:
44%.
Nvidia rarely guides an entire year so far in advance.
CEO Jensen Huang acknowledged that explicitly.
Management appears unusually confident in the order pipeline.
AWS ALONE PLANS 2 MILLION MORE NVIDIA GPUS
One example is Amazon Web Services.
Nvidia says AWS plans to deploy an additional:
2 million Nvidia GPUs
during:
2027 and 2028.
That is only one major cloud customer.
Microsoft, Google, Meta, Oracle and AI-native cloud providers are also building enormous clusters.
These commitments explain why Nvidia expects demand to remain strong even as revenue approaches unprecedented levels.
AI LABS COULD REPRESENT 25% OF NVIDIA’S BUSINESS
Nvidia expects AI-native companies and frontier labs to become increasingly important customers.
Management says AI labs could account for approximately:
one-quarter of Nvidia’s overall business
next year.
That means Nvidia’s growth is no longer dependent only on:
Microsoft
Amazon
and
Meta.
Companies such as OpenAI and Anthropic are becoming massive infrastructure buyers in their own right.
AI COMPANIES ARE COMMITTING HUNDREDS OF BILLIONS
The scale of spending is extraordinary.
Anthropic disclosed planned infrastructure commitments totaling approximately:
$518 billion
over the coming decade.
Those commitments involve companies including:
Amazon
Microsoft
and
Broadcom.
OpenAI is also pursuing hundreds of billions of dollars of computing infrastructure.
The AI race increasingly resembles an industrial buildout rather than a normal software cycle.
That benefits Nvidia.
AMAZON IS EVEN FINANCING NVIDIA CHIPS DIFFERENTLY
Reuters reported that Amazon is exploring plans to move roughly:
$8 billion worth of Nvidia Grace Blackwell chips
into a special-purpose financing vehicle.
Amazon would potentially lease the chips back.
Why would Amazon do this?
Because AI hardware spending has become so large that companies are seeking new ways to finance it.
The fact that sophisticated financing structures are being built around Nvidia GPUs shows how central the hardware has become to the AI economy.
BUT THAT IS ALSO A WARNING SIGN
The same financing boom creates risk.
If companies need increasingly complex debt and leasing structures to fund AI infrastructure, investors may start asking:
Are returns on AI spending high enough?
AI infrastructure investment is projected to reach enormous levels.
Some forecasts suggest annual spending could exceed:
$1 trillion by 2027.
If revenue from AI applications does not grow fast enough, hyperscalers may eventually slow spending.
That would directly affect Nvidia.
THIS IS PROBABLY NVIDIA’S BIGGEST LONG-TERM RISK
Nvidia does not need AI enthusiasm.
It needs:
AI customers to make money.
Hyperscalers can afford to spend aggressively today because they have enormous balance sheets.
But shareholders will eventually demand returns.
If trillion-dollar spending produces disappointing revenue, capital expenditures could slow.
Nvidia’s current valuation may look inexpensive because investors are already discounting that possibility.
HIGHER INTEREST RATES MAKE THE SPENDING BOOM MORE EXPENSIVE
The macroeconomic backdrop is becoming more difficult.
The U.S. 10-year Treasury yield recently reached around:
5.34%.
That was its highest level in:
24 years.
High interest rates increase financing costs.
That matters because AI infrastructure increasingly involves:
Debt
Data-center financing
Energy projects
and
Long-term leases.
Even giant technology companies have to consider the cost of capital.
NVIDIA’S VALUATION MAY BE CHEAP FOR A REASON
A low price-to-earnings ratio can mean two very different things.
It can mean:
the stock is undervalued.
Or it can mean:
investors believe earnings are near a peak.
That is the central debate surrounding Nvidia.
Bullish investors believe the AI infrastructure cycle has many years left.
Skeptics believe Nvidia is experiencing extraordinary but unsustainable profitability.
Both sides are looking at the same 16.5-times earnings multiple and reaching very different conclusions.
NVIDIA IS ANSWERING WITH A $150 BILLION BUYBACK
Nvidia recently increased its share-repurchase authorization by:
$150 billion.
That brought total remaining buyback capacity to approximately:
$235 billion
through fiscal 2028.
It is one of the largest corporate stock-repurchase programs ever announced.
For perspective, the added $150 billion authorization alone is larger than the market capitalization of roughly:
84% of S&P 500 companies.
The message from Nvidia management is clear:
the company believes it can fund growth and return enormous amounts of cash simultaneously.
NVIDIA ALREADY RETURNED $26 BILLION IN ONE QUARTER
During Q2, Nvidia returned approximately:
$26 billion
to shareholders through:
Share repurchases
and
Dividends.
The company has said it intends to return at least:
50% of free cash flow
to shareholders over time, after strategic uses of capital.
That is becoming another part of the investment story.
Nvidia is no longer only a growth company.
It is increasingly becoming a giant cash-return machine.
BUT BUYBACKS DO NOT GUARANTEE THE STOCK IS CHEAP
A company repurchasing shares can signal management confidence.
But buybacks are not perfect indicators.
Management teams can misjudge valuation.
And repurchases only create long-term value if the shares are bought below what the business is ultimately worth.
The enormous buyback therefore strengthens the bullish argument.
It does not prove it.
CHINA REMAINS ONE OF THE BIGGEST UNCERTAINTIES
Nvidia’s Q3 revenue forecast assumes:
zero Data Center compute revenue from China.
That is important.
China was once a major market for Nvidia.
U.S. export restrictions have sharply limited which advanced chips Nvidia can sell there.
At the same time, Beijing is encouraging Chinese companies to use domestic semiconductors.
That combination creates enormous uncertainty.
NVIDIA SHIPPED VERY LITTLE DATA-CENTER HARDWARE TO CHINA IN Q2
Nvidia disclosed that Hopper Data Center products shipped to China represented:
less than 1%
of Data Center revenue during Q2.
That illustrates how dramatically the market has changed.
Some sales could eventually return if regulations ease.
China is reportedly considering limited approvals for domestic companies to buy certain Nvidia products.
But Nvidia is wisely excluding meaningful China Data Center revenue from its official near-term forecast.
CHINA COULD BECOME UPSIDE — OR PERMANENTLY LOST BUSINESS
If Nvidia regains broader access to China, revenue could exceed current expectations.
But the opposite scenario is equally plausible.
China is investing aggressively in domestic alternatives.
Companies including:
Huawei
and other Chinese semiconductor developers are building competing AI hardware.
Over time, geopolitical restrictions could create two separate AI ecosystems:
one centered on U.S. technology,
and another centered on Chinese hardware.
That would limit Nvidia’s global addressable market.
MEMORY COSTS ARE ANOTHER IMMEDIATE PROBLEM
AI GPUs require extremely advanced memory.
High-bandwidth memory, or:
HBM,
is essential for modern AI accelerators.
Demand has become so strong that memory prices have surged.
Nvidia warned that rising component costs will pressure gross margins.
Management expects margins to bottom around:
71% to 72%
later in the fiscal year.
That is lower than recent levels near:
75%.
72% MARGINS ARE STILL EXTRAORDINARY
Even after the expected decline, Nvidia’s profitability remains remarkable.
Most semiconductor companies would consider:
70%-plus gross margins
exceptional.
Those margins demonstrate Nvidia’s pricing power.
But investors are watching the direction carefully.
If competition increases and hardware costs rise simultaneously, profitability could come under greater pressure.
The market may already be discounting some of that risk.
NVIDIA IS EXPANDING BEYOND GPUS
Jensen Huang increasingly describes Nvidia as a:
full-stack computing company.
The business now spans:
GPUs
CPUs
Networking
Software
Robotics
Automotive computing
and
AI cloud services.
This diversification matters.
If Nvidia can capture more parts of the AI stack, it can continue growing even if GPU market share gradually declines.
NETWORKING HAS BECOME A MAJOR OPPORTUNITY
Modern AI clusters can contain hundreds of thousands of accelerators.
Those chips must communicate extremely quickly.
That makes networking critical.
Nvidia owns:
InfiniBand
and
Spectrum Ethernet
products.
Rubin systems expand Nvidia’s networking content further.
This creates another layer of revenue beyond the GPU itself.
NVIDIA IS ALSO MAKING A BIG ROBOTICS BET
Physical AI is one of Jensen Huang’s biggest long-term themes.
Nvidia believes AI will move beyond:
Chatbots
and
Software agents
into:
Robots
Factories
Autonomous vehicles
and
Industrial machines.
Its Omniverse platform allows companies to simulate physical environments.
Nvidia also sells robotic computing hardware.
If robotics becomes a multitrillion-dollar market, Nvidia wants to provide the computing platform underneath it.
AMD IS CHASING THAT SAME MARKET
AMD’s acquisition of World Labs highlights the competition.
The startup specializes in:
World models
that help machines understand and simulate three-dimensional environments.
That technology can be important for robotics.
AMD is clearly trying to prevent Nvidia from owning the physical-AI ecosystem the way Nvidia dominated generative AI training.
The rivalry is expanding beyond data centers.
THE SOFTWARE MOAT MAY BE MORE IMPORTANT THAN THE CHIP LEAD
Semiconductor leadership can change quickly.
One company can design a faster processor.
Another can leapfrog it a year later.
Software ecosystems are much harder to replace.
Nvidia’s long-term advantage may therefore depend less on:
the fastest GPU
and more on:
developers continuing to build around Nvidia.
CUDA is central.
So are Nvidia’s AI libraries, networking tools and enterprise software.
That ecosystem is what investors mean when they describe Nvidia as “best in breed.”
THE STOCK IS NOT ACTUALLY FAR FROM A RECORD HIGH
There is an important nuance to the word:
“sale.”
Nvidia closed October 2 at approximately:
$233.95.
Its record high is around:
$235.74.
So in absolute price terms, the stock is nearly at a record.
The “sale” refers to valuation.
Not share price.
That distinction matters.
Investors are not buying a stock that crashed 50%.
They are buying a company whose earnings grew faster than its share price.
THAT IS A VERY DIFFERENT KIND OF VALUE STORY
Traditional value investing often focuses on companies whose share prices have fallen sharply.
Nvidia represents something different.
Its valuation multiple fell because:
earnings estimates exploded higher.
That can create what investors call:
multiple compression.
The stock rises.
Profits rise faster.
The P/E falls.
Whether that represents an opportunity depends entirely on whether those future profits actually materialize.
MORGAN STANLEY JUST RESTORED NVIDIA AS ITS TOP CHIP PICK
The bullish view is not limited to Hightower.
Morgan Stanley recently reinstated Nvidia as its:
top semiconductor pick.
The firm maintained an:
Overweight
rating and approximately:
$300 price target.
Its analysts cited Nvidia’s broadening demand across:
Hyperscalers
AI labs
Enterprises
and
Agentic AI.
Again, that price target is an analyst opinion rather than a guaranteed outcome.
NVIDIA IS NOW A $5-TRILLION-PLUS COMPANY
Scale itself becomes a challenge.
Nvidia’s market capitalization is around:
$5.5 trillion.
At that size, adding another 50% in market value would require creating roughly:
$2.7 trillion
of additional shareholder value.
That is larger than the entire market capitalization of almost every company on Earth.
Future percentage gains naturally become harder as a company gets larger.
This is another reason investors are focusing so heavily on earnings growth.
THE BIGGER STORY: NVIDIA DOES NOT NEED TO PROVE AI IS REAL ANYMORE — IT HAS TO PROVE AI SPENDING CAN STAY THIS LARGE
The Nvidia story has changed.
Three years ago, investors were asking:
Is generative AI really going to become a major industry?
That question has largely been answered.
Companies are spending hundreds of billions of dollars building AI infrastructure.
Nvidia is generating nearly:
$100 billion of quarterly revenue.
Its Data Center business alone produced:
$89 billion
in three months.
And management expects another:
70% revenue increase
next fiscal year.
The question is no longer whether AI demand exists.
It clearly does.
The question is whether the spending can remain large enough to justify Nvidia’s future earnings expectations.
That is why today’s valuation is so unusual.
At around:
16.5 times forward earnings,
Nvidia is trading at its lowest multiple in more than a decade despite producing some of the strongest growth numbers ever recorded by a company of its size.
If Nvidia’s 70% growth forecast proves accurate and Rubin continues selling faster than supply can meet demand, the valuation could look unusually inexpensive in hindsight.
But if hyperscalers begin slowing AI investment, custom chips take meaningful workloads, China remains effectively closed and margins compress faster than expected, investors may discover that the low multiple was anticipating slower growth rather than mispricing it.
That is the real debate behind Stephanie Link’s “best in breed on sale” call.
Nvidia is almost back at a record share price — but because its profits have grown even faster, Wall Street is now confronting the unusual possibility that the world’s most valuable company may simultaneously be near an all-time high and cheaper than it has been in more than a decade.