
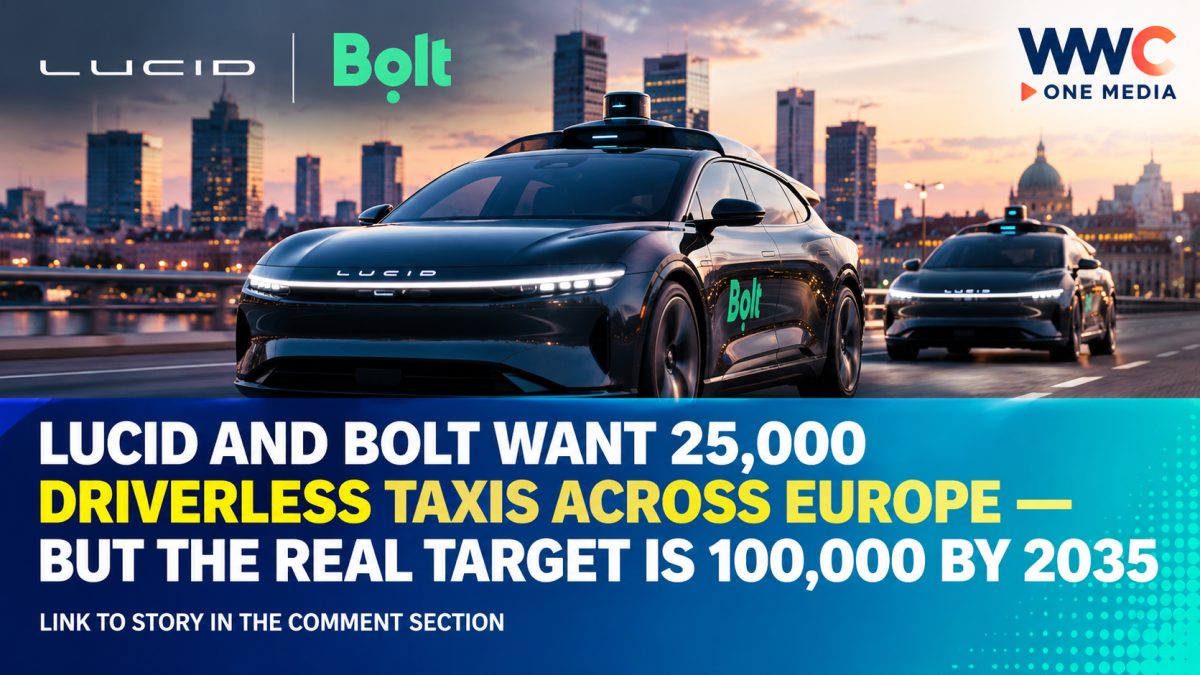
Europe’s driverless-taxi market is moving beyond small demonstrations.
U.S. electric-vehicle maker Lucid Group and European mobility giant Bolt have announced plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, creating one of the continent’s largest announced robotaxi programmes.
The vehicles will be built around Lucid’s upcoming Midsize electric-vehicle platform and are expected to use Nvidia Hyperion, Nvidia’s autonomous-driving reference architecture combining high-performance computing with a standardized sensor package.
Bolt intends to own and operate the fleet, while its autonomous-driving division will help define the vehicles’ software, safety standards, passenger experience and operating requirements.
The announcement immediately caught investors’ attention, with Lucid shares rising about 5.5% in premarket U.S. trading following the news.
But 25,000 vehicles are only one part of a much larger ambition.
Bolt says it wants 100,000 autonomous vehicles operating on its platform by 2035.
These Won’t Just Be Cars With Better Cruise Control
Lucid and Bolt say the vehicles are being designed for SAE Level 4 autonomy.
That distinction is important.
Level 4 vehicles can drive themselves without human intervention within defined operating areas and conditions. A human does not need to sit behind the wheel constantly supervising the system when the vehicle is operating inside that approved environment.
That is fundamentally different from Level 2 driver-assistance systems commonly available in consumer cars today, which can steer and control speed but still require a human driver to remain responsible.
For a commercial robotaxi service, Level 4 is the threshold that matters because it opens the possibility of operating rides without paying a driver for every journey.
And that could radically alter the economics of ride-hailing.
Bolt Will Own the Cars — Not Just Put Them in Its App
One of the most significant details in the agreement is Bolt’s role.
Bolt is not simply planning to list Lucid robotaxis alongside human-driven cars in its ride-hailing app.
The company says it intends to own and operate the autonomous fleet itself.
Bolt Autonomous Driving Solutions will be involved from vehicle development through commercial deployment.
Its responsibilities will include helping specify:
vehicle design requirements,
software requirements,
safety standards,
passenger experience,
fleet infrastructure,
operating systems,
and partnerships with individual cities.
That means Bolt is effectively moving deeper into fleet operations rather than remaining only a marketplace connecting drivers with passengers.
For the traditional ride-hailing model, that is a major shift.
Why Lucid’s New Midsize Platform Matters
The robotaxis will not primarily be based on Lucid’s expensive Air luxury sedan.
Instead, the programme centers on the company’s upcoming Midsize platform, which Lucid sees as critical to increasing production and moving beyond the premium end of the electric-vehicle market.
Lucid said earlier this year that Midsize vehicles are expected to start at below $50,000, substantially less than its flagship luxury products. The company says the platform will use smaller battery packs while targeting strong range, interior space and fast charging.
Those characteristics matter enormously in robotaxi operations.
A fleet operator does not simply care whether a car feels luxurious.
It cares about how much the vehicle costs to purchase, how much electricity it consumes, how often it needs to charge and how many hours each day it can stay on the road earning revenue.
Lucid believes its highly efficient EV architecture can give it an advantage there.
Nvidia Will Supply the Computing Backbone
The proposed vehicle platform is expected to use Nvidia DRIVE Hyperion.
Hyperion combines computing hardware, cameras, radar and other sensors into a standardized architecture intended to support autonomous-driving development.
This is part of a much wider Nvidia push into self-driving vehicles.
Bolt separately announced earlier this month that it plans to use Nvidia DRIVE Hyperion as part of the technology foundation for scaling autonomous mobility in Europe.
That effectively places Nvidia behind the computing infrastructure of yet another major robotaxi push.
The company is no longer benefiting only from AI data centres.
Autonomous vehicles are becoming another market where enormous quantities of AI computing may eventually be deployed at scale.
But Lucid Isn’t Supplying the Full Self-Driving System Alone
Another important detail is what Lucid and Bolt have not yet announced.
They have not named one single autonomous-driving software company that will necessarily provide the complete “virtual driver” for all 25,000 vehicles.
The companies say they expect to work with autonomous-driving technology partners, as well as regulators and policymakers, to bring the service to market.
That makes the partnership different from Lucid’s U.S. robotaxi programme.
In America, Lucid is working with Uber and autonomous-driving company Nuro, where the roles are more clearly divided:
Lucid provides the vehicle,
Nuro provides the Level 4 autonomous-driving system,
and Uber provides the ride-hailing platform and fleet-demand network.
Europe could ultimately involve a broader mix of autonomous-driving suppliers.
And Bolt has already been making deals with several of them.
Bolt Is Building a Robotaxi Ecosystem, Not Betting on One Company
Just two weeks before announcing the Lucid deal, Bolt revealed partnerships involving Stellantis and Chinese autonomous-driving specialist Pony.ai.
Bolt and Pony.ai are preparing autonomous mobility in Europe, while Stellantis is contributing vehicle-engineering and manufacturing capabilities to a testing programme in Luxembourg.
Bolt has also separately partnered with Stellantis on plans to scale Level 4 autonomous vehicles across Europe.
Its broader target remains 100,000 autonomous vehicles on the platform by 2035.
That makes the Lucid agreement easier to understand.
Bolt does not appear to be choosing a single vehicle maker or autonomous-driving company and betting the entire future of its business on it.
It is building a multi-partner platform.
Lucid could provide 25,000 vehicles.
Stellantis could provide others.
Different autonomous-driving technology companies could potentially power different fleets or markets.
That model resembles what Uber has been doing globally.
Lucid Already Has an Even Bigger Robotaxi Commitment From Uber
Lucid’s Bolt agreement is not its first major autonomous-mobility deal.
In April, Uber expanded its commitment to purchase at least 35,000 Lucid vehicles for its future global robotaxi programme.
That expanded an earlier agreement involving Lucid, Uber and Nuro.
Uber also increased its total investment in Lucid to $500 million, while an affiliate of Saudi Arabia’s Public Investment Fund committed another $550 million.
The U.S. programme initially uses the Lucid Gravity SUV equipped with Nuro’s Level 4 autonomous-driving system.
Autonomous testing began in late 2025, and Lucid said in April that the companies were preparing for a commercial robotaxi launch in the San Francisco Bay Area during 2026.
Lucid therefore now has announced commitments tied to at least:
35,000 vehicles for Uber
and
25,000 vehicles targeted by Bolt
That is potentially 60,000 autonomous fleet vehicles across the two programmes, although the agreements have different structures and timelines and should not be treated as 60,000 immediately delivered orders.
Robotaxis Could Become Critical to Lucid’s Survival Strategy
For Lucid, this is bigger than another technology demonstration.
The company is still trying to become sustainably profitable.
Lucid delivered 15,841 vehicles in 2025, despite nearly doubling production from the previous year, and ended 2025 with roughly $4.6 billion in liquidity.
But 2026 has remained financially difficult.
In June, Lucid announced plans to cut about 18% of its U.S. workforce, following an earlier reduction, as it tried to lower costs amid supply-chain problems and a challenging EV market.
That is why tens of thousands of robotaxi vehicles matter.
Lucid does not necessarily need every one of its cars to be purchased by an individual consumer.
It can sell vehicles in bulk to fleets.
It can generate software revenue.
It can license technology.
And autonomous-mobility programmes could produce recurring revenue long after the car itself leaves the factory.
Lucid CEO Silvio Napoli has been reshaping the company around precisely that broader business model.
The 25,000 Figure Is a Target — Not Tomorrow’s Fleet
This is the most important qualification.
Bolt and Lucid did not announce that 25,000 finished robotaxis have already been purchased, built or approved for public operation.
The companies announced a strategic partnership and deployment target of at least 25,000 vehicles.
They have not publicly disclosed the full financial size of the programme.
They have also not provided a detailed city-by-city delivery timetable for the entire fleet.
That means several things still need to happen:
Lucid must successfully launch and scale its Midsize platform.
The Level 4 driving system must be validated.
Cities and national regulators must approve commercial deployment.
Fleet infrastructure needs to be built.
The economics must work.
And passengers need to trust the service.
Those are substantial hurdles.
Europe Has Been Slower Than the U.S. and China
Europe’s robotaxi market is developing later than the largest deployments in China and the United States.
Waymo already operates commercial driverless services in multiple American markets and this week announced an expansion into Las Vegas.
Tesla is also attempting to scale its Cybercab and autonomous ride-hailing strategy, although the company continues to face regulatory scrutiny over vehicle certification.
Chinese companies have meanwhile deployed autonomous vehicles across multiple cities and are increasingly looking overseas.
Europe has generally moved more cautiously.
CNA reported that Uber, Verne and Pony.ai launched robotaxi rides in Zagreb in August, while Waymo is testing vehicles in Munich ahead of a planned German launch in late 2027.
The Lucid-Bolt deal suggests the European market is now moving from small tests toward industrial-scale planning.
Regulation Could Be the Hardest Part
Bolt CEO Markus Villig has acknowledged that Europe’s strict safety and regulatory environment creates a significant challenge for autonomous mobility.
Unlike launching a smartphone app, deploying a robotaxi requires legal approval in every relevant jurisdiction.
Countries can set different rules.
Cities can impose separate licensing requirements.
Insurance and liability frameworks have to be established.
Vehicle behavior has to satisfy local traffic laws.
And regulators need evidence that autonomous vehicles are genuinely safe enough for public roads.
The United Kingdom offers one example of how detailed the process can become.
Under Britain’s Automated Vehicles Act framework, driverless passenger services need authorization, while taxi-style robotaxi operators must obtain consent from relevant local licensing authorities. Britain is also developing formal safety principles for determining whether an automated vehicle is safe enough to operate without human monitoring.
That gives an indication of the regulatory work Lucid and Bolt will face across Europe.
Bolt Says Europe Should Not Simply Import Its Robotaxi Future
There is also a strategic angle.
Villig has argued that Europe should develop more of its own autonomous-mobility capabilities rather than becoming completely dependent on technology imported from the United States or China.
Bolt itself is headquartered in Estonia and operates across more than 50 countries and 850 cities, serving more than 200 million customers across ride-hailing, scooters, e-bikes and car rental.
But the Lucid partnership also shows how difficult genuine European technological independence may be.
Bolt is European.
Lucid is American.
Nvidia is American.
Other autonomy partners could come from Europe, the United States or China.
The future robotaxi may therefore be less about one national technology stack and more about assembling the best combination of cars, chips, software and operating networks from multiple countries.
Why Ride-Hailing Companies Want Driverless Cars So Badly
The economics explain much of the urgency.
In conventional ride-hailing, drivers receive a significant portion of every passenger fare.
They own or lease the car.
They pay fuel or electricity costs.
And platforms such as Bolt or Uber collect a percentage of each ride.
Robotaxis fundamentally change that equation.
If a company owns a self-driving car that can operate for many hours per day without a salaried driver, a much larger proportion of each fare could potentially contribute toward the vehicle, technology, maintenance, charging and platform costs.
That does not automatically mean autonomous rides will be cheap.
The cars themselves are expensive.
Sensors and computing systems cost money.
Remote support may be needed.
Vehicles still require maintenance, cleaning, insurance and charging.
But eliminating or reducing the driver cost is the economic prize that has attracted billions of dollars into autonomous mobility.
The Biggest Winners May Not Be Traditional Car Companies
The Lucid-Bolt structure also shows how the car industry itself may be changing.
Instead of one automaker controlling everything, robotaxis increasingly look like interconnected technology stacks.
Lucid builds the electric vehicle and software-defined architecture.
Nvidia supplies computing and sensors.
A specialist autonomy company may provide the driving intelligence.
Bolt provides customers, fleet management and local operations.
Regulators determine where the vehicles can operate.
The company that captures the most value may therefore not necessarily be the company stamping out the metal body.
It could be the autonomy provider.
The mobility platform.
The computing company.
Or some combination of all three.
That explains why so many partnerships are forming now.
Few companies possess every capability themselves.
The Deal Could Transform Lucid From Luxury EV Maker to Fleet Supplier
Lucid is still best known for expensive consumer vehicles like the Air sedan and Gravity SUV.
But the Bolt deal points toward a very different future identity.
If even a substantial fraction of the 25,000 vehicles is deployed — alongside Uber’s 35,000-vehicle commitment — commercial fleets could eventually represent one of Lucid’s biggest customer categories.
That would reduce the company’s dependence on persuading individual buyers to choose a relatively small luxury EV brand over Tesla, Mercedes-Benz, BMW, Porsche or newer Chinese competitors.
The Midsize platform is already supposed to move Lucid down-market.
Robotaxis could move it into an entirely different business.
But 25,000 Is Not the Number to Watch
The headline figure is impressive.
Twenty-five thousand driverless Lucids operating across European cities would represent a major change in how people move.
But Bolt has already told investors and partners that its destination is much larger.
100,000 autonomous vehicles by 2035.
Lucid is one route toward that target.
Stellantis is another.
Pony.ai is another technology partner.
Nvidia is becoming part of the infrastructure.
Europe’s regulators still have to decide how quickly all of them can move.
So the real story is not that Bolt has ordered enough robotaxis to replace human-driven taxis tomorrow.
It is that one of Europe’s largest mobility platforms is now designing its next decade around the assumption that tens of thousands of rides eventually will not need a driver at all.
Leave a Reply