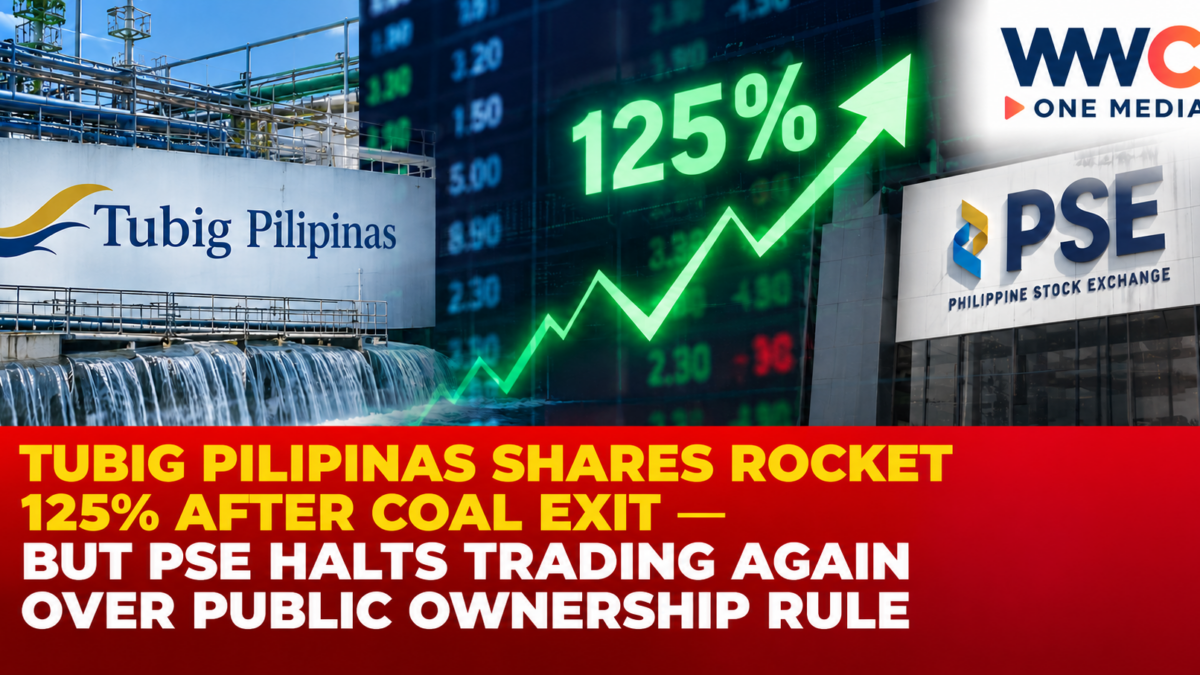
MANILA, Philippines — Tubig Pilipinas Holdings Inc. delivered one of the Philippine stock market’s most dramatic comeback rallies in October, with its shares surging 125% in two trading sessions after a nearly 10-month suspension.
But just as investors celebrated the company’s transformation from coal mining into water infrastructure, the Philippine Stock Exchange (PSE) suspended trading in its shares again.
The new suspension took effect on October 19, 2026, after a ₱6.65-billion share-swap transaction reduced the company’s public ownership to 10.64%, below the 20% minimum required for companies using the exchange’s backdoor-listing route.
The development creates an immediate challenge for Tubig Pilipinas, which is backed by businessman Dexter Tiu and other water infrastructure investors.
The company now needs to restore compliance with the PSE’s minimum public ownership rules, potentially through a follow-on share offering or other fundraising arrangements.
For investors, the biggest question is no longer simply whether a former coal company can become a major Philippine water utility — but whether Tubig Pilipinas can satisfy exchange requirements before its latest trading suspension becomes a far more serious problem.
Shares Hit the 50% Price Ceiling on October 15
Tubig Pilipinas returned to trading on October 15 after its shares had been suspended since December 23, 2025.
The stock previously closed at ₱0.028 per share before the extended suspension.
When trading resumed, demand pushed the price to ₱0.042, the day’s 50% upper price limit.
The move gave the company an estimated market capitalization of approximately ₱1.68 billion, based on its roughly 40 billion outstanding shares at the time.
The rally drew attention because the company was undergoing a fundamental restructuring.
Previously known as Coal Asia Holdings Inc., it was transitioning toward water infrastructure and utility operations through the acquisition of privately held Tubig Pilipinas Group Inc.
The market reaction reflected strong interest in the business transformation, although the available trading data do not establish precisely what motivated each investor.
Stock Jumps Another 50% on October 16
The rally did not stop on the first trading day.
On October 16, Tubig Pilipinas shares surged another 50%, reaching ₱0.063.
That brought the cumulative increase from the pre-suspension closing price to 125%.
Based on the approximately 40 billion shares then outstanding, the company’s market capitalization increased from roughly ₱1.12 billion to ₱2.52 billion.
The implied increase in market value was approximately ₱1.4 billion over two trading sessions.
But the stock’s rise also illustrates why extraordinary price movements require careful interpretation.
A 125% increase in share price does not mean the company earned 125% more revenue or profit.
Nor does a higher market valuation guarantee that its underlying business has improved by the same proportion.
Stock prices can move sharply because of investor expectations, limited available shares, speculative interest and changes in perceived future value.
For Tubig Pilipinas, the market rally was closely associated with the planned transfer of a substantial water infrastructure business into the listed company.
From Coal Asia to Tubig Pilipinas: A Major Corporate Transformation
The company behind ticker symbol TUBIG was formerly Coal Asia Holdings.
Its restructuring involves acquiring Tubig Pilipinas Group Inc., an established private water infrastructure and utility business.
The transaction uses a backdoor-listing structure.
Instead of taking the privately held water business public through a conventional initial public offering, the owners are transferring it into an existing listed company in exchange for newly issued shares.
The result is a substantial change in the listed company’s business activities and ownership structure.
The transaction reflects a strategy to position the company around water distribution, treatment, sanitation and related infrastructure rather than its former coal-related identity.
The corporate name and stock symbol officially changed to Tubig Pilipinas Holdings Inc. and TUBIG effective July 24, 2026.
However, the change in corporate name should not be confused with proof that all former coal assets were immediately disposed of.
The central verified development is the listed company’s acquisition of the water utility business and its shift in corporate purpose.
Inside the ₱6.65-Billion Water Infrastructure Deal
The transaction involves the exchange of shares in Tubig Pilipinas Group for newly issued shares in the listed holding company.
Under the arrangement, Tubig Pilipinas Holdings issued 66.46 billion new common shares to Pure Water Corporation, Quadwater Corporation and CEF2 AO9 B.V.
In return, the listed company acquired 632,352,943 shares representing 100% of Tubig Pilipinas Group’s outstanding capital stock.
The transaction was valued at approximately ₱6.646 billion.
An independent valuation by Isla Lipana & Co. had placed the water business within a range of approximately ₱5.71 billion to ₱6.65 billion, according to earlier reporting.
This is a share-for-share transaction, not a straightforward ₱6.65-billion cash payment.
That distinction matters because the exchange increases the number of shares in the listed company and substantially changes the ownership percentages of existing investors.
The deal also means that investors evaluating Tubig Pilipinas must assess the water business’s operational performance, debt, investment commitments and future cash flows.
Who Controls the New Tubig Pilipinas?
The restructuring involves investors associated with the water infrastructure sector.
Pure Water Corporation is linked to Dexter Tiu’s Pure Energy Holdings.
Quadwater Corporation is associated with Ryan Wesley Yapkianwee, Tubig Pilipinas Holdings’ chairman and president.
The third participant is CEF2 AO9 B.V., an investment vehicle associated with international climate infrastructure investor Climate Fund Managers.
Earlier transaction details indicated that Pure Water and Quadwater would each own approximately 37.65% of the listed company, while CEF would hold roughly 9.36%.
These ownership arrangements significantly increase the influence of the water-business shareholders.
At the same time, the issuance of billions of new shares reduces the percentage ownership represented by existing public shareholders unless they acquire additional shares.
That change became the source of the company’s latest stock exchange compliance problem.
PSE Suspends Trading Again on October 19
The PSE announced on October 19 that trading in Tubig Pilipinas shares would be suspended starting at 9 a.m. that day.
The immediate reason was noncompliance with the minimum public ownership requirement.
Following the issuance of 66.46 billion additional shares, the company’s outstanding shares increased from approximately 40 billion to 106.46 billion.
The public float fell to 10.64%.
For backdoor-listed companies, the applicable PSE minimum public ownership requirement is 20%.
That placed Tubig Pilipinas below the required threshold.
The exchange’s action was therefore not presented as a finding of accounting fraud, business insolvency or wrongdoing by the company.
It was an enforcement measure under its public ownership rules.
The suspension is particularly significant because it followed just two trading sessions of sharply rising share prices.
Existing shareholders cannot assume they can immediately sell their shares at the last recorded trading price while the suspension remains in effect.
Could Tubig Pilipinas Face Delisting?
Under the applicable PSE rules, companies that fail to satisfy the minimum public ownership requirement can be suspended for a period not exceeding six months.
The exchange’s October 19 notice states that a company that remains noncompliant after the suspension period will be automatically delisted.
This creates a clear regulatory deadline and significant consequences for Tubig Pilipinas.
However, delisting is not yet an accomplished event.
The company has an opportunity to restore compliance through the appropriate corporate and market transactions.
The PSE has not announced a confirmed date for the suspension to be lifted.
For investors, this means the immediate priority is monitoring official disclosures about steps to increase public ownership.
Tubig Pilipinas Considers Follow-On Share Offering
The company has said it will pursue fundraising activities that may include a follow-on public offering.
Such an offering could increase the number or proportion of shares held by public investors, depending on its structure and allocation.
AB Capital Securities noted in an October 20 commentary that an earlier fundraising plan contemplated raising approximately ₱1.8 billion.
But the latest offering size, issue price and timetable have not been confirmed.
The eventual financing terms will matter to existing shareholders.
Selling additional shares can improve public float and provide capital for growth.
However, the number of shares offered, the sale price and participation by existing investors could influence ownership dilution and market valuation.
A successful offering could help the company address its regulatory problem.
But until a compliant transaction is completed and the PSE lifts the suspension, the shares remain subject to the trading restriction.
Tubig Pilipinas Operates 12 Water Projects Nationwide
The underlying water business provides the investment story behind the corporate restructuring.
Tubig Pilipinas Group has 12 operating water infrastructure projects across the Philippines.
It also has five projects under construction and another 13 in various stages of development.
The portfolio spans locations in Luzon, the Visayas and Mindanao.
Its operations and development plans include water distribution and related infrastructure services.
The company is also associated with a 25-year joint venture with the Authority of the Freeport Area of Bataan to improve water supply and sewerage systems.
The arrangement illustrates its strategy of working with local authorities and infrastructure partners.
However, the existence of development projects does not guarantee that every project will be completed, profitable or immediately generate substantial revenue.
Performance will depend on customer demand, construction requirements, tariffs, costs, regulatory conditions and financing.
International Climate Investor Supports Expansion
The participation of CEF2 AO9 B.V. adds an international infrastructure investment component to the transaction.
The vehicle is connected with Climate Fund Managers, which focuses on climate-related infrastructure investments.
According to earlier reporting citing the investor’s project information, financing associated with Tubig Pilipinas included approximately $28.4 million in construction equity and $6.9 million for development activities.
The funding is connected with water infrastructure projects in Nueva Ecija, Camarines Sur, Cavite, Palawan and Samar.
The targeted expansion could improve combined water supply capacity serving around 205,000 people.
These figures describe investment commitments and project plans, not the amount of cash automatically received by listed Tubig Pilipinas shareholders.
For the company, international infrastructure funding may support future project development.
But it does not eliminate the need to comply with stock exchange rules.
Why Water Infrastructure Is Attracting Investor Attention
Water infrastructure provides services that communities and businesses rely on every day.
Water distribution, treatment and sanitation require significant investment in facilities, pipelines, equipment and ongoing operations.
As population centers grow, reliable water supply becomes increasingly important for residential development, commercial activity, industrial operations and public health.
Private-sector participation can help finance projects and provide technical expertise.
However, water utilities also operate under regulatory, contractual and service obligations.
Investors must consider project development costs, operating margins, tariff arrangements and long-term maintenance requirements.
Revenue opportunities should not be assumed to translate automatically into guaranteed profits.
For Tubig Pilipinas, becoming a major water infrastructure operator will depend on executing its pipeline and maintaining sustainable operations.
The stock market’s initial enthusiasm cannot replace those underlying business requirements.
What the Share Swap Means for Existing Shareholders
The transaction has substantially increased Tubig Pilipinas Holdings’ number of outstanding shares.
Before the share swap, the company had approximately 40 billion issued and outstanding shares.
After the issuance, the total reached approximately 106.46 billion.
As a result, previous shareholders collectively own a smaller percentage of the enlarged company.
This is called ownership dilution.
Dilution is not automatically harmful if the company acquires valuable assets that increase its overall economic worth.
But investors need to examine whether the value of the acquired water business justifies the new shares issued.
The impact should be evaluated using the post-transaction share count, the company’s combined financial statements and its projected operating performance.
The market capitalization calculated during the October 15–16 rally reflected the pre-issuance share count.
Applying the same prices to the enlarged share count would produce a different theoretical valuation, but that calculation should not be presented as a newly established market price while trading is suspended.
The Bigger Challenge: Investor Excitement Versus Regulatory Compliance
Tubig Pilipinas has generated substantial investor interest by transforming itself from a former coal company into a water infrastructure-focused business.
Its 125% two-day rally demonstrates the strength of the immediate stock market reaction.
Its underlying water portfolio also gives investors a new set of assets and development projects to evaluate.
But the October 19 trading suspension underscores the importance of corporate governance and regulatory compliance.
A company can complete a significant business restructuring and still face obstacles if its ownership structure does not meet listing requirements.
For Tubig Pilipinas, the near-term priority is restoring the public float to the required level.
The longer-term test is delivering reliable water services, completing projects and demonstrating sustainable financial performance.
What’s Next for Tubig Pilipinas?
Investors will be watching for three developments.
First, the company must clarify how it intends to restore the minimum 20% public ownership.
Second, it needs to disclose any follow-on offering or other capital-raising transaction, including its size, price and timing.
Third, it must show how its new water infrastructure portfolio will contribute to revenue, cash flow and earnings.
The PSE’s future decision on the trading suspension will be a key milestone.
For now, the company has completed a major corporate transformation but faces an immediate compliance challenge.
Tubig Pilipinas returned to the Philippine stock market with a 125% rally and a ₱6.65-billion water infrastructure transaction. But the celebration lasted only two trading sessions before another suspension. The real question is whether its shareholders can see the company restore trading — and prove that the new water business can justify the extraordinary market excitement.