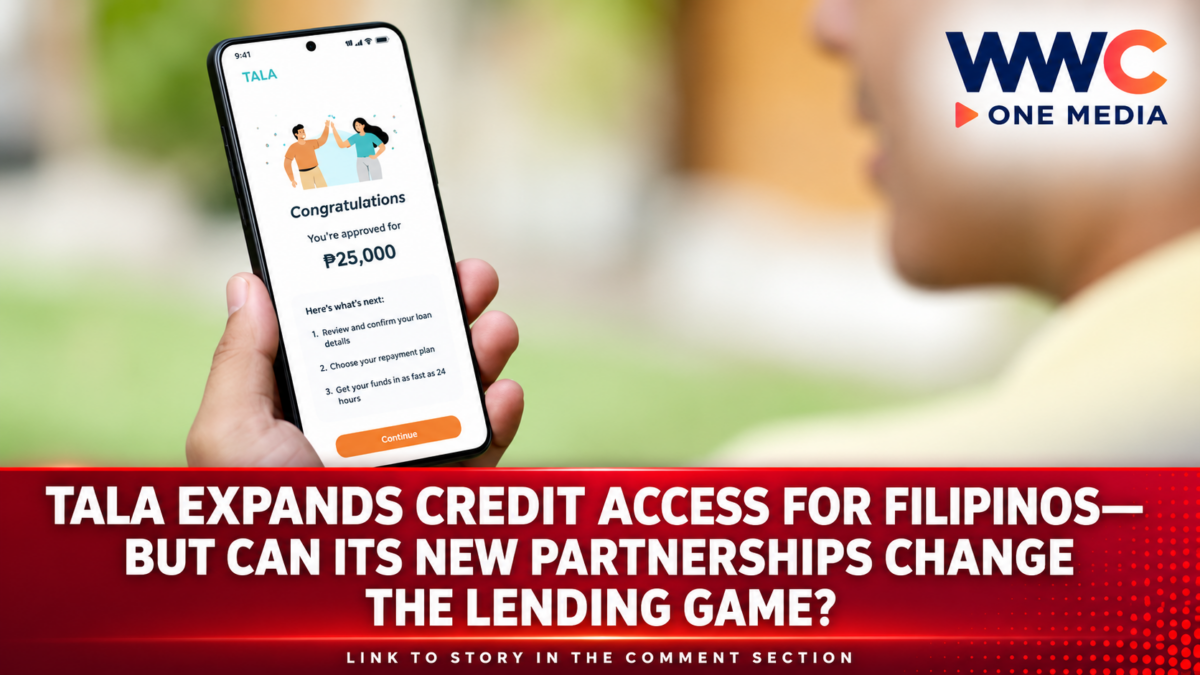
MANILA, Philippines — Access to credit could become easier for more Filipinos as digital lending platform Tala expands its partnerships with banks, financial technology companies, payment networks and other businesses to reach borrowers who remain underserved by traditional financial institutions.
The strategy combines Tala’s artificial intelligence-powered credit assessment technology with its partners’ funding capacity, customer networks and payment infrastructure. The goal is to make formal borrowing more accessible to people whose financial circumstances or limited credit histories may make it difficult to qualify for conventional bank loans.
The initiative comes as financial inclusion in the Philippines moves beyond simply opening bank accounts toward ensuring that people can actually use financial services, including borrowing, saving and managing money securely.
According to figures cited in recent reports about Tala’s strategy, 58% of Filipino adults own a formal financial account. However, account ownership does not automatically guarantee access to affordable credit when households face emergencies or small businesses need additional capital.
How Tala’s partnerships could widen access to credit
A major component of Tala’s strategy is its Credit-as-a-Service (CaaS) platform, which allows partner businesses to integrate its credit assessment capabilities into their own applications and customer networks.
Using application programming interfaces (APIs) or software development kits (SDKs), participating businesses can incorporate lending technology without having to build an entire credit assessment system from scratch.
Tala says its system uses alternative data and proprietary risk intelligence to assess borrowers, including those with limited conventional credit histories. Automated decisions can be delivered within minutes, although approval and loan availability depend on the lender’s assessment and applicable terms.
For borrowers, this model could create additional pathways to formal credit through services they already use. For partner companies, it offers a way to provide financing without independently developing all the necessary lending technology.
Still, faster credit decisions do not necessarily mean every applicant will qualify or that every available loan will be affordable.
Banks, e-wallets and payment channels play a key role
Expanding access to credit also requires reliable ways for borrowers to receive their money.
Tala’s network connects customers with banks, electronic wallets and over-the-counter payment channels, allowing funds to move through both digital and cash-based services. This is important in a country where consumers use different payment methods depending on their location, access to technology and daily financial needs.
InsiderPH
+1
The company is also pursuing loan-channeling partnerships with financial institutions. Under this arrangement, funding partners provide capital while Tala contributes its lending technology, risk assessment capabilities and customer network.
One notable example came in April 2024, when Tala announced a US$48.5-million loan-channeling partnership with Maya Bank intended to expand access to credit for Filipinos. The agreement illustrates how cooperation between digital banks and fintech lenders can help channel institutional funding through alternative lending platforms.
The broader objective is to increase the supply of credit and potentially improve financing efficiency. However, the actual effect on borrowing costs for individual customers depends on loan pricing, fees, repayment schedules and the terms offered.
Tala’s growth reflects continued demand for digital lending
The expansion of partnerships comes amid Tala’s efforts to increase its reach in the Philippine market.
In a March 2026 report, GMA News Online said Tala Philippines was targeting approximately 4.5 million to 5 million customers by the end of the year, up from about 3.5 million to 3.6 million customers at the time of the interview. The company also aimed to grow its loan portfolio by around 30% to 40%, while emphasizing the importance of sustainable growth and keeping non-performing loans stable.
Those figures were company targets, not confirmation of its final 2026 performance.
The demand for digital credit reflects the financing challenges faced by people who lack conventional collateral or extensive credit histories. Small entrepreneurs, self-employed workers and households facing unexpected expenses may find it difficult to obtain traditional loans even when they have income-generating activities.
Tala’s approach seeks to use alternative data to evaluate these borrowers, although the ability to repay remains central to responsible lending.
Financial inclusion must also protect borrowers
Wider access to loans is only one part of the financial inclusion equation. Consumer protection, transparent pricing and responsible debt collection must accompany any expansion in digital lending.
Tala says it works with industry organizations, including the Consumer Lending Association of the Philippines, on initiatives involving responsible lending, fraud prevention and borrower protection. Its Debt with Dignity advocacy also focuses on discouraging abusive debt collection practices.
Regulatory vigilance remains important as digital lending grows. In June 2026, the Securities and Exchange Commission issued an advisory warning against fraudulent online lending platforms and mobile applications illegally using the name of Tala Financing Philippines Inc.
Securities and Exchange Commission
The warning highlights a separate but important risk for consumers: scammers may impersonate established lenders to deceive borrowers. Customers should verify the legitimacy of lending applications and websites through official channels before submitting personal information or making payments.
Borrowers should also review the loan’s effective cost, interest, fees, due dates and penalties before accepting an offer. Easy access to money can help address urgent needs, but borrowing without a realistic repayment plan can create additional financial pressure.
The bigger question: Will easier credit improve financial security?
Tala’s partnership strategy reflects a broader shift in financial technology: instead of relying exclusively on individual lending platforms, companies are connecting credit assessment, funding, payments and distribution through a wider financial ecosystem.
For Filipinos who struggle to qualify for conventional loans, these arrangements could create more opportunities to access formal financing. For small businesses, credit may help cover inventory, operating expenses or other productive needs.
But the long-term success of this strategy will depend on more than customer growth or the number of loans issued. Meaningful financial inclusion requires products that borrowers can understand, afford and repay without sacrificing essential household expenses.
Ultimately, the test for Tala and its partners is whether expanded access translates into responsible borrowing, fair treatment and stronger financial resilience—not simply more people taking out loans.